
Credit contagion returns

In order to see meltdowns coming, you have to be looking for risk. Most financial types are paid to sell risk, not manage it.

Warnings of a high-yield bust were plentiful: The shale driller that missed its first payment. The clothing manufacturer and the software maker among the many companies that issued debt, payable in more debt, earmarked to reward managers who’d already loaded them up with debt.

They had willing buyers, all of them. Investors have poured $240 billion into junk-bond funds since 2008, tripling the total commitment, in a desperate hunt for decent returns while the Federal Reserve pumped $3.5 trillion into the financial system and kept interest rates near zero for seven years. Junk-bond traders helped fund America’s shale boom and gave the cheapest money ever, even to companies deemed by Moody’s Investors Service to be “very high credit risk, poor standing.” Now they’re finding out what happens when the fling is over and everyone wants their money back at once. See: Investors ignored risk of junk-bond rout.  Here is a direct video link.
Posted in Main Page | Comments Off on Credit contagion returns

Bill Black updates on implicit big bank immunity in America

While assisting the prosecution of JPMorgan and Countrywide in Florida by the Department of Justice, TRNN regular Bill Black was dismissed from the case by the assistant US Attorney, who described him as a “Jihadist”. Here is a direct video link.

Posted in Main Page | Comments Off on Bill Black updates on implicit big bank immunity in America

Venture Index ‘gives’ 500: -85% and counting

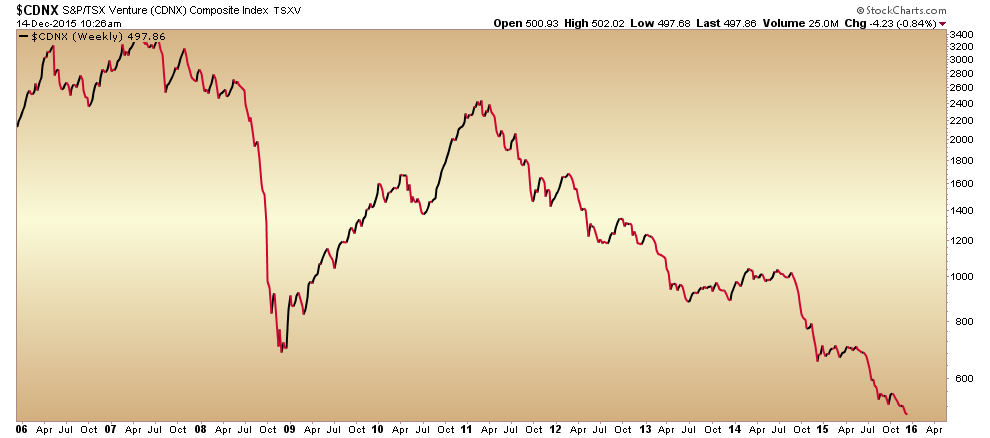
This is what the end of a secular bull looks like.  From a high around 3300 in July 2007, the resource-centric Canadian Venture Index (CDNX) has today broken below 500.  As shown below, it is now some 26% below the great recession low reached in December 2008.
Venture Dec 14 2015
With commodity prices still falling, global demand still slowing and defaults in the high yield debt space just getting starting, further industry consolidation is likely. In other words, the once widely adored Venture Exchange may have even further downside yet to come.  And all of this offers a warning shot to broader financial markets.

Why should we care about excessive credit and speculation driving asset prices beyond reason? Because the most reckless participants and advisers attract followers to their ‘genius’ during the topping phase.  In the end, only the few insiders who cashed out early leave enriched.  The vast majority of participants are left with devastating losses in the process–savings and precious time that they could not afford to lose.

Posted in Main Page | Comments Off on Venture Index ‘gives’ 500: -85% and counting




