Frank: A Life in Politics

I don’t agree with all of Barney Frank’s take on the origins of the financial crisis (he and others under the Bush administration failed to rein in the mortgage underwriting of Fannie and Freddie that played a major role in the excessive leverage behind the financial crisis). I also don’t think that the lengthy Dodd Frank Act that he co-sponsored is sufficient or efficient response to the excessive risk-seeking in the financial sector.  A simpler Glass-Steagall-like division breaking up of the large institutions would be far more effective.  And I believe that will come in the heat of the next financial panic.

But Barney Frank is an intelligent man with a long career of public service, and I respect many of his efforts.  I found the discussion in this far-reaching interview worthwhile.

Barney Frank, former chairman of the House Financial Services Committee discusses his new memoir, “Frank: A Life in Politics From the Great Society to Same-Sex Marriage.” Here is a direct video link.

Last week I visited the Civil Rights Memorial in Montgomery, Alabama on the 50th anniversary of when the King-led marchers from Selma finally arrived in Montgomery.  I was pleased to see that the exhibits included sexual orientation as a key area of present day prejudice and inequality.

“The civil rights movement didn’t begin in 1954 and it certainly didn’t end with Dr. King’s death. It continues through all of us, people of good will, who are committed to the principles of our democracy.”

–SPLC President Richard Cohen, Civil Rights Memorial speech, March 25, 2015
Posted in Main Page | Comments Off on Frank: A Life in Politics

Zell: “I’m looking for demand, and find very little of it”

“There’s a significant and growing disparity between the stock market and the economy,” Billionaire Sam Zell said on CNBC’s “Squawk Box.”

“I’m looking for demand, and I find very little of it.”

U.S. multinational companies are facing significant competition overseas because the euro and the yen have depreciated dramatically, the real estate mogul said. “They’re playing with funny money.”

The dollar index, tracking against a basket of six other currencies, rose nearly 9 percent in the the first three months of the year—logging the best quarter since the third quarter of 2008. In the past year, the euro has fallen about 20 percent against the dollar, while the Japanese yen has dropped 15 percent.  Here is a direct video link.


Here is a direct video link to part 2.

Posted in Main Page | Comments Off on Zell: “I’m looking for demand, and find very little of it”

Financial trainwreck assured: borrowing to ‘invest’ at record highs

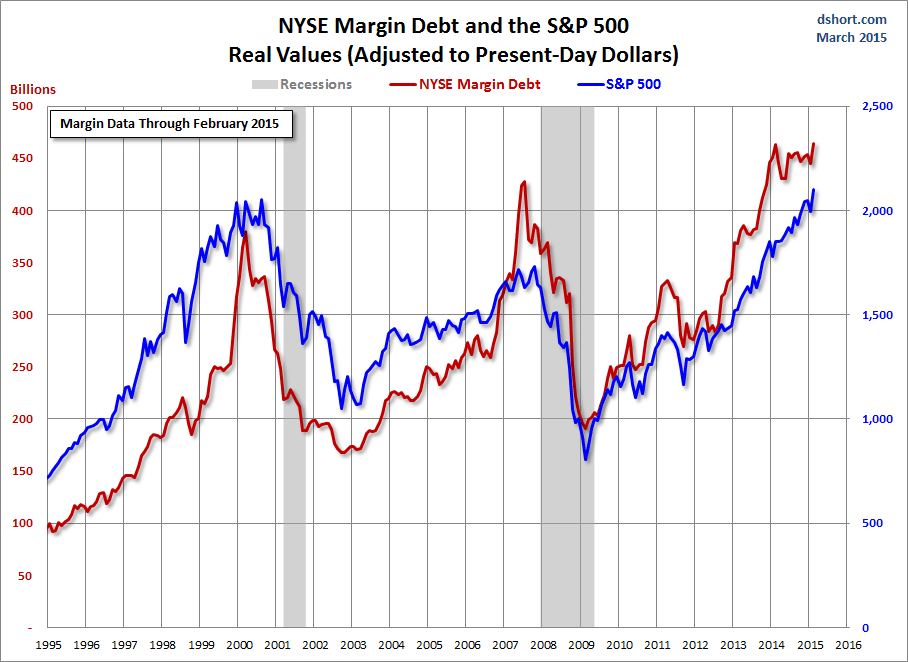
US margin use (borrowing to buy securities) peaked this cycle in February 2014 and has moved ever so slightly lower since.  Historically when margin balances stop expanding, they begin contracting and bear markets have followed within a matter of months.  We saw this pattern (margin debt in red, S&P 500 price in blue, below) in both 2000 and 2007.

NYSE-margin-debt-SPX-since-1995This is a graph of classic ‘investor’ behavior:  as prices rise, people become more confident (and reckless) and start borrowing money in an effort to increase their exposure to market gains.  Unfortunately this also increases their exposure to market losses; and when the ‘hottest’ sectors inevitably sell off, asset values fall and margin calls commence, setting off a cascade of forced selling as holders must liquidate assets and pay back the debt.  Anyone who has ever witnessed this cycle first hand, can attest to its awesome capital incinerating effects.

Even worse, and sometimes on top of margin loans(!), some mortgage their homes to buy stocks and mutual funds (typically after they have already been rising for years).  Usually the ‘strategy’ is recommended by the loan sellers and broker/dealers who make rich commissions when they do.  (No conflicting interests there of course…)

In any event, borrowing to ‘invest’ in financial markets is a very risky bet at the best of times, but doing so when market assets are at all time highs is financially suicidal. Why not mortgage your house to buy lottery tickets while you are at it?

Apparently already debt-drenched Canadians, are oblivious to these facts.  See:  Canadians find new way to binge on debt as borrowing to buy stocks hit record levels.

If you know anyone that is doing this today, send them this article before it is too late. Honestly, this is a front seat on the next financial trainwreck. Run, don’t walk. To wit:

Dennis Colpitts could pay down the mortgage on his house in western Canada early if he wanted. He’s investing in the stock market instead — and in some cases borrowing to do so.

With a mortgage rate of 2.35%, Colpitts said it makes more sense to put his money into stocks or other investments that hold the potential for higher gains. He primarily invests in exchange-traded funds, including through a margin account, which allows him to borrow money from his broker to buy securities.

“I could liquidate all my stocks and ETFs and put them into my mortgage, but I don’t,” said Colpitts, 39, a technology consultant who lives with his wife and two children in Calgary. “I keep them with the hope of getting my 6 or 7% return.”

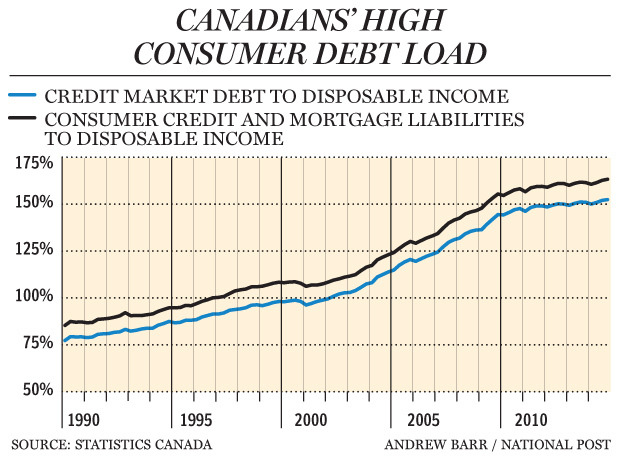
Canadians like Colpitts are borrowing to invest at the highest level since at least 2000, racking up more than $19 billion on margin in January. That’s helped fuel a 37% surge in mutual-fund assets in the past two years and a 41% rise in ETF assets. The figures illustrate Canada’s rock-bottom interest rates aren’t only fuelling house prices and consumer debt to record highs, they’re enticing people to leverage in financial markets.

Cdn debt levels

Posted in Main Page | Comments Off on Financial trainwreck assured: borrowing to ‘invest’ at record highs