2007-2009 bear modest in historical context

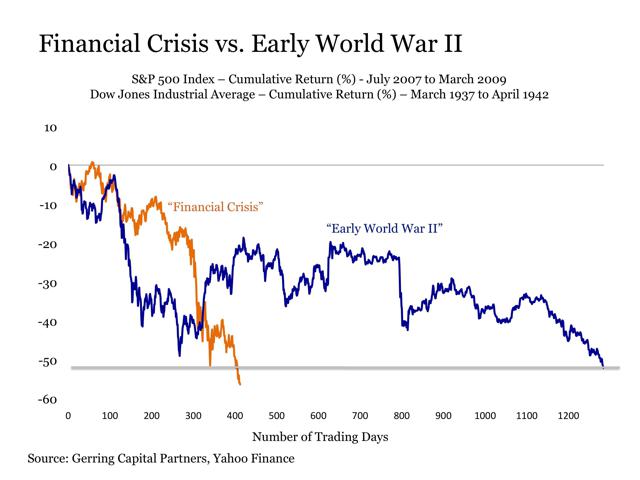
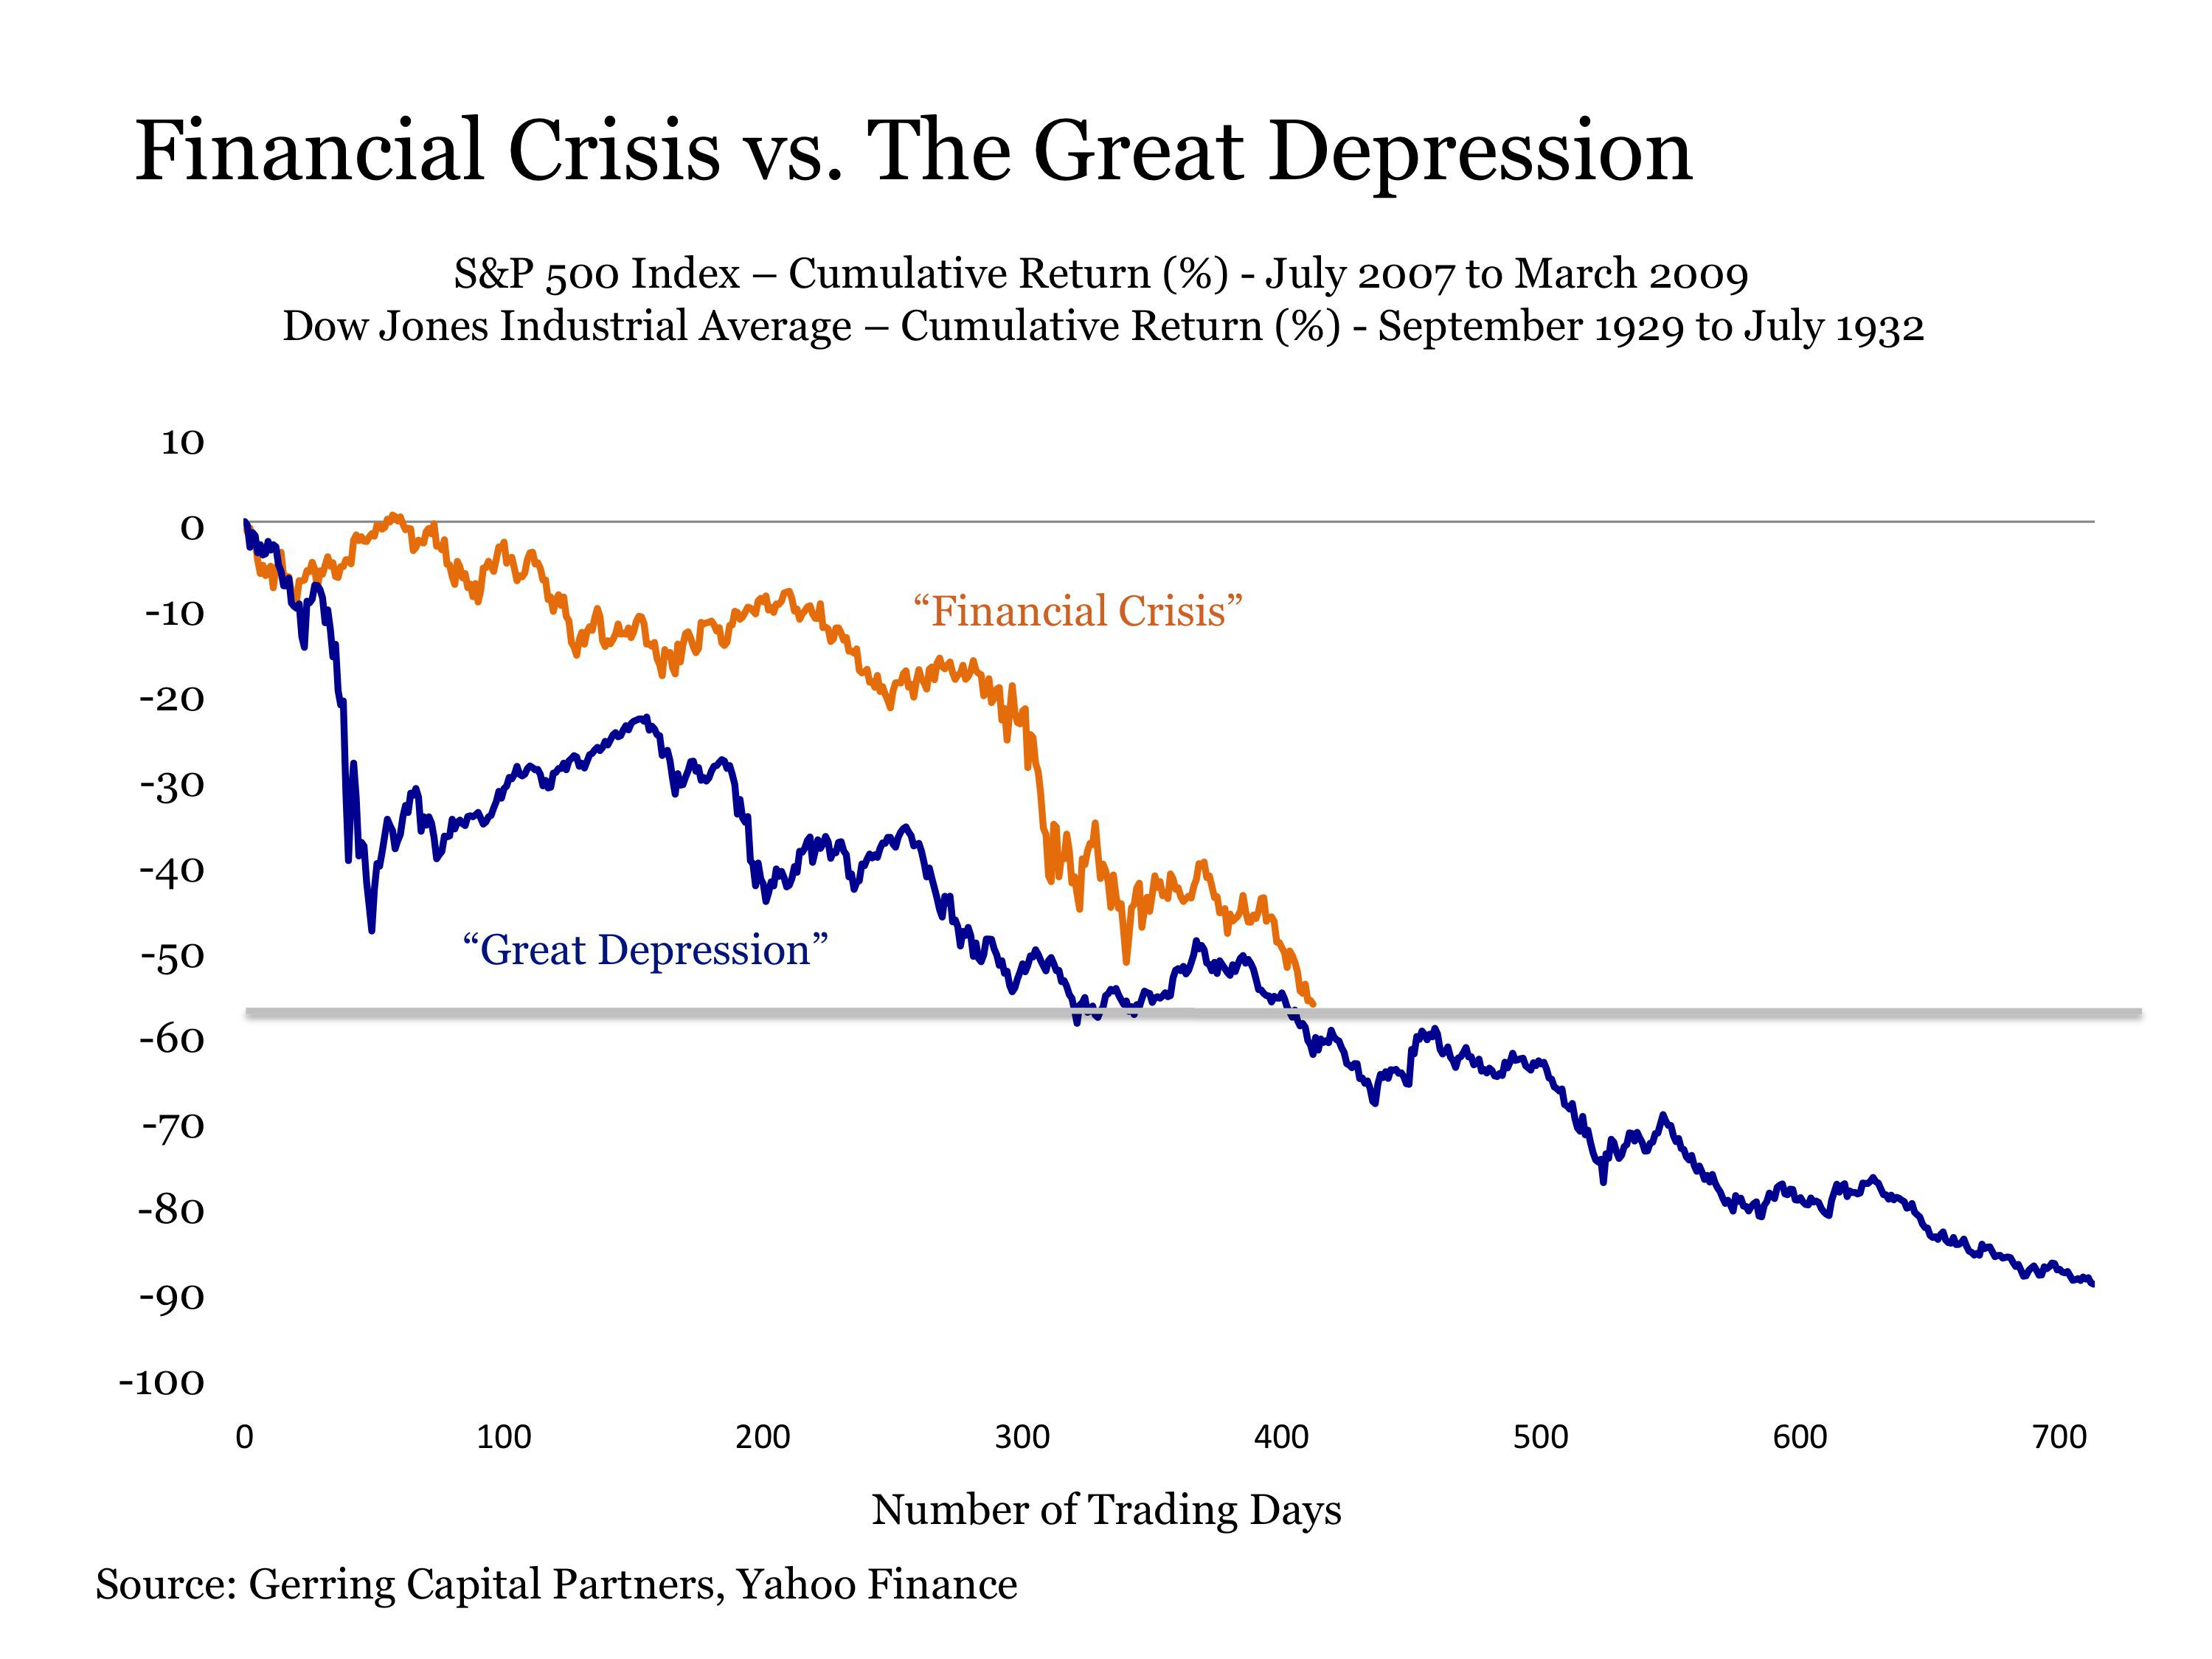
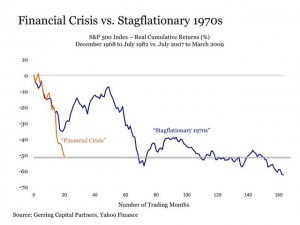
Good historical perspective today from Eric Parnell as he dispels the notion that the bear market of 2009 was an unusual, once in a lifetime occurrence, not likely to be repeated.  Au contraire, in fact the loss cycle of 2007-2009 was actually modest in the context of previous secular bear declines.

See: A crisis less extraordinary and the following great charts, plotting the 2008 decline and duration against other secular bear declines in 2000, the 1970’s, 30’s and 20’s:

2008 vs 20002008 vs 1970s

2009 vs 19422008 vs 1929

“…the only thing that has been truly extraordinary this time around has been the policy response. And this fact alone may be setting investors up for a far more challenging bear market experience the next time around.

…investors should not be lulled into complacency with the thought that the financial crisis was a once in a lifetime event that is not doomed to repeat anytime soon. For in reality, the bear market associated with the financial crisis was not only comparable at worst from a returns perspective, but it lasted only a fraction of the time that other major bear market investors had to endure.

What raises the stakes even further in the current environment is that nearly all of the policy bullets to protect against a weakening economy and sharply correcting stock markets have already been deployed even before the next bear gets started. For unlike in March 2009 when the Fed and other global central banks had the luxury of cranking up the printing presses to flood the financial system with liquidity, such is not at all likely to be the outcome the next time around, as the market may be left to sort things out on its own. This, of course, would not necessarily be a bad thing, as this is how the market cleansing process can finally play itself out in bringing us to the dawn of the next great secular bull market. But investors that are fully allocated in advance of any such day of reckoning stand the risk of sustaining meaningful losses that may not be so easily recovered the next time around.”

Indeed I would argue that the unusually quick rebound in asset prices since 2009 has been counter-productive in several key ways. First, because it has served to quickly re-establish present conditions among the top three most over-valued and dangerous environments for capital since 1929 and 2000. Second, because it has bred extreme moral hazard and over-confidence among participants, reminiscent of the ‘near-miss’ psychological phenomenon described by Malcolm Gladwell where those who were nearly wiped out in the financial crisis, but then revived on central bank bailouts, have now become less fearless and more brazen in their risk-taking. Stay-tuned, this story is not yet finished…

Posted in Main Page | Comments Off on 2007-2009 bear modest in historical context

Reality getting the best of central bankers

We know that the US economy ‘officially’ contracted at an annual rate of 2.1% in Q1 before rebounding on inventory build(restocking not sales) in Q2.

We also now have official confirmation that as of Q2, Italy is back in recession, the Japanese and German economies contracted and France was stagnant with zero growth.

Portugal’s price index slumped 0.7% in July. Spain saw the steepest slide in consumer prices in five years.  See stagnation in the Eurozone here.  Brazil is struggling too, with revised 2014 consensus forecasts recently down to 1.44% versus the 3% forecast last summer.

In the first half of 2014, Russia’s growth slumped to an annualized rate of .85%, the slowest rate in five quarters, and is expected to weaken further in the second half of the year.  Together these economies represent more than 60% of global output as shown here.

World's largest economiesBulls peg hopes on a continuation of higher growth in the UK, China and India.  But with high household debt and weak wage growth in the UK as well as weak domestic demand in China and India, these countries are in need of stronger external demand to support their growth.  That is unlikely to materialize over at least the next year or so.

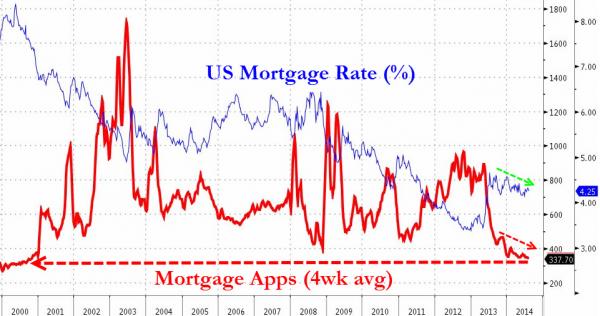
Despite the hype and hope of central bank monetary experiments, the global economy is slowing at a an accelerated pace coming into the second half of 2014. Economic bell weather copper concurs, having fallen more than 32% since 2011 and 7% year to date.  Government bond yields are also deflating with global growth:  the 10 year German bond yield today moved below 1% as the US 10 year yield is back at 2.4% down from 3% 7 months ago. And yet, US mortgage applications–normally expected to surge as rates fall–have not picked up, now at levels last seen in 2000 (shown below).  The golden goose of lower rates seems to have finally exhausted its ability to force increased consumption.

US mortgage rates and apps since 2000
Chart source: www.zerohedge.com

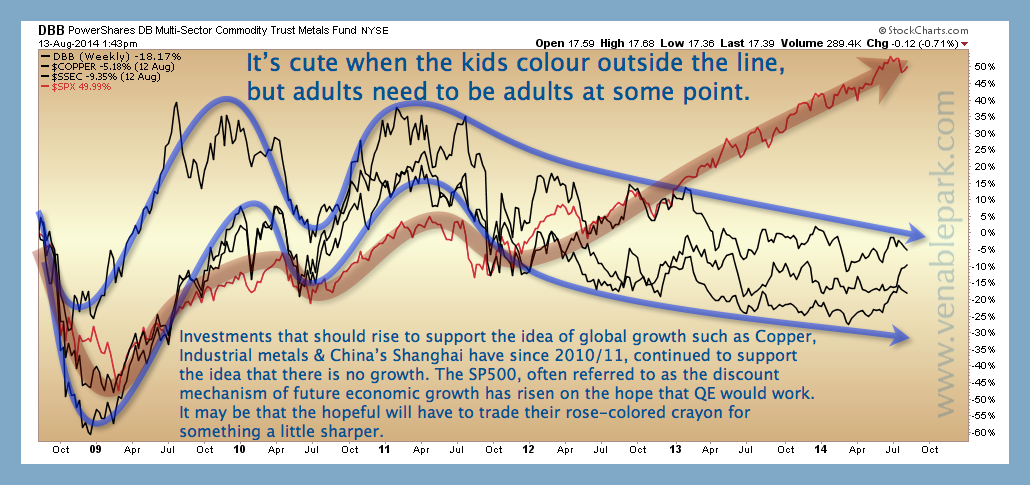
All that remains is for the algo-driven S&P 500 to admit facts and fall back down to reconnect with sales growth here on planet earth. This chart showing the extreme overshoot of large cap North American stocks (here the S&P 500 in red) on QE hopes the past 2 years, as compared with other growth barometers like industrial metals and Chinese stocks, gives a sense of the price risk facing present stock holders. As well as the opportunity coming for those who can design themselves now to be ready.
SPY vs other indicators Aug 14 2014

Posted in Main Page | Comments Off on Reality getting the best of central bankers

Gold: dead or merely pining?

Gold promoters keep promising a return to the golden days of 2011 every day now…but so far a break out in bullion remains illusive. With all the recent news about geopolitical strife and a faltering global recovery, the U$ has continued to strengthen, not collapse as the bugs had predicted.
Gold Aug 14 2014
With QE winding down over the next couple of months, it seems gold’s best hope for the foreseeable future is not likely to be a spike in inflation, but rather ongoing ‘secular stagnation’ in the global economy that might prompt yet another round of desperate ‘liquidity’ experiments out of Central Banks down the road.

But then again, markets would also have to believe that such policies will be successful in order to drive a break out in inflation and gold. So far, some of the other key voters: treasuries (moving up) and copper (moving down) remain unconvinced.

Posted in Main Page | Comments Off on Gold: dead or merely pining?