Rebound running on fumes

With tech and small cap shares down heavily the past few weeks, today many are staging a classic counter-trend rally on vapid volume. Its important to keep in mind however, that no matter what financial sales people tell us, regaining some losses is not the same as making money. This chart of the NASDAQ offers perspective, with volume shown in orange at bottom.
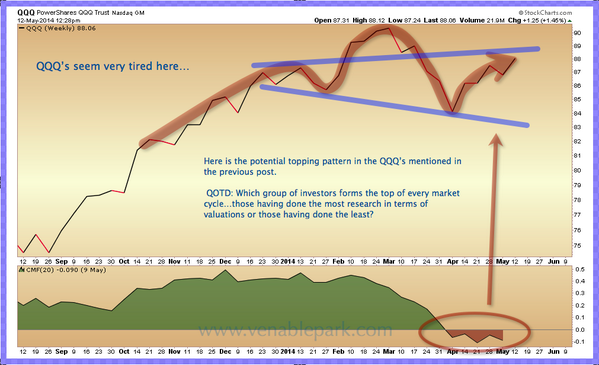
Nasdaq May 12, 2014

Lance Roberts offers a similar appraisal here, see: Is the market consolidating or topping?

While it is certainly possible that the markets could ratchet higher from here due to the “psychological momentum” that currently exists, the likelihood of a runaway bull market from here is remote. What history tells us is that when markets are attaining new highs, the end of a particular bull market cycle is closer than the beginning. It is also worthwhile to remember that getting back to even is NOT an investment strategy.

It is easy to get lured into the casino as the flashing lights and cries of barkers send out the siren’s call that “everyone’s a winner.” However, the difference between a successful gambler and everyone else is knowing that “hot hands” eventually run cold. Knowing when to walk away from the table is what separates success from failure. In both cases, by the time a winning streak gets you back to even, it has generally run the majority of its course. As Nick Dandalos once said:

“The house doesn’t beat the player. It just gives him the opportunity to beat himself.”
Posted in Main Page | Comments Off on Rebound running on fumes

Recession calls and the predictable math of market valuations

The last 18 months of QE-goosed/HFT-abused/insider-trading, wild west, bubbling asset markets have been hard on those using logic, math and historical comparatives to assess likely price moves. The Economic Cycle Research Institute (ECRI) is one of those in the hot seat since their latest recession call in late 2012. Bruised and badgered, ECRI head Lakshman Achuthan is sticking to his call with a small adjustment:

In hindsight, the epicenter of the recession looks to be the half-year spanning Q4 2012 and Q1 2013, which saw just 0.6% annualized GDP growth, mostly from a jump in agricultural inventories. GDP growth for those quarters could easily end up negative after revisions, much of which tend to arrive years after the fact. Nevertheless, just looking at the data in hand, yoy GDP growth during that period fell to lows never seen away from recessions in over half a century. We’ll see how the revisions change the picture in retrospect. See: Business Insider: ECRI’s Achuthan

As market cycle analyst Ed Easterling of Crestmont Research points out the precise timing of market cycles is uncertain but that does not make outcomes unpredictable:

“Secular market cycles are not driven by time, but rather they are dependent upon distance–as measured by the decline in P/E to a low enough level to then enable a significant increase.”

Secular bull markets historically never start until the Price to Earnings ratio for the S&P is below 10. Today at 25.6, valuations on US equities are more than 60% above those found at the beginnings of secular bull markets. Mean reversion in this metric, would imply an S&P 500 Index around 750 (vs. the 1890 range today).

For those hoping that Central Bank interventions have now abolished the traditional valuation cycle and that stocks can continue at a new “permanently high plateau” (as infamously predicted by Irving Fisher in October 1929), the precedents aren’t good. Here’s Easterling:

“…secular bears are driven by longer-term annual trends rather than momentary market disruptions…the stock market has recovered most of its declines from late 2008 and early 2009; therefore it’s now fairly clear that the period in late 2008 and early 2009 was just a cyclical
(short-term) bear market blip within a longer secular bear market. Of course, that makes the period since early 2009 a cyclical bull market inside a secular bear market (it has happened many times before).”See: The P/E Report: Quarterly Review of Price to Earnings Ratio, April, 7, 2014

Posted in Main Page | Comments Off on Recession calls and the predictable math of market valuations

David Suzuki on choices in human evolution

At 78, Suzuki is still fighting every day to enlighten his species.
Here is a direct video link.

Posted in Main Page | Comments Off on David Suzuki on choices in human evolution