Chinese year of the horse a tough one for global growth

The HSBC Flash China Manufacturing Purchasing Managers’ Index™ (PMI™) is the earliest available indicator of manufacturing sector operating conditions in China. In March the reading contracted below 50 for the 3rd consecutive month, now at the lowest level in 18 months.

During the past five years, China accounted for 43 percent of worldwide growth. Now swimming in debt and liquidity constraints thanks to Foreign Reserves that have been mal-invested in risk markets and pledged multiple times over, a necessary slowdown of investment by the Chinese government is reverberating around the world. From Australian miners to South Korean consumer electronics manufacturers, the major beneficiaries of China’s astronomical growth are now the most vulnerable. See: China’s economic hard landing.
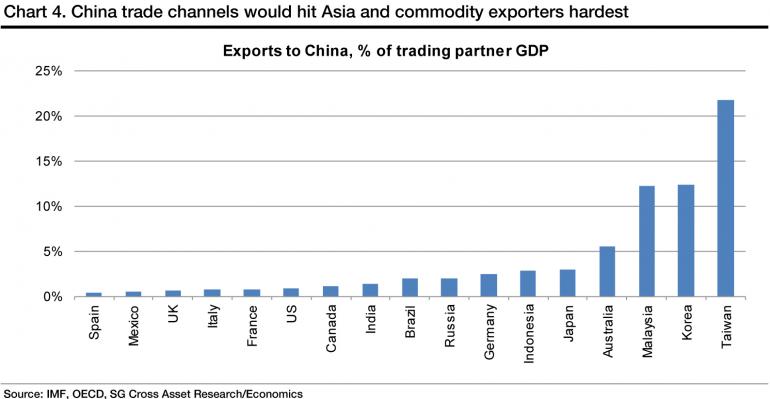
exports-china

Years of poor policy decisions encouraged by a decade of record commodity sales, have left Canada particularly il-prepared for this slowdown. Ray Dalio of Bridgewater Investments recently explained why the next decade is likely to prove a disappointing one for the Canadian economy. See: Hedge fund legend warns of a decade of risk for Canada.

“For more than a decade major global macro pressures have benefited Canada on an absolute basis and relative to the U.S.,” but those conditions “have now left the Canadian economy unbalanced and at significant risk for the next decade.”

The hedge fund firm says Canada’s commodity-dependent economy is in trouble because it is “one of the highest cost producers” meaning that capital investment by energy producers will go to lower cost countries.

“The rest of the Canadian manufacturing economy has been hollowed out to a significant degree due to years of underinvestment, as the commodity-driven surge in the currency made other industries unprofitable,” the note says.

In addition, there is the continuing concern about Canadian households’ high debt levels, and the box that puts the central bank in.

The economy might require further stimulus in the form of interest rate cuts, but lower rates would feed the housing market and borrowing by overburdened consumers.

“Therefore, our likely outlook for Canada is a lagging economy that is just beginning a needed de-leveraging in order to re-balance,” the note says.

American economist Jim Rickards recently explained more on the the downside of the “China Miracle”. Here is a direct video link.

Posted in Main Page | Comments Off on Chinese year of the horse a tough one for global growth

GMO’s Montier: “Hideous opportunity set” advises cash and patience

James Montier, member of the asset allocation team at Boston-based GMO, has a hard time finding attractively valued assets these days. His advice to investors: Cash – and lots of patience.  See:  Equity markets are overvalued by 50 to 70%.

“When we look at the world today, what we see is a hideous opportunity set. And that’s a reflection of the central bank policies around the world. They drive the returns on all assets down to zero, pushing everybody out on the risk curve. So today, nothing is cheap anymore in absolute terms. There are pockets of relative attractiveness, but nothing is cheap or even at fair value. Everything is expensive…

The S&P-500 just keeps drifting upwards. But I think emerging markets are the canary in the coalmine, the first signal. They had been the beneficiaries of these incredible capital inflows. So the fact that they are the first ones to suffer makes sense. It’s not a huge surprise that stock markets in the U.S. have not reacted, because the bond market has not reacted. The bond market seems to think the tapering will turn out fine. Maybe they’re right. But there is no margin of safety in asset pricing these days. That’s no comfortable position to begin a tightening cycle.

Valuations suggest that most people are fully invested today. I don’t see much evidence of people being overly cautious, but a lot more evidence of people getting exuberant. But bear in mind: Owning a large chunk of cash today hurts your performance. Following a value-based strategy requires you to be patient. We know that patience is a rare treat in human beings, and it is extraordinarily rare among investors. Patience hurts. But it is less foolish to do the right thing for the long term, than try to second guess what will happen in the short term.

Several valuation measures suggest that the S&P is overvalued by 50 to 70%. Every piece of valuation I do says this market is too expensive”

Posted in Main Page | Comments Off on GMO’s Montier: “Hideous opportunity set” advises cash and patience

If the NASDAQ screams “sell” does anybody hear?

NASDAQ Mar 21 2014

Posted in Main Page | Comments Off on If the NASDAQ screams “sell” does anybody hear?