Rate cuts come as demand-driven economy slows

The Bank of Canada’s (BOC’s) Business Outlook Survey for the fourth quarter of 2023 found that 40% of Canadian companies were experiencing a slowdown in sales. Indicators of future sales – including order books, advance bookings, and sales inquiries – remain subdued. See: Bank of Canada surveys show weak business environment, lower inflation expectations. The dour outlook for demand is feeding into weaker investment intentions and hiring plans, and most firms no longer feel the need to add staff.

Canadian consumer spending contracted 4% year over year in 2023, even with unemployment still sub-6% and the bulk of mortgages yet to renew at higher interest rates in 2024-2026. A separate BOC survey of consumers found that households are growing more pessimistic about the economy and pulling back on spending. See 2024 in charts.


Spending from 2020 to 2023 was enabled by unsustainable government support for households and businesses and record debt addition in the public and private sector.

The Bank of Canada will soon have to acknowledge that the economy has weakened far more rapidly than it expected. The third-quarter 2023 GDP growth was negative, and the first half of 2024 is looking to follow suit. Already, the unemployment rate has increased by a percentage point since June 2022, and home prices are falling again. According to the Canadian Federation of Independent Business, the proportion of businesses suffering from insufficient demand has rocketed to its highest level since early in the pandemic.

After a period of unprecedented rate hikes, this year will be a story of wage growth slowing as unemployment goes up. That’s according to David Rosenberg, Founder and President of Rosenberg Research. Here is a direct video link.
Posted in Main Page | Comments Off on Rate cuts come as demand-driven economy slows

Danielle’s Biweekly Market Update

Danielle was a guest with Jim Goddard on Talk Digital Network, talking about recent developments in the world economy and markets. You can listen to an audio clip of the segment here.

Further to the discussion of retail investors getting smoked in funds that hold illiquid concepts and securities, see Property sharing investment firm Willow latest to get hit by rising interest rates. More of these to come:

A commercial property-sharing startup aimed at retail investors is the latest real estate venture to face trouble amid higher borrowing costs.

Willow LP, which was acquired by an online rental-services company in late 2023, was part of a new wave of property investing called “fractional investing or prop sharing” that became popular when the pandemic’s spike in property prices enticed more Canadians to invest in real estate.

Unlike real estate investment trusts, in which investors purchase units in an entity that owns a large portfolio of properties, fractional-investing companies give individual investors a chance to own a piece of a commercial property, such as a retail building or office tower. Fractional investing became especially attractive for younger investors.

Willow charged $36.06 to buy one unit of a retail and residential property in a popular shopping area on Queen St. West in Toronto in 2022, according to legal documents it provided to investors.

But now with higher interest rates, hundreds of small investors have seen the value of their investment decline between 50 and 60 per cent, according to a December e-mail sent to Willow investors from the company’s new owner, Montreal-based Solutions Guiker Inc.

Posted in Main Page | Comments Off on Danielle’s Biweekly Market Update

Rate cuts come in response to intensifying financial strife

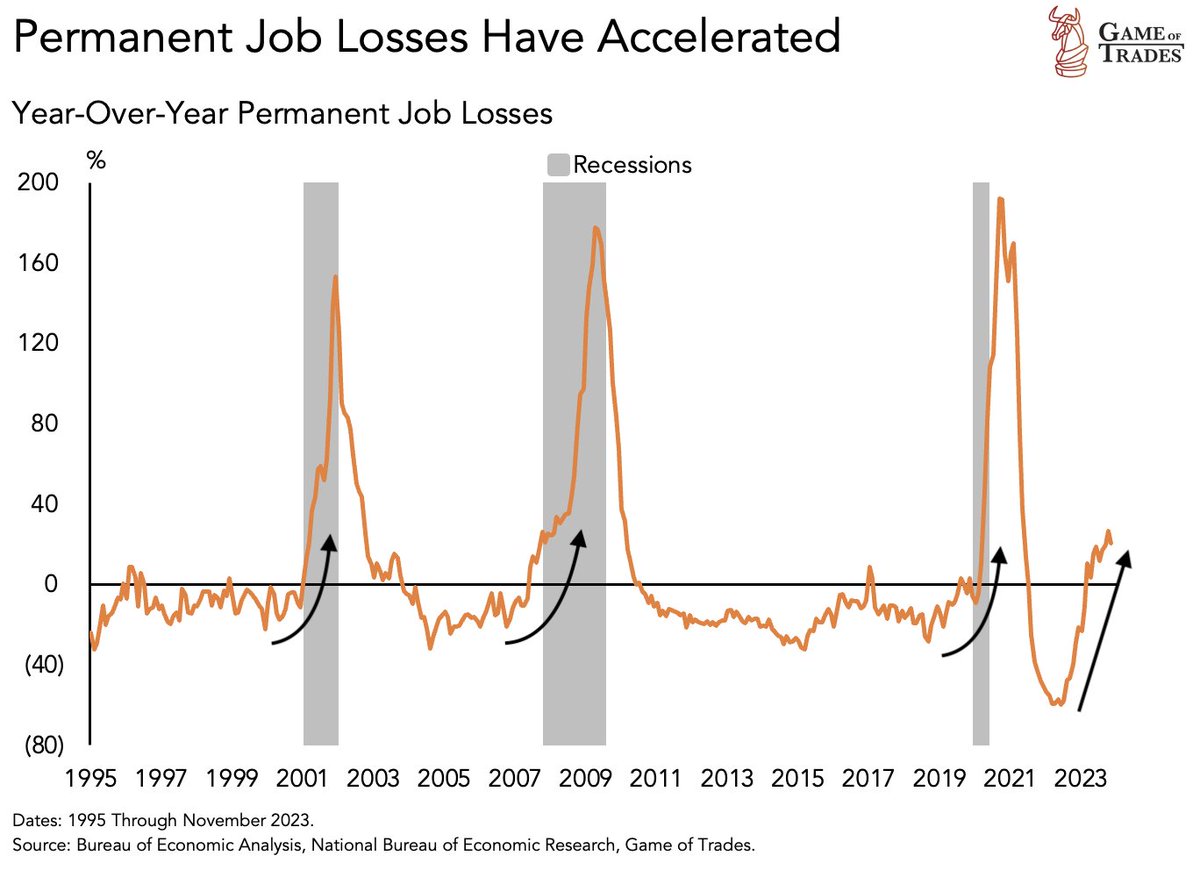
With inflation cooling and unemployment rising, rate cuts are coming into view. Permanent job losses have already accelerated in line with the onset of the past three recessions since 1995 (see arrows and grey bars below, courtesy of Game of Trades). Since 1969, the longest Fed pause time between the last rate hike and the first cut was 14 months (July 2006 to September 2007), and the average was just under five months. Since 1986, the average pause time has been eight months. In all cases, recessions began at or shortly after the first rate cut, with the stock market bottoming 13 to 33 months after the last Fed Hike. March will be eight months since the last hike this cycle, and so far, the stock market remains near its 2021-22 cycle high.

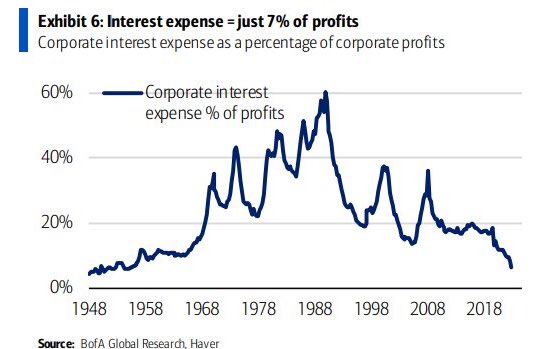
Like households, many corporations locked in term debt when interest rates were at all-time lows in 2020-2021. For this reason, even as rates leapt in 2023, corporate interest payments in the US were just 7% of profits, the lowest share since 1948 (shown below courtesy of Bank of America). This starts to change in 2024 as a record level of corporate debt comes up for renewal every month at higher interest rates. Delinquencies and defaults are rising on all debt types, and this tends to widen credit spreads (lenders demand higher compensation for credit risk/higher rates for borrowers) even as central banks lower overnight rates.
Capital shifting away from corporate credit and equity risk typically flows into government bonds, driving their price up and yields down (10-year yield in red below. since 1989, courtesy of my partner Cory Venable) as recessions unfold (blue bars) and stock markets plummet (S&P 500 in blue).
This hour-long discussion is big-picture rich and worth a mull:

On today’s episode, Danielle DiMartino Booth, CEO and Chief Strategist at QI Research, and George Goncalves Head of US Macro Strategy at MUFG for a discussion on what to expect from the Fed, economy & markets in 2024. Will the Fed be able to avoid a recession as markets price in a soft landing? Here is a direct video link.
Posted in Main Page | Comments Off on Rate cuts come in response to intensifying financial strife