Pension stakeholders beginning to face math

The Ontario Municipal Employee Retirement System (OMERS) is the 4th largest public pension plan in Canada with approximately 60 billion dollars under management. Although it is known as being one of the best run pensions in the country and doubtless has access to some of the best investment opportunities and managers available, it is still struggling to make up losses experienced in the 2000 and 2008 bear markets. Today like most pension funds, OMERS is running a deficit and is approximately 89% funded according to its website here.

An aging population that is living longer than ever before, is presenting unfavorable funding demographics in pretty much every pension in the world, and with 100-year lows in interest rates, low dividend yields and an ongoing secular bear market in stocks, the answers needed are more than just optimistic return hopes. The way back to sustainable plans includes lower benefit amounts, later retirement dates, less annual indexing and increased funding from employers and employees alike. Stakeholders trying to avert contribution hikes at OMERS have recently tabled proposals to lower benefit accruals, extend retirement dates and lower annual CPI indexing by 50%. These are all steps in the right direction although they will be hugely unpopular and hotly contested by union representatives; still facts must be faced eventually. One of the proposals aptly explains the rational for reforms as follows:

The grim economic picture facing Ontario and its citizen impacts on the affordability and sustainability of the current OMERS Plans. This is especially true when it is unlikely that current contribution levels can be reduced to normal cost levels for many years. Infact there is a real prospect that contributions may increase as set out in the 2013 projections.

Current members and their employers should be protected as much as possible against further contribution increases. If earnings of the OMERS plans in the next few years do not surpass on average the assumed rate of 6.5% further increases in contributions and reduced benefits may be required under SPDOS. To attempt to avoid such an occurrence it is proposed to reduce benefits accrued by members to the OMERS plans after December 31, 2015.

Posted in Main Page | Comments Off on Pension stakeholders beginning to face math

McWilliams: the end of austerity the start of opportunity?

Ireland’s Punk Economics Economist and author David McWilliams explains why austerity–without writing off bad debts and bonds and restructuring mortgage debt in exchange for long term equity– has run its predictable course to no recovery:

“Being ‘stuck’, getting punished for doing the right thing; watching those in charge throw good money after bad – and why: if my spending is your income, and your income is mine, the last thing we should be doing is undermining that system.” Here is a direct link.


See McWilliam’s article on the need for debt relief to struggling homeowners: The end of austerity: the start of opportunity?

Posted in Main Page | Comments Off on McWilliams: the end of austerity the start of opportunity?

Buffett explains “the best single measure of where valuations stand” today

Every year the Berkshire Hathaway annual meeting brings a circus of media coverage along the lines of “why Warren Buffett is bullish [always] on America”. As I have pointed out before, part of this is because 55+ years of longevity and a high profile with billions in cash reserves have allowed Berkshire to be a lender of last resort that is able to extract sweeter yields and products than going rates. But also because as a major shareholder in publicly traded companies, Berkshire has necessarily become a long-always fund, unable to easily sell or downsize its positions.

On a personal level, Buffett and his partners are some of the world’s wealthiest billionaires with excellent cash flow who are now more concerned with legacy and tax planning issues than with the standard income and capital preservation needs of mere mortals. However, for those who are buying bullish statements from Berkshire and company, a look at its stock price (not the internal book value Buffett likes to talk about) is reflective of the real life investor experience over the past 10 years of our secular bear in stocks.

Like the S&P 500, after dropping more than 50% in 2009, Berkshire is now just slightly above the high it reached at the last cycle peak in 2007. Most important at this point however, is not that those who held on have just recently managed to recover the capital they lost 5 long years ago, but what is likely to happen to that capital in the next market downturn.

For an indication, we see warnings in a host of reliable valuation tools today. But it is instructive here to look at US stocks with the Oracle of Omaha’s very own stated favorite market valuation metric: “the market value of all publicly traded securities as a percentage of the country’s business–that is, as a percentage of GNP.” Here he is explaining in a 2001 interview with Fortune’s Carol Loomis:

“The tour we’ve taken through the last century proves that market irrationality of an extreme kind periodically erupts–and compellingly suggests that investors wanting to do well had better learn how to deal with the next outbreak. What’s needed is an antidote, and in my opinion that’s quantification. If you quantify, you won’t necessarily rise to brilliance, but neither will you sink into craziness.

On a macro basis, quantification doesn’t have to be complicated at all. Below is a chart, starting almost 80 years ago and really quite fundamental in what it says. The chart shows the market value of all publicly traded securities as a percentage of the country’s business–that is, as a percentage of GNP. The ratio has certain limitations in telling you what you need to know. Still, it is probably the best single measure of where valuations stand at any given moment. And as you can see, nearly two years ago the ratio rose to an unprecedented level. That should have been a very strong warning signal.”

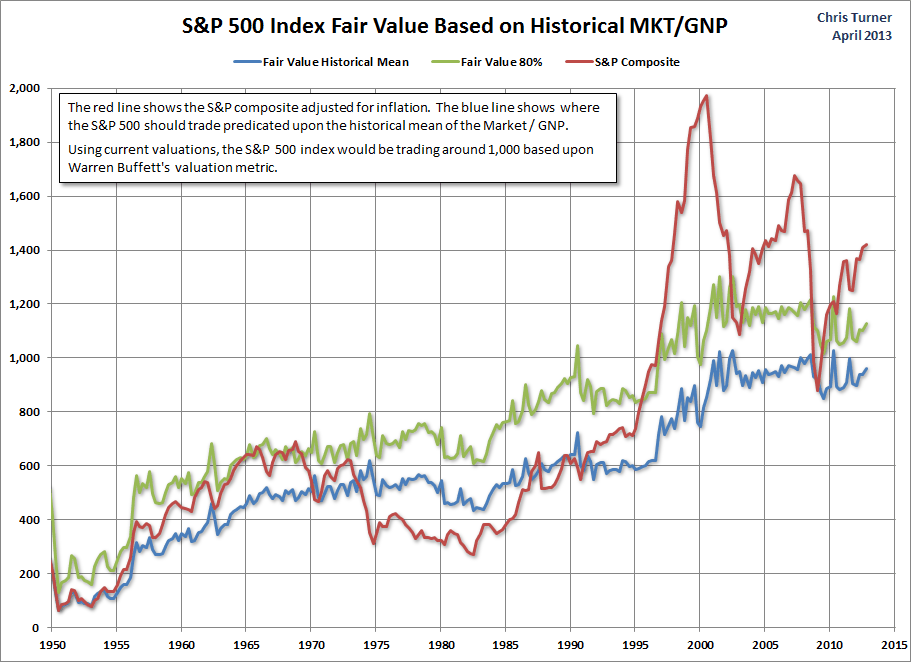
So taking Warren at his word, here is what his preferred valuation tool says about US stocks as a percentage of Gross National Product today:

As plotted by the green line, the S&P 500 should be trading at about 1000 today given present US GNP. So at its present 1616, the S&P 500 is about 38% over-valued. Nothing the next bear market can’t cure of course, but certainly an indicator of probable losses for US stock prices ahead.

US stocks offer good value today Warren? Really? Thanks for the tip.

Posted in Main Page | Comments Off on Buffett explains “the best single measure of where valuations stand” today