Consumer spending and employment downturn in 2024

Consumer spending drives some 58% of Canada’s economic growth and 68% in America, so when households are blindsided by higher carrying costs and deteriorating employment, financial weakness compounds through the economy to lower revenues for companies and governments. See more on the current US job cycle in ECRI, Unveiling the Cyclical Reality of Jobs Growth:

Our research questions the complacency surrounding employment growth, suggesting an impending downturn as cyclical job losses loom. This counters the popular belief in a soft-landing, underpinned by the expectation of job market stability. To resolve the contradictions, we delve deeper into the U.S. employment outlook.

Canadian consumer debt reached $2.9 trillion in the third quarter ($2.2 trillion is mortgages), and households needed 15.4% of their disposable income to cover debt payments compared with 13.6% in 2020 and 13.2% at the US consumer debt peak prior to the 2008 financial crisis. As fixed loan terms come up for renewal at higher interest rates, payments will take an even larger portion of disposable income (see Canada’s mortgage crunch is already hitting the economy–and it’s going to get worse).

Even economists at sell-side bank-broker conglomerates are warning about a consumer-led downturn in 2024 (see a recent segment below of James Orlando, Senior TD Economist, discussing TD’s latest forecast). Here is a direct video link.

Of course, wealth management manglement arms are still recommending customers buy and hold corporate securities with the bulk of their wealth even though equities have routinely lost 40%+ during past recessions. Product-pumpers, got to pump, after all.

Central bank rate cuts will start next year, but there will be no quick fix for what ails here.

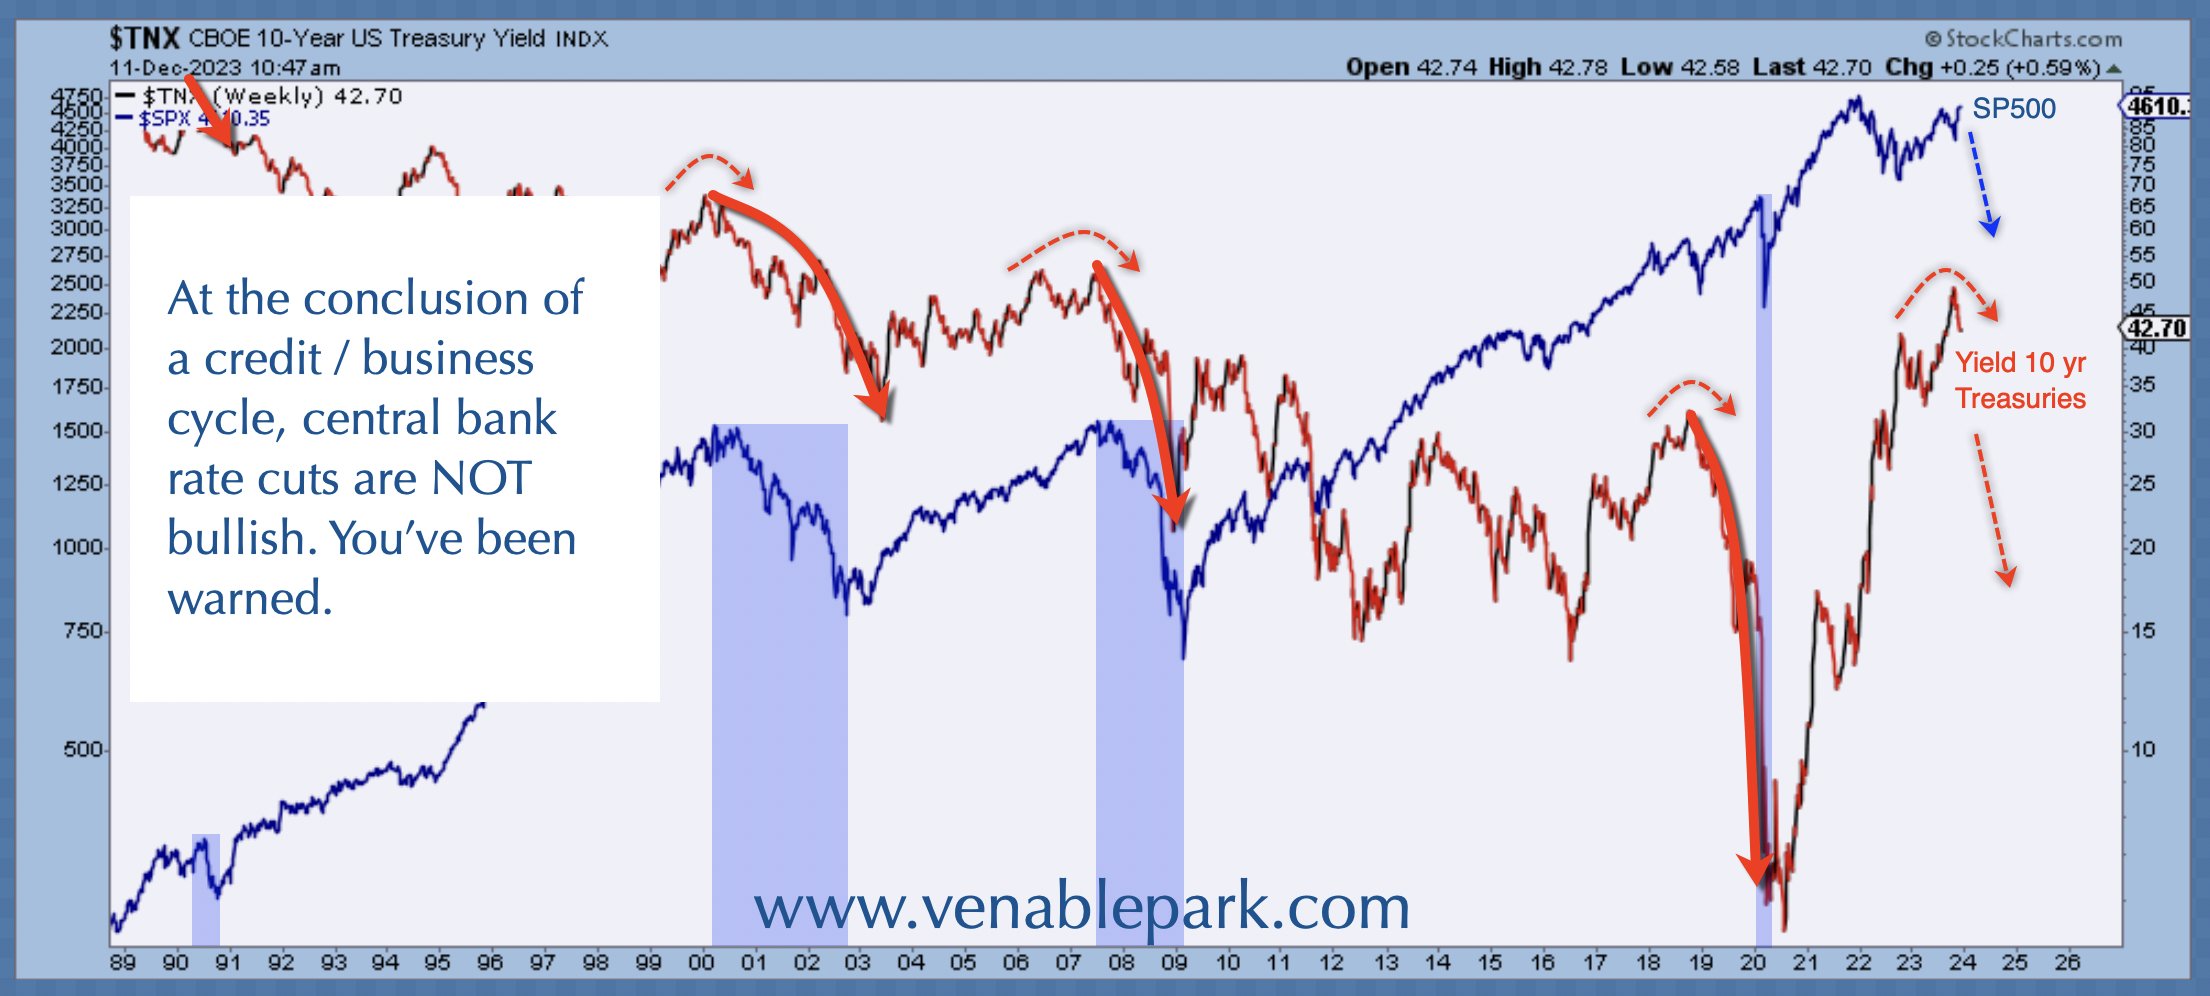
Bond yields set fixed-term loan rates, and it’s typical for the 10-year Treasury yield to roll over near the end of Fed tightening cycles (see red arrows below since 1989, courtesy of my partner Cory Venable) as government bond prices rise–that’s been happening since early October.

Job losses and credit defaults eventually bring central banks back to cutting short-term policy rates, and that’s when stock markets really tumble (S&P 500 in blue below)–more than 80% of bear market losses have historically happened while central banks are easing, not before. Eyes open!
Posted in Main Page | Comments Off on Consumer spending and employment downturn in 2024

Yield curve screaming bear market in process

The US yield curve’s last 17 months of inversion has been the second longest in history (2-10 curve inversion lengths shown below since 1941 courtesy of The Daily Shot).

Ditto for Canada, where the 2s-10s curve has also been inverted since July 2022.

Only four other times in history have seen this degree of inversion, and except for the summer of 1962, every one preceded a recession. Moreover, these incidents were followed by worse-than-average equity and corporate debt bear markets as government bond prices rose.

See, Canada is in economic decay. Prepare for BoC rate cuts and big returns in this asset class. Here’s a taste:

But when the negative gap between longer-term bond yields and rates at the front end of the GoC curve was as steep as it is now, the Canadian economy entered a recession 100% of the time.

Why are the Canadian banks tightening their credit guidelines and boosting their loan loss provisioning of late? Because they are being forward-looking and see things unfolding just as I do.

Economic decay is already underway. Real GDP growth in Canada has slowed markedly on a four-quarter trailing trend basis from a hot +4% pace a year ago to a chilly +0.5% as of the third quarter, as fiscal stimulus lags fade away and the bite from the radical tightening in monetary policy lingers on. This is a stall-speed economy and is either in recession or rapidly approaching one. When you adjust for the immigration-fueled +2.7% population boom, what this means is that the economy, in real per-capita terms, has contracted -2.2% over the past four quarters. You can only camouflage the dismal economic reality via unprecedented inbound migration flows for so long.

Posted in Main Page | Comments Off on Yield curve screaming bear market in process

The end of secular norms

A worthwhile overview of current conditions and implications for asset prices and unemployment in this presentation…

In his Dec. 5, 2023, webcast, DoubleLine CEO and Chief Investment Officer Jeffrey Gundlach (0:06) tours a global environment undergoing a sweeping breakdown of norms that for decades conditioned the behavior of different assets, financing of the U.S. government and performance of the U.S. economy. Here is a direct video link.

Mr. Gundlach begins with the dilemma of the U.S. debt cycle (1:07), “something that is barreling right at us.” He presents a series of charts on federal expense (3:25) interest on U.S. Treasury debt outstanding and adjusting Congressional Budget Office deficit projections for the change in the federal deficit following previous recessions.

By 2028, the deficit could swell to between $3.5 trillion and $4.8 trillion (7:08), equal to 20% of gross domestic product. Mr. Gundlach turns to the question of whether a recession is coming (7:58). This discussion begins with the Treasury yield curve, as measured by yields on the 10-year and two-year Treasury. True to the form of its behavior leading into past recessions, the curve inverted for an extended period and has been de-inverting from a maximum inversion this cycle of negative 108 basis points. By this metric, he suggests that, if the Fed stands pat on rates while the 10-year continues to rally, the completion of the curve’s de-inversion, signaling imminent recession, could occur in “2Q or so of next year.”

Another metric (13:10), the backup of the U-3 unemployment rate, “looks remarkably like the front edge of a recession.”

With respect to markets, Mr. Gundlach disagrees with observers who see record asset levels in money market funds as bullish for risk assets such as stocks (17:47). Moving from Treasury bills into stocks, he says, would be a “monumental change in risk appetite”; rather, he sees the size of assets in money market funds as “bullish for Treasury bonds and other high-quality bonds.”

Posted in Main Page | Comments Off on The end of secular norms