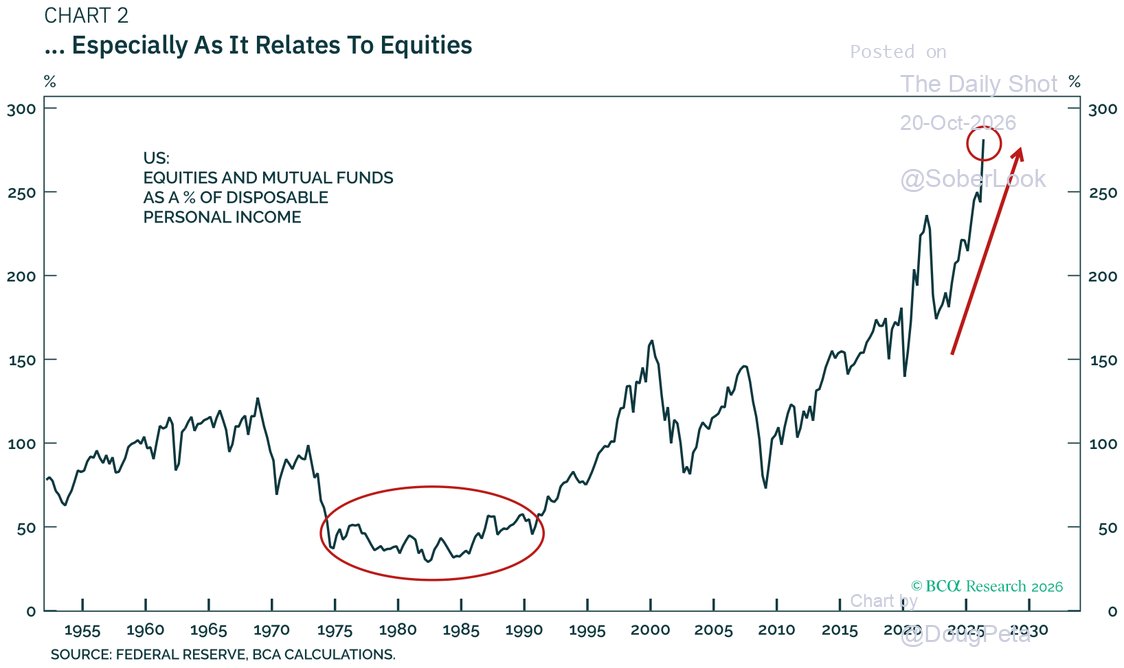
Conventional investment management principles and precepts about equities as long-term growth engines have been a disaster for real life people since at least 1997. Herd think, hubris and investment salesmanship have all helped to move asset prices from undervalued, high probability holdings in the early 80’s to insanely valued, reckless bets by the late 90’s.
Most unfortunately however, for all of those banking that this “bad luck” is now behind us, it is critical to appreciate that a full 15 years later, equity prices today remain in the “most likely to implode than improve capital” category. Although most money gurus and media types seem to exist in a world of fantasy, esoteric theory and denial–for understanding, I find it most helpful to review the math of loss in real money terms for real life people. For reference lets look at a couple of big picture charts. First we’ll start with that bell weather of best businesses in the world: the S&P 500, here:

Source: Cory Venable, CMT, Venable Park Investment Counsel Inc.
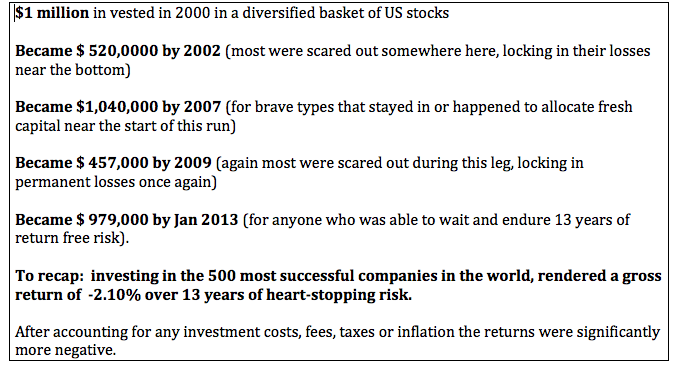
Starting from 1997 to 2000 we see stock prices take off in a parabolic fit of euphoria. All those who had shunned equities or had no investment capital when prices were cheap and then reasonable in the 80’s and early ’90’s came flooding into them in the final three years of the late great bull that ended in 2000. Since then we see that stock prices have been through a series of manic episodes on the road to literally no where. To make this clear, here is the math:
 What about international diversification? Actually the lion share of international markets have fared worse than the US market over this same time frame. A “stand out” in this bunch would be the broad Canadian stock market (TSX composite index) which has slightly outperformed the S&P 500 as shown here:
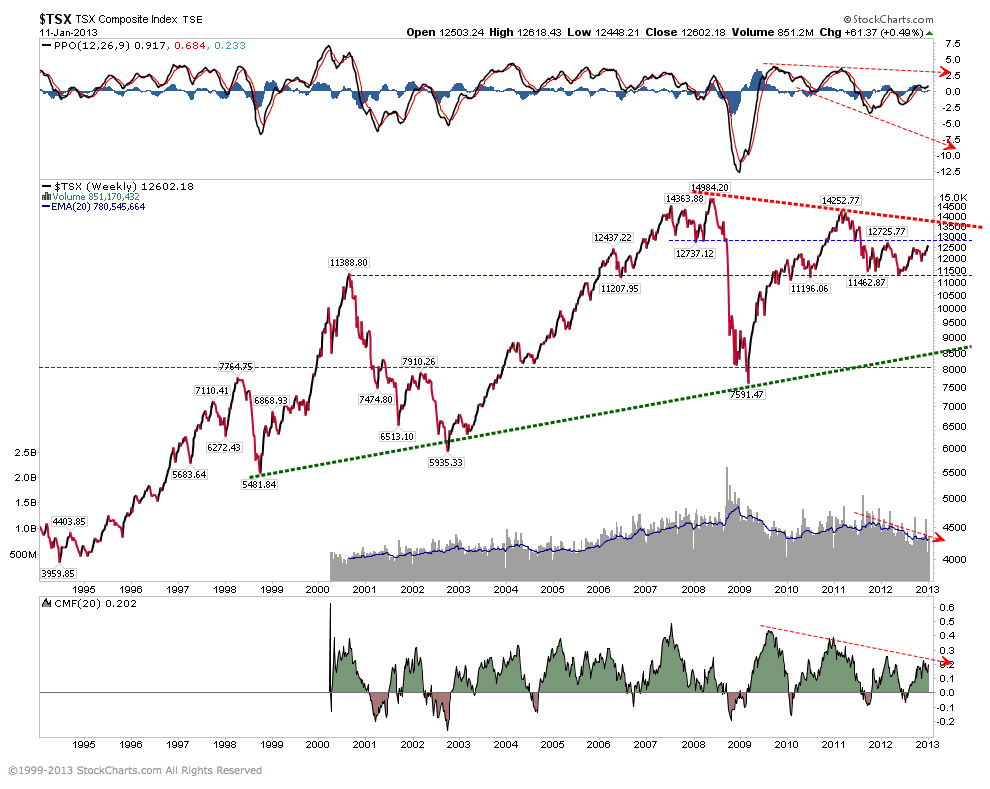
Source: Cory Venable, CMT, Venable Park Investment Counsel Inc.
And here is the real life effect on savings sacrificed invested.
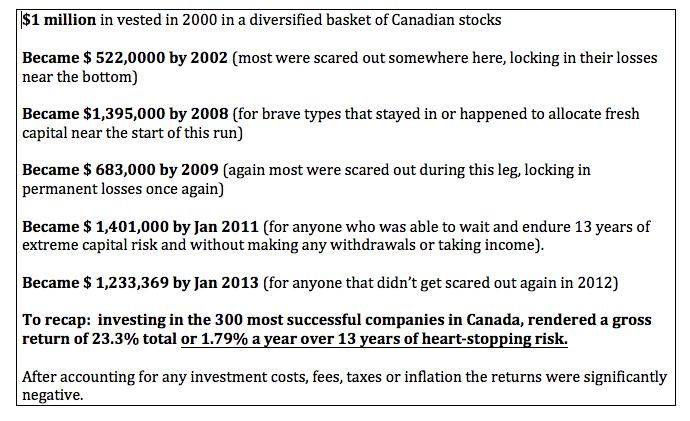
So what is the conclusion here. The facts remain that stocks today are once again dangerously over-valued thanks to central bank shenanigans, herd think, hubris and investment salesmanship. Now back near secular bear resistance, they are most likely to soon begin another major contraction. The history of secular bears tells us, this third down cycle could very likely take stock prices back toward the long term support of about 800 on the S&P 500 (-45% from present) and about 8500 on the TSX (-32% from present). Just imagine what the long term returns will look like for participants once this next leg completes.
The moral of this story is that stocks today are not a good risk/reward at present levels no matter how impatient or frustrated people may be to sit on the sidelines. Only those with the wisdom and discipline to wait and preserve their liquidity now will be able to profit from the next big fire sale when it finally presents. And that is why most will suffer miserably once more.