This week’s letter from John Hussman is worth a read. See Number Five.
“Examine the points in history that the Shiller P/E has been above 18, the S&P 500 has been within 2% of a 4-year high, 60% above a 4-year low, and more than 8% above its 52-week average, advisory bulls have exceeded 45%, with bears less than 27%, and the 10-year Treasury yield has been above its level of 20-weeks prior. While there are numerous similar ways to define an “overvalued, overbought, overbullish, rising-yields” syndrome, there are five small clusters of this one in the post-war record: November-December 1972, July-August 1987, a cluster between late-1999 and early 2000, early 2007, and today. The first four instances preceded the four most violent market declines in the post-war record, though each permitted a few percent of additional upside progress before those declines began in earnest. We do not know what will happen in the present instance, particularly over the short-run. But on the basis of this and a broad ensemble of additional evidence, we estimate that the likelihood of deep losses overwhelms the likelihood of durable gains. To ignore those four prior outcomes as “too small a sample” is like standing directly underneath a falling anvil, on the logic that falling anvils are an extremely rare occurrence….
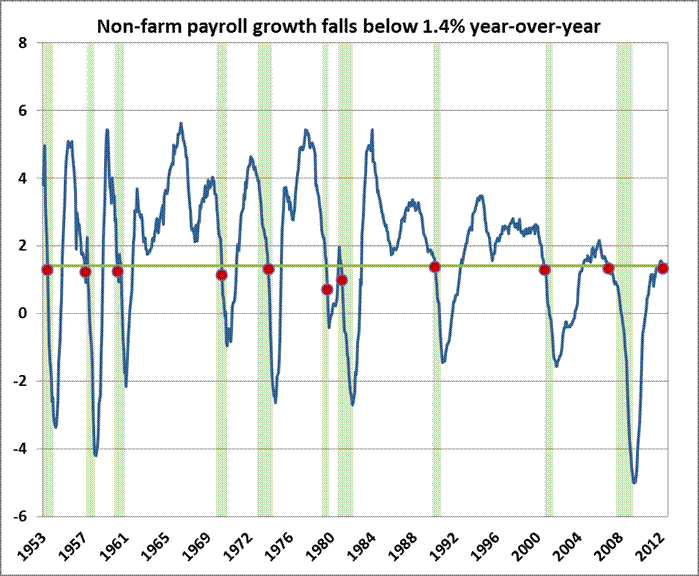
And even if we take the recent employment report at face value, the year-over-year growth in non-farm payrolls is presently just 1.37%, and we’ve never yet seen a decline in payroll growth below 1.4% year-over-year except during or just prior to U.S. recessions[see chart below]. This time may be different, but is difficult to see why that expectation is sensible given the broader context of economic evidence. “