Extend and pretend has magnified economic shock

As interest rates soared above six percent over the last seventeen months, four of the big five Canadian banks have allowed floating-rate customers to extend and pretend by making the same mortgage payments as when floating rates were sub-2%. This has compounded solvency problems as unpaid interest adds to the debt and extends amortization periods beyond prudence.

In their latest quarter ended in July, Canadian banks reported between 23 and 29.8% of their mortgage books with amortizations greater than 30 years, up from virtually zero in 2022. Bank of Nova Scotia is the only of the big five that wisely has not allowed variable payments for floating rate mortgage customers.

Last month, the Office of the Superintendent of Financial Institutions (OSFI) proposed changes to make banks hold more capital to address risks “related to mortgages with growing balances.” Starting in 2024, lenders will hold more capital against mortgages with growing balances and loan-to-collateral values above 65 percent.

Higher capital requirements reduce lender profits and are particularly unattractive at a time when banks are also increasing their loan loss provisions.

Canadian banks are alerting customers that they must bring mortgages into conventional 25-year amortization periods by increasing monthly or lump sum payments—easier said than done for the masses. An estimated C$331 billion in home loans are due for renewal next year alone.

Higher debt-service payments are a headwind for debtors and the overall economy. Royal Bank CEO Dave McKay connected the dots last week: “The industry has a significant portion of mortgages maturing in 2024, 2025 … If rates hold, we’ll pull more disposable income out of the economy and slow it even faster.”

Less spending leads to rising unemployment and more people skipping payments of all kinds. That negative loop is underway now. Defaults and forced sales are growing.

The Canadian financial index (XFN) is, to date, -18% since peaking with Canadian home prices in February 2022. During the 2000-02 and 2007-09 downcycles (where Canadians were much less indebted and property prices much less inflated), the financial index lost about 50% of its market value.

The financial sector’s whopping 31% weight in the broader Canadian stock market (TSX) magnifies capital risk for all of the funds and portfolios designed to track it. But most overlook these dynamics until it’s too late.

Valuable investment opportunities come for those prepared and disciplined enough to wait for them. Such is the test.
Posted in Main Page | Comments Off on Extend and pretend has magnified economic shock

Higher rates freezing mobility and consumption

About seventy percent of Canadian mortgages were taken out over the last few years with a 5-year fixed term and an ultra-low interest rate that averaged 2.79%. In 2020-2021, some 40% were taken at floating rates that averaged 1.65%. Floating and new fixed-term rates are now above 6%. Eighty-five percent of US home mortgages have a 30-year fixed-term taken out when rates were less than 4% versus new term rates above 7%.

Refinancing/equity withdrawals and moving are off the table for the masses since most can’t qualify for new loans at current rates. No wonder that new mortgage applications are the lowest since 1995. See Mortgage Growth Buckles Under Weight of Rate Hikes in Canada.

The housing market is frozen as the number of people reporting it is a good time to buy a home slipped to lows seen just twice since 1960—the recessions of 1973-74 and 1981.

The trouble is that life happens and staying put is not always possible. As layoffs pick up, more people will want to move to downsize expenses or relocate for new employment.

David reviews the lagged impacts of higher rates well in the segment below.

David Rosenberg, Rosenberg Research, joins ‘Fast Money’ to talk about the U.S. economy, the impact of interest rates, slowing employment growth and more. Here is a direct video link.

Posted in Main Page | Comments Off on Higher rates freezing mobility and consumption

Unaffordable prices cure unaffordable prices

Canada’s housing bubble is crystal clear unless you are paid not to see it (wilfully blind) or painfully naive.

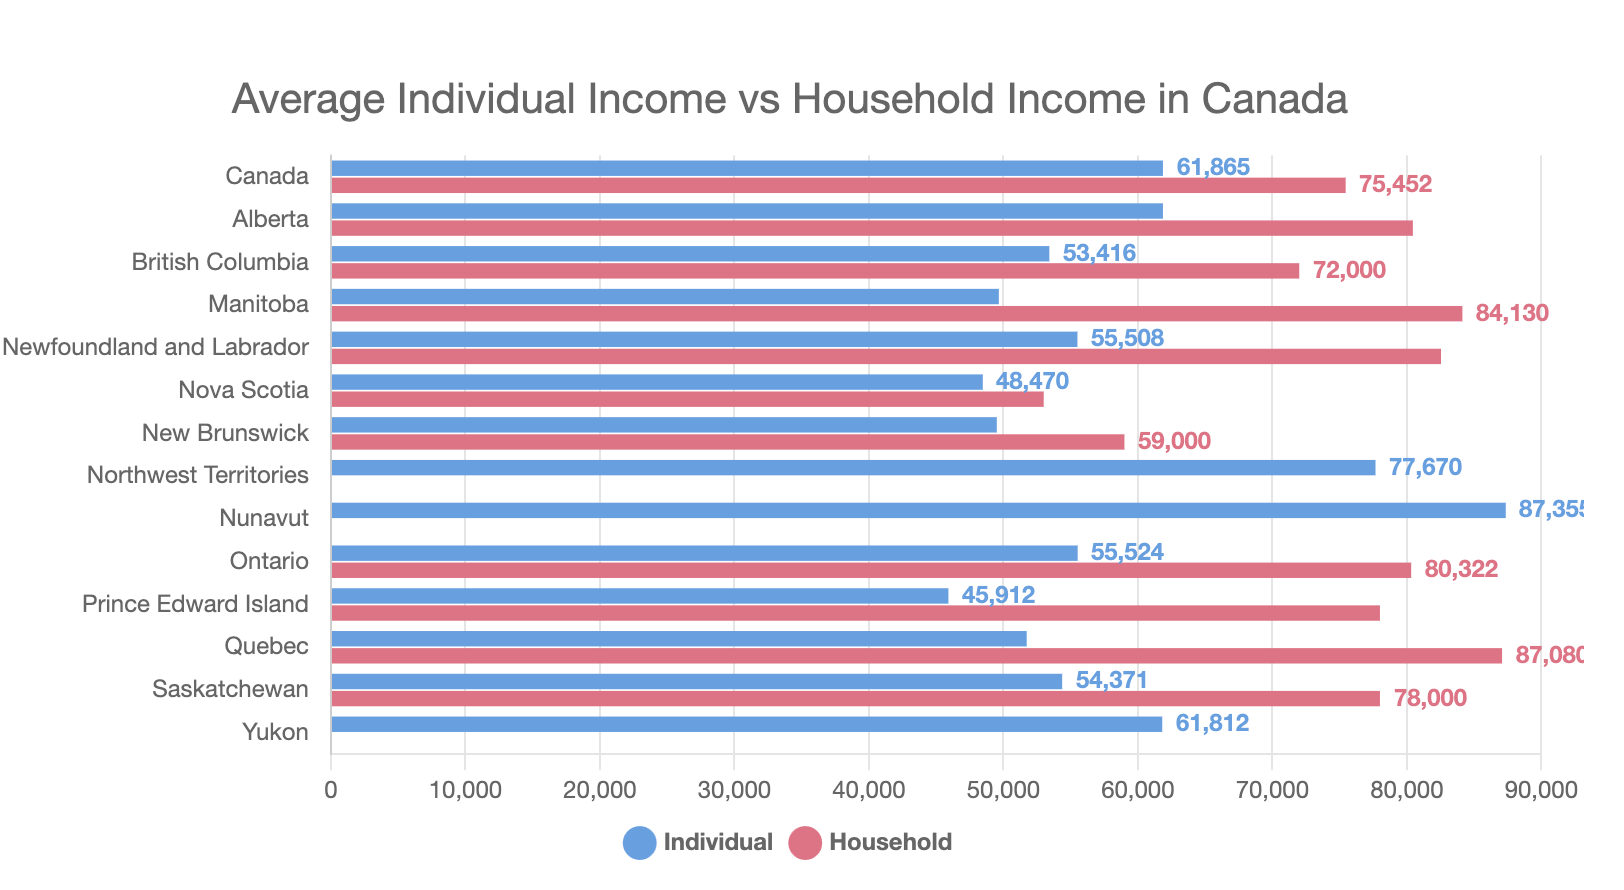
The average national home price of 754K in July is ten times the average household income of $75k. The historically recognized affordability ratio has been home prices that are 3 to 4 times household income; this ratio allows people to pay off their shelter within 25 years and still have some cash flow available for other spending and saving needs. In provinces like Ontario and BC, where the average household income is higher, the average home price is likewise, so affordability is worse. See the table below and more here.

Some seventy-seven percent of Canadian homeowners have a mortgage, and seventy percent were taken out in the last few years with terms coming up for renewal in the next 1 to 5 years. It requires a household income of about $180k (with no other debt) to qualify for a mortgage to purchase or refinance the average Canadian home today. Ninety percent of Canadian households have incomes less than the required 180k.

Historical precedents have ended in multi-year busts where prices tumble greater than 20 percent nationally and more in the most inflated areas.

Lenders, investors and homeowners take losses, bankruptcies spike, and those who are ready buy real estate and related securities at the best valuations in decades from desperate sellers who had leveraged up when prices were high.

It’s important to understand that interest rates do not need to go higher for housing prices to keep falling. The extremity of pricing and leverage in the system has already cast the corrective die. Like driving 200 miles per hour, any wobble or unexpected development is enough to trigger wipeouts.

From a 52-year low last summer of 4.9%, Canada’s official unemployment rate has risen to 5.5% compared with the long-term average unemployment rate of 8%. Job loss will increase over the next year and possibly beyond. The good news is that unaffordable prices are the cure for unaffordable prices. It’s not a question of if, just how long it takes.

Analyst Phillip Colmar delivers wildly unpopular facts well in the segment below. Hate mail is sure to follow.

MRB Partners’ Phillip Colmar explains why he thinks Canada’s real estate market is in a huge housing bubble and what key factors could cause it to pop. Here is a direct video link.

Posted in Main Page | Comments Off on Unaffordable prices cure unaffordable prices