Dr Realist on megathreats and proactive behaviors needed

The below Roubini interview is a thought-provoking discussion on key global issues—many facts to face. I agree with the emphasis on personal discipline in helping lead needed changes. We can navigate the challenges before us if we choose to.

I am more optimistic about the expansion of renewable power than Roubini. I follow many renewable space engineers who are helping ramp up its rollout globally at a much faster pace than most had predicted. And to reduce near-term emissions (as Roubini agrees we must), we cannot afford to wait a couple of decades for new nuclear and fusion to help.

Lastly, I agree that inflation could revive once central banks switch back to easing monetary conditions. But over the next year, at least, disinflation and outright deflation will likely hold the upper hand. This is no time for set and forget. Staying nibble in our allocation decisions is critical.

Nouriel Roubini is an economist, a professor in New York, a global economic consultant and an author who, amongst many distinguishing things, was one of those who foresaw the 2008 credit crunch and financial crisis.

His latest work is called ‘Megathreats’, and it details 10 trends that make it more likely than not that we are heading for a global economic crash of stagnant growth, debt crises and high inflation that will cause decades of dystopian suffering and injustice. No wonder they call him Dr. Doom.

In this episode, Nouriel joins Krishnan to talk about climate change, job-displacing artificial intelligence and our future. Here is a direct video link.

Posted in Main Page | Comments Off on Dr Realist on megathreats and proactive behaviors needed

Fun with stocks and curves

The S&P 500 is down just over 20% since January 4th and a seasonally unusual -6.4% month to date. Under the hood, the most widely held stocks are leading the descent. The top five most expensive S&P 500 companies are now:

  1. Apple (6.23% of index) -27%
  2. Microsoft (5.65% of index) -28%
  3. Amazon ( 2.42% of the index) -50%
  4. Berkshire Hathaway B (1.67% of index) -16.7%
  5. Alphabet A (Google) (1.67% of index) -39%

Other 2021 darlings have slipped significantly; here are just a few standouts:

Nividia -46%, Tesla -63%, Meta -70% and Netflix -52%, Uber -43%, Disney -45%,

You might think prices may be nearing a cycle bottom. While that could be possible for an individual name, it is improbable for the market overall. And in a world of highly leveraged global participants holding a ton of increasingly illiquid assets, selling pressure typically spreads from what people would like to sell to whatever assets they can–making no company or sector protected from liquidation.

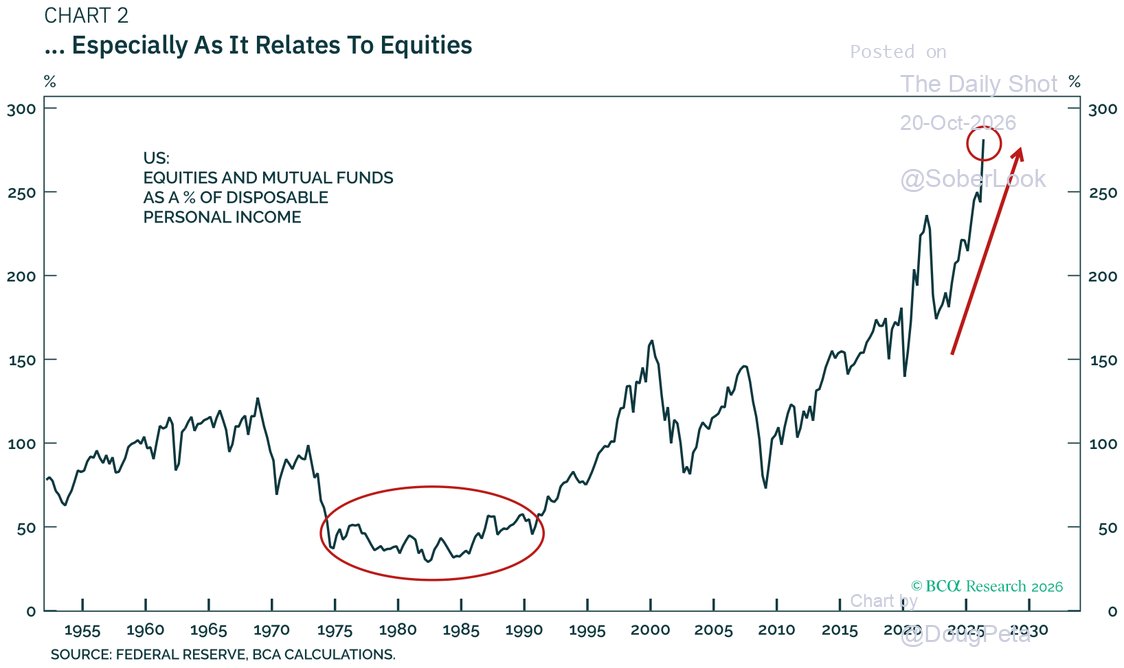
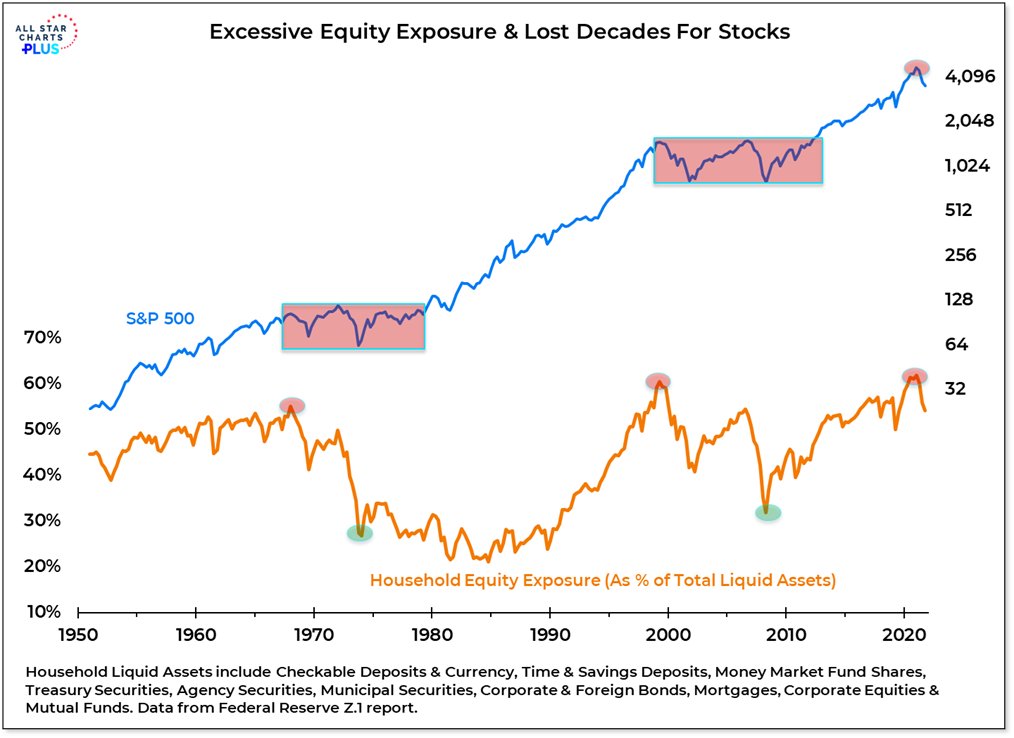
Sentiment reports may appear bearish, but equity positioning, especially in household portfolios, remains (as shown below in yellow) near the secular peaks of 1966, 2000 and 2022. There’s much panic selling yet to come.
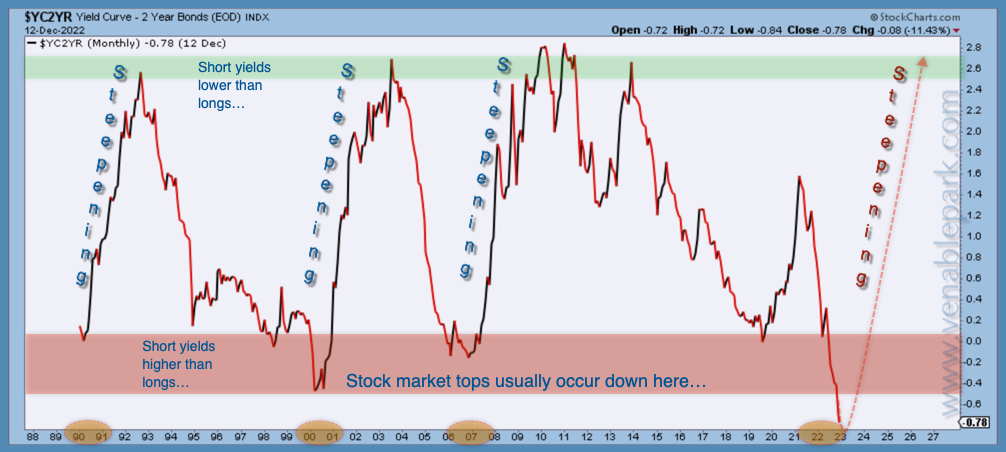
One of the most historically reliable indicators that a bottom is not yet nigh is that Treasury yield curves remain deeply inverted worldwide.

The US two and ten-year yield spread is shown below since 1988, courtesy of my partner Cory Venable. As highlighted in green, with dates circled along the lower axis, stock markets historically bottom after central banks have responded to slowing growth by slashing short rates enough to drop the front end and re-steepen the yield curve once more. Today, the US Fed is still tightening, and the yield curve is profoundly negative, even more than in the stock market tops of 1990, 2000 and 2007.
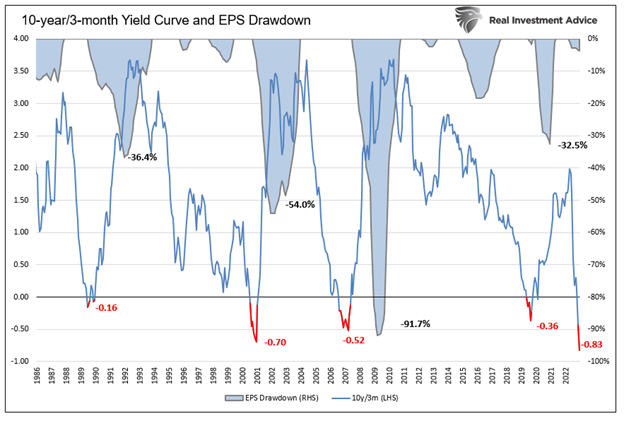
As curve inversions (blue line below since 1986) mark the onset of recessions, they have historically also led an average 25% decline in earnings per share (EPS). As shown below (blue bars) courtesy of Lance Roberts, the drawdown in S&P 500 earnings to date has been tiny in the big picture. At this point, 2023 consensus forward EPS estimates have moved from a delirious $250 down to still optimistic $203. A 25% average cycle drawdown from the peak would mean 2023 earnings of $187 a share. At a forward PE of 15, this would put the S&P cycle low around 2805, some -26% from here. A 12 PE, typical of other cycle bottoms, would see the S&P around 2204, -42% from here.
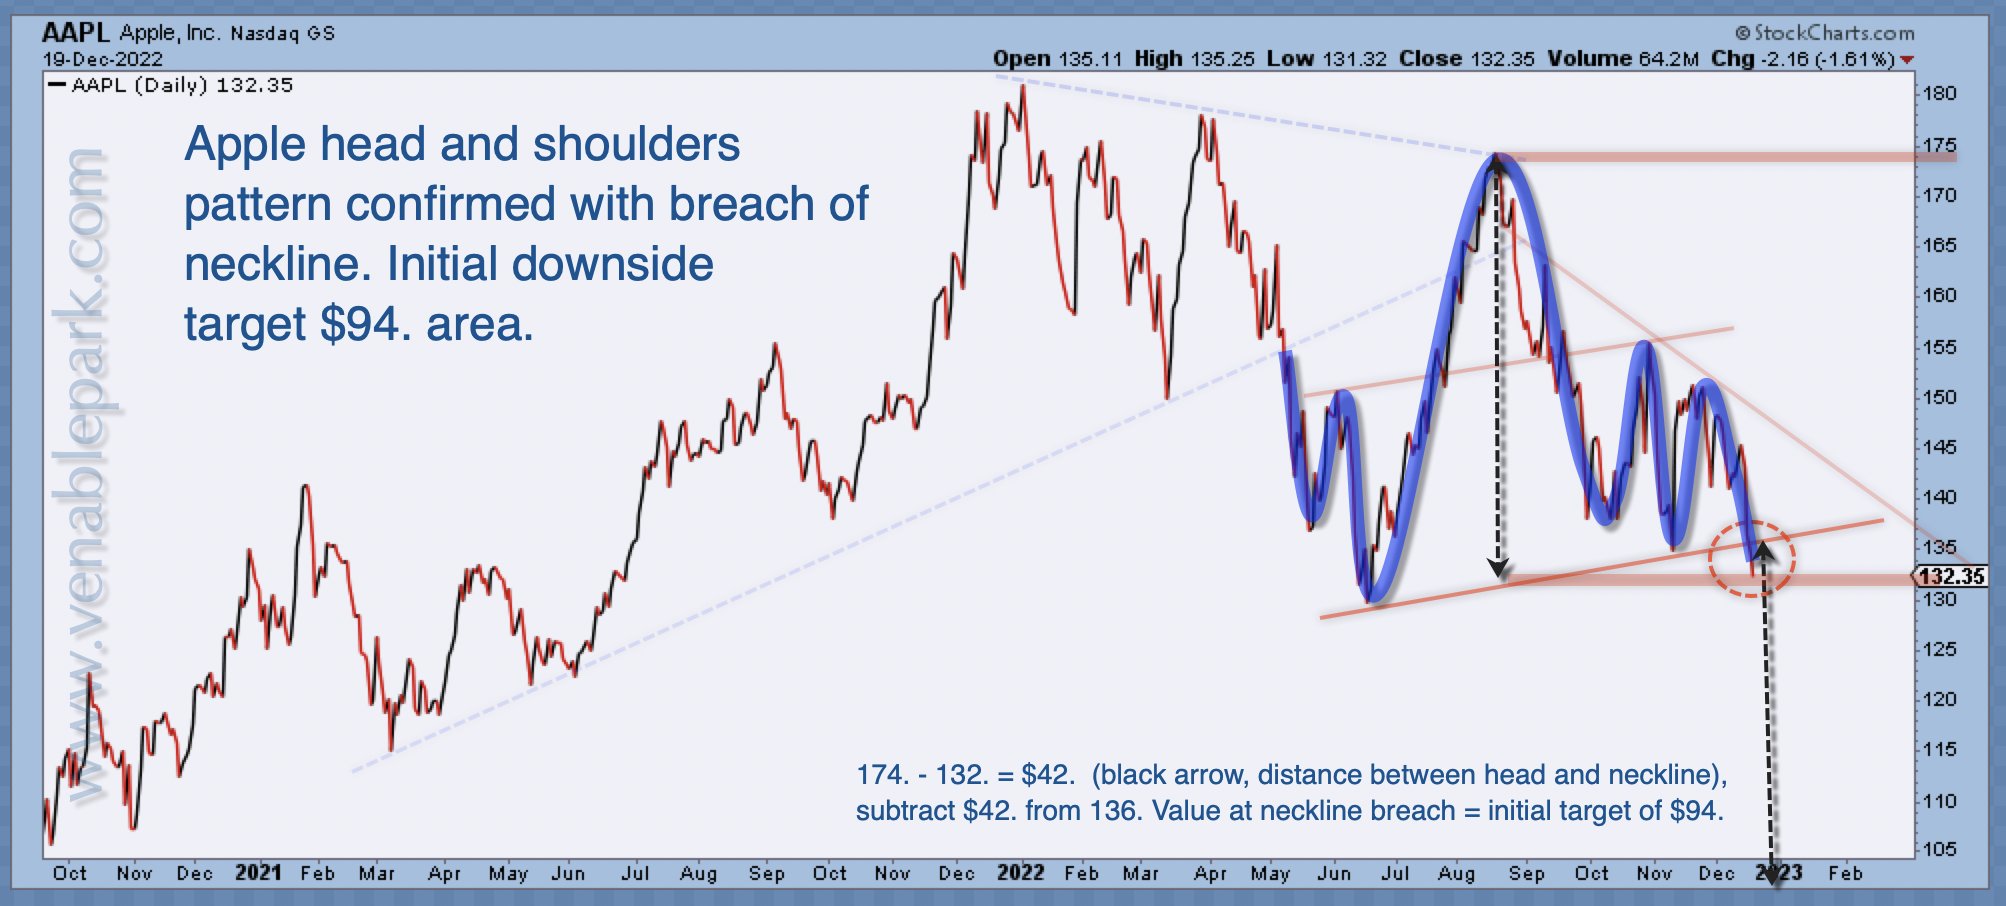
A micro reason that the overall market remains vulnerable is that its largest component Apple (6.23% weight), has fallen just 28% and remains widely held and over-hyped.

Yesterday’s close below $132 broke the support line that has held since last June and, as shown below courtesy of Cory Venable, suggests an initial downside target of $94; that would be 49% below Apple’s January peak. If Apple were to bottom at $94, it would be a relatively mild decline relative to past bear markets, where total cycle drops have been greater than 50%. Other S&P heavy-weights, Microsoft and Berkshire Hathaway, have seen similarly modest declines so far when compared with the 2000-02 and 2007-09 full cycle drops.


Posted in Main Page | Comments Off on Fun with stocks and curves

Canadian home prices need to fall

According to Statscan, 89% of Canadian individuals earn less than $100,000 annually. The median household income is $75,000 nationally (see more here) and just over $80,000 per year in the Greater Toronto (GTA) and Vancouver (GVA) areas.

According to CMHC (calculator here), a household with $100,000 in annual income ($8,333 a month before tax) and no other debt can qualify for a maximum conventional monthly mortgage payment of $2,800. At an interest rate of 5.5%, amortized over 25 years, with a 20% downpayment ($114,000), this means that above-median income households can afford a home priced at $580,000 (mortgage calculator here), nearly 6x their household income. Any other debt payments naturally lower the mortgage room available.

That’s a problem because Canada’s national median sale price was $632,800 in November (CREA). In the GTA and GVA, the median sale price in November was $1.2 and $1.1 million, respectively. So, $200,000 in before-tax annual income and a $244,000 minimum down payment are needed to qualify a household to buy a median $1.2m home with a mortgage balance of $976,000 (are we joking? Sadly, no).

Thus, notwithstanding the 12% decline in home prices nationally year over year and the 22% drop since February, housing remains unaffordable for the vast majority of Canadians. Unless incomes are about to more than double, prices will have to drop significantly more to make any sense. See: Home prices need to fall another 40% to make buying homes in these cities affordable.

Little acknowledged is that higher-than-average income allows people to qualify for more debt. This is also why home prices can rise more in higher-income areas than the national average. And so-called prime borrowers experience the largest increase in household payments when interest rates jump. Higher-income families are also more likely to have more than one property and more than one mortgage.

For all these reasons, selling pressure cascades and spreads from top-income earners on down, especially once unemployment rises during a recession. The segment below covers some of Canada’s latest data.

The Bank of Canada says that 13% of variable fixed mortgages have reached their trigger point. This is the point at which the interest rate resets. Different financial institutions are deciding to do different things about it. Could this start a foreclosure crisis in 2023? People who cannot afford to pay their mortgages are falling deeper and deeper into a hole of debt. The banks are kicking their hands as they reach for a hand up. Here is a direct video link.

Posted in Main Page | Comments Off on Canadian home prices need to fall