
Grantham: bear market update

As stocks rebound on disinflation data and hope for less central bank tightening, the tech-heavy Nasdaq is +21% from its June low but remains -18% from its November high. Meanwhile, commodity speculators are back to bidding up prices even as excess inventory of many goods mounts and global demand contracts. Bonne chance tout la monde.

While some proclaim a new bull market, realists note that 20% price rebounds have historically been common within ongoing bear markets. We are very early days in this one, and downside for markets, the economy, animal spirits and interest rates, still looms large.

In a late July video interview, cycle expert Jeremy Grantham offered context for what’s happening now as follows:

“There’s nothing as quick and spectacular as a bear market rally. With hindsight, they signify very little, but at the time, they frighten the pants off bears, and they give hope that all is over, all is forgotten, and it’s back to the races.” (Grantham suggested the current rebound in stocks could continue into September.)

“In terms of the entire bear market, it would be unusual for it to bottom out anywhere near this high. I would expect that by the low, the S&P would have declined by 50% from the peak in real terms.”

The Business Insider summarized ten standout quotes from the interview here. The full far-reaching discussion is available below.

Jeremy Grantham is the co-founder and Chief Investment Strategist of Grantham, Mayo and van Otterloo or more commonly known as GMO – a Boston-based asset-management firm. I last spoke with Jeremy almost exactly a year ago on episode 371 and I highly recommend you revisit it to see how prescient his predictions were at the time. In this episode, I wanted to get Jeremy’s thoughts on how the markets have materialized since we last spoke, but I also wanted to dive deeper into his knowledge around climate change. Here is a direct video link.

Posted in Main Page | Comments Off on Grantham: bear market update

Tracking grizzly bears

This morning (so far), stocks and bonds are rebounding on relief that US CPI in July eased to 8.5% (consensus forecast was 8.7%) from 9.1% in June, suggesting that the US Fed may hike less than 75 bps in September. The drop in price pressure was led primarily by disinflation in used vehicles, air travel, communication and apparel, while inflation continued in essentials for the masses like shelter, food and medical care.

Most importantly for the economic outlook and earnings, real incomes and productivity continue to slump to the lowest level in decades.

This morning marks Nasdaq’s 5th 2% gap-up day since the 2022 bear market began, and such rebounds are typical within ongoing bear markets.

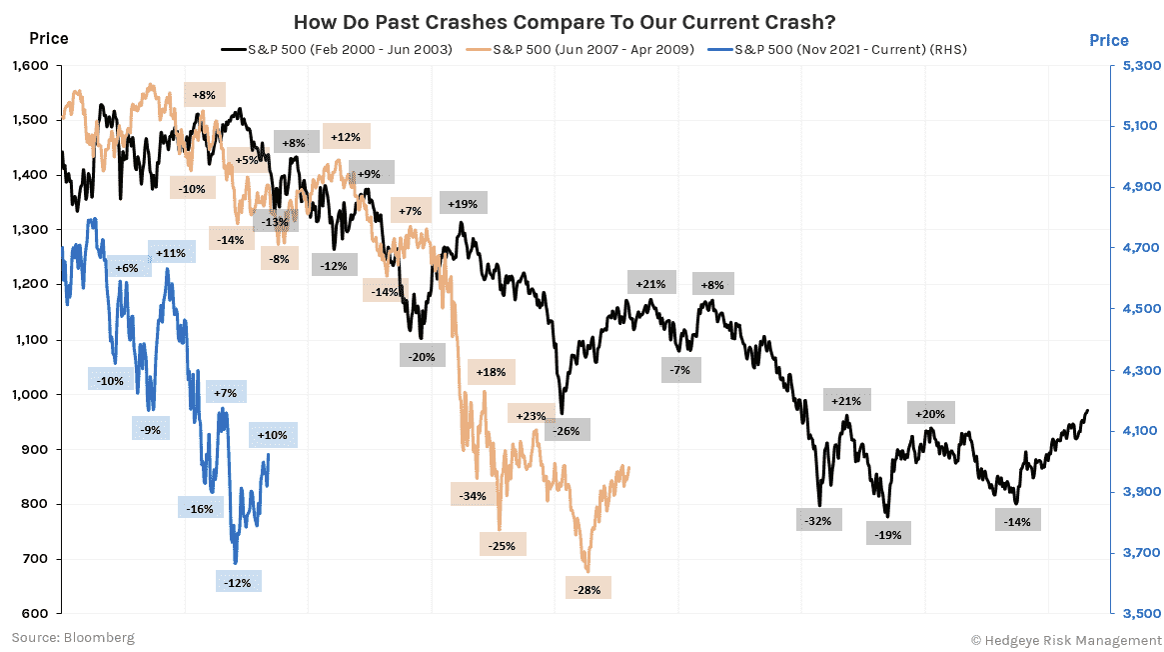
In the chart below, Hedgeye Macro analyst Ryan Ricci plots the S&P 500 recessionary bear markets of 2000 and 2008 compared with the current downturn. In terms of duration, the latest bear has lasted just 20% as long as 2000 and 37% as long as 2008.
Numbers on the chart show the interim bounces and drops within each bear cycle:

For 2000, the average up move was +15%, and the average down move was -18%.
For 2008, the average up move was +12%, and the average down move was -19%.
For the current bear, the average up move is +9%, and the average down move is -12%.

Ricci offers some useful context for the bullish chorus who never see downturns coming and continually urge us to buy stocks regardless of macrocycles:

“The largest bear market bounce in our current market is +11%, in 2008 +23%, and in 2000 +21%. Our current max bear market bounce (+11%) is lower than the average bounces in 2000 and 2008! Can you imagine all the talking heads in this country when there is a +23% bear market bounce?”

BOTTOM LINE: Patience should be a core asset allocation.”

Macro analyst Alfonso Peccatiello offers more historically informed insight in Bear Market Rally or Turning Point.

After a sharp decline in markets throughout 2022, many investors were caught off guard by the recent rally in equites. Is the bear market over? Should we expect a rally from here? “Hold your horses” says Alfonso.

Posted in Main Page | Comments Off on Tracking grizzly bears

Contagion between public and private markets

The average sale price for a Toronto home in July was $1.02 million (Toronto Regional Real Estate Board), down $133,075 (11.5%) from June 2022 and +0.2 percent or $2,520 compared to July 2021. Sales were down 44%, and active listings were up 25%, while the stockpile of available homes was up 58% from a year ago.

Over the last six months, Toronto’s average sale price has dropped more than $500,000.

So much for all the hopium about “rich Torontonians” being rate insensitive; high-priced houses are seeing some of the deepest declines:

It would appear that eroded affordability is hitting Toronto-based homebuyers the hardest; detached prices in the city proper are down 7.3%, though still sit at a hefty $1,515,762, with sales down 46.9%. Compared to February, when the average exceeded the $2M mark, Toronto house prices have slid a whopping $558,226 (-26%). A large chunk — a difference of  $221,250 — has been lost in the last month alone.

Declines are still steep, though slightly less pronounced, in the 905 markets. TRREB reports prices have dropped 1.9%, to $1,320,269, down by $407,694 from February (-23.5%). Month over month, they’re down 3%. Sales in the suburban and exurban markets are down 46.9%, says TRREB.

This predictable but widely unexpected downturn (after prices doubled in record time) is sparking a classic cash crunch among highly leveraged owners and their lenders; see Goodbye housing bubble, you won’t be missed:

House flippers thought they’d actually earned something, when they often just shuffled money around and waited. Now they don’t want to admit the fun is over, and figure if they just sit tight long enough, the market will turn foolish again and they can still get their big cash-out.

Related trouble in the illiquid private equity world is just beginning as funds will be forced to mark assets to market and sell some properties to meet redemption requests; see investors sell stakes in buyout funds at a record pace.

And then there are all of the institutions, pensions, family offices and other investors who piled into ‘alternative’ funds concentrated in real estate and related lending as well as high-risk venture bets during the ‘easy’ money era. As debt and equity prices tumble, required rebalancing and redemptions naturally force selling in the ‘alternatives’ where illiquidity tends to magnify price discounts. For a taste, see: Market Rout Sends State and City Pension Funds to Worst Year Since 2009. Meanwhile, the private equity and real estate losses since March 31st have not yet been reflected in portfolio values.

Posted in Main Page | Comments Off on Contagion between public and private markets





