The unending Canadian housing boom?

The average rate on a common fixed-rate mortgage in Canada was a record-low 1.97 percent at the end of 2020.  This, along with taxpayer-backing that enables minimal down payments, has helped propel Candian home prices and household debt to world-leading highs.  This chart shows the top 8 year-over-year price gain areas to February 2021.

In the near-term, on paper, present property owners like myself have won a lottery.  But if we don’t cash in the ticket by selling high, moving somewhere cheaper and banking the savings, there is no net benefit to exorbitant prices.  Quite the opposite: many are locked out of property ownership and those who do buy are left paying off related debt for decades, with reduced savings and spending capacity throughout.

Demand has spiked new housing starts in Canada to a high not seen since previous cycle tops in 1990 and 2008, as shown below since 1977.  Once more, the Canadian economy has become extremely vulnerable to any downturn in the housing sector.  And yet, the cure to too high prices has always been too high prices.  Painful as they are for the unprepared, downturns are naturally recurring resets endemic to credit and price cycles.

The present expansion cycle has been long and strong enough to convince many that this time is different and prices will never correct again.  That would be unprecedented.

When Covid-19 hit, even Canada’s own national housing agency seemed sure this was finally the end, predicting a dive in home values ranging from bad to catastrophic. But instead the market went on to another record year.  Here is a direct video link.

You can read Ari’s piece The Housing Boom that never ends here.

Posted in Main Page | Comments Off on The unending Canadian housing boom?

No market for sober thinkers

Market pricing is driven by irrational impulses when math and risk-assessment have no place in the allocation decisions being made.  The present financial climate is a textbook episode where sober thinking is decried as out of step and worse.

With the masses wielding record amounts of government-backed-debt while eschewing traditional risk-checks like home inspections and historically-prudent price-to-income ratios, mania is rampant.

For some COVID-friendly-entertainment yesterday morning, we played ‘guess the price’ driving in a radius around where we live north of Toronto.

For a base-line glimpse:  in Barrie, thirty-year-old entry-level townhomes are on offer for $629k.  The property shown on the left last sold in August 2016 for 260K–some 140% below the current ask.  Maybe they’re pushing their luck with this price.  A neighbouring property sold yesterday for 585K, up 113% from its last sale at $274k in May 2016.

Not to pick on townhomes.  Detached subdivision houses in the 700k to 1m range are run-of-the-mill.   Twenty minutes into the countryside in any direction, sales in the 1 to 2m range are typical, often within days of listing.

According to the CREA, the national average home price in February was a record $678,091, up 25 percent from a year earlier.  CREA forecasts the average price to rise a further 16.5 percent to just over $665,000 in 2021 and $679,341 in 2022–no pull-backs in sight.

In the meantime, the average annual salary for full-time employees has risen 4% since January 2019 to just over $54,630 in 2020.

The average detached home sale in the 905 area code immediately surrounding Toronto jumped 28% year over year in February to $1.3-million.

In these conditions, a $450,000 down payment and household income of 200% of the national median are no assurance of winning the abode lottery.  See:  A well-qualified millennial home-seeker throws up his hands after losing multiple bidding wars.

Fear of missing out (FOMO) during upcycles tends to overwhelm any fear of capital losses (FOCL).  But amid conventional nonsense, math is always worth reviewing.

On a property priced at 1.3m, even someone wielding a historically huge 450K downpayment needs to sign on for an 850K mortgage that will typically take several decades to repay even if presuming perpetually low-interest rates.  Moreover, if home prices can rise 28% in a year, they can certainly fall that much as well.  A 28% decline from 1.3m would return that home price to 936K and evaporate all but 86K of the initial 450k cash downpayment.  It commonly took 10 to 15 years for prices to revisit prior peaks after past realty correction cycles.  That’s a long time waiting to grow back principle, even for those who can manage to wait.

Waiting to buy assets at rational prices while building cash savings is always a wise course.  Today, more than usual, the fortitude to do so is likely to define individual financial prospects for many years to come.


Posted in Main Page | Comments Off on No market for sober thinkers

Risk-seeking drives yields higher only until risky markets croak

With the US 10-year treasury yield pushing through 1.62 today, bond prices are in retreat and the yield back to where it was in early February 2020.  It’s as if the pandemic never began.  That is, except for all death and suffering, lost businesses, unemployment and massive debt addition that continues to unfold.

How much further yields rise matters for all markets.  Higher treasury yields mean higher fixed mortgage rates, lower borrowing capacity and increasing pressure on equities and realty prices.

As shown in my partner Cory Venable’s chart below from February 22, the last three bear cycles for stocks (shown since 1990) began when the 10-year yield had risen far enough above 2-year yields that the spread between the two passed .8% (dotted blue line), and did not end until this spread had topped 2.4%.

Having broken above .8 in late 2020, the 10-2 spread breached a new cycle high of 1.477% today.  If history is a guide here, we could see a further spread increase in the months ahead, with the 10-year potentially topping out somewhere near the 3% range.  In the 2007-09 cycle, the US 10-year topped at 3.36% in April 2009 and the 2-year just over 1% while the stock market halved.  With debt at historic highs at every level today, leveraged participants, assets and sectors are even less tolerant to higher rates now than in the past.
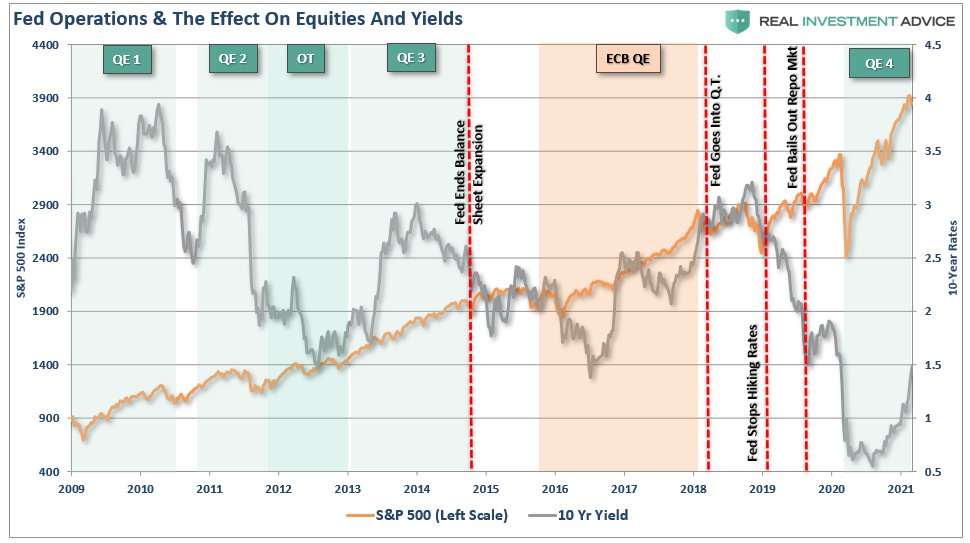
Some point to central bank bond-buying as a reason why rates will not rise further.  But this flies in the face of experience during past ‘quantitative easing or QE’ interventions.

As shown below, courtesy of Lance Roberts, each time central banks have swapped their cash for bonds on bank balance sheets (QE) since 2009, increased liquidity in the financial system has moved, not into the real economy, but rather out of safe deposits and into higher-risk securities on increased risk-seeking from market participants. In the process, net selling of treasuries pushed yields higher for a time until higher yields snuffed out the risk rally once more.


The upside here is that higher yields will offer another valuable opportunity to put cash to work in the highest quality bonds in the coming weeks. This will be a place to collect income and some capital gains as other assets tank.  And then, finally, we will have a valuable cyclical opportunity to move cash into high-yielding, low-priced equities once more.  Well worth the wait.

Posted in Main Page | Comments Off on Risk-seeking drives yields higher only until risky markets croak