Housing bubble popping again?

Home prices are precarious to a deflating debt cycle in the US, Canada, Austrailia, New Zealand, the UK, Hong Kong, Sweden, and…well pretty much everywhere that humans have used excessive debt to drive up realty prices far beyond income growth over the past decade.  See:  The U.S Housing Boom is Coming to an End, Starting in Dallas for some good stats and charts.

We have to live somewhere.  Homes that one can carry for the same or less than the price of rent can be great foundational assets to have.  But the goal should always be to get it paid for as soon as possible and to keep other carrying costs well below our means.

A paid for home or office with income generating units within it that help cover the owner’s carrying costs, even create net cash flow–even better.  But using debt to acquire real estate that makes us cash poor or cash-flow negative is generally a bad financial decision that usually ends in trauma.  To prosper from bursting asset bubbles, we need to have low or no leverage personally, with liquid cash and our buy list, and then patiently wait for prices to go on clearance sale.  They always do in the end.

As we’ve been tracking here at PeakProsperity.com, the housing market is starting to look quite ill. After the central bank-driven Grand Reflation following the Great Financial Crisis, home prices are now beginning to nose over from their new bubble-highs. Has the Housing Bust 2.0 begun? If so, how bad could things get? And what steps should those looking to pick up values at much lower prices in the future be taking?

This week we talk with citizen journalist Ben Jones, property manager and publisher of TheHousingBubbleBlog — where he tracks the latest headlines and developments in the housing market. And given the stream of data Ben sees every day, he’s extremely pessimistic on home prices in most major markets worldwide. Here is a direct video link.

Posted in Main Page | Comments Off on Housing bubble popping again?

More on why product sales must be separated from financial advising

Financial sales firms will never ‘get’ the sacrosanct importance of holding professional advisors to a fiduciary standard because masquerading sales as advising is such a lucrative business model for them.

The crash of 1929, the decade of loss and suffering thereafter and the revelations of the Pecora Senate hearings of 1932-34, made this vividly clear to our grandparents and led to the landmark Glass-Steagall Act of 1933 and its hard divisions between banking, product underwriting and advising services, as well as the Securities Act of 1933 setting penalties for filing false information about stock offerings, and the Securities Exchange Act of 1934, to regulate stock exchanges.  This was all watered down to nothing over the past 20 years, and the consequences are our present reality of record debt, destabilizing financial risks and gaping capital shortfalls in most of the world’s pension, trust funds, families and institutions.

A recent article underlines the classic conflicts of interest so endemic today in Some Merrill Brokers say plan urges more consumer debt:

Some brokers at Merrill Lynch are pushing back against a compensation plan they claim rewards them for increasing debt their clients take on and in some cases can punish them for reducing it.

…The skirmish is occurring as brokers digest pay policies that include what amounts to a broad pay reduction as well as changed targets for attracting new business and cross-selling certain products. Those who miss growth targets earn less than in the past; those who jump certain hurdles stand to get a bonus.

One of those targets focuses on growing clients’ net new assets and liabilities, including things like securities-backed loans and mortgages, by at least 2.5% annually…

Loans that are backed by a client’s investment portfolio are a particular favorite of brokerage firms, said Jeffrey Harte, brokerage analyst at Sandler O’Neill + Partners. “It’s taking money that’s already there and making more money on it, versus the much harder job of going out and growing assets,” he added.”

Merrill Lynch Wealth Management ‘Manglement’ head Andy Sieg is so corrupted that when asked about the scheme, he didn’t even know to be embarrassed about it, acknowledging some complaints from brokers he added the “pay program has motivated many financial advisers and helped boost growth at Merrill.”

Well, if it’s helping boost growth for the brokers and your bonus Andy, by all means, abuse away, right?

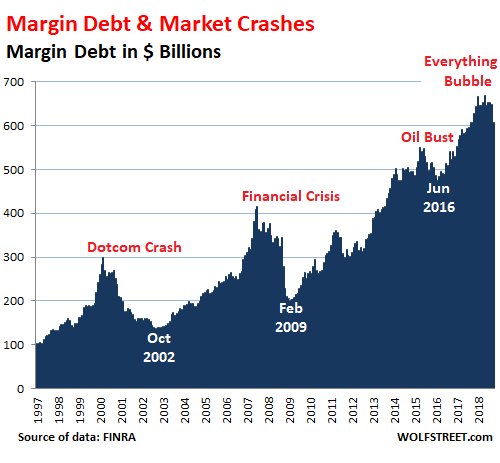
The add more debt and stir model has been legendary this cycle. Below is the latest margin debt chart showing funds borrowed against security portfolios from 1997 through the end of October.  Much forced selling is coming to markets everywhere as these levered accounts unwind amid falling prices.  And that won’t just hurt levered participants, but un-levered ones who think they are being ‘conservative’ as well.


Posted in Main Page | Comments Off on More on why product sales must be separated from financial advising

GM and the planet paying for status quo myopia

After pig-headedly ripping its EV-1 electric cars off adoring customers in 2003 and crushing them up (believe it or not), 15 years later GM is finally renewing its attention on electric car production. Thanks to Elon Musk for leading the world’s major car producers kicking and screaming into a much-needed emission-free future.  But the world remains far behind where we could and should have been in this evolution.

While climate change seems too generalized a phenomenon for most individuals to wrap their heads around, toxic air and the myriad of related health problems is becoming immediate enough to demand attention.

Plagued by horrific air quality in many cities, China finally has a sense of urgency on this transition. Its government has mandated that starting in January, all major manufacturers there must meet new-energy vehicle production minimums and this is helping to accelerate the country’s EV producers.  Meanwhile, with western demand turning down on highly indebted households and super-extended auto loan terms, GM and other car makers are now drowning in antiquated ICE (internal combustion engine) inventories and racing to recalibrate by closing plants and laying off workers.

A huge head start was wasted through complacency and status quo myopia, and the unnecessary costs of this to our environment, health and productivity will compound for years to come.  Hopefully some lessons can be learned here.

See China is leading the world to an electric car future.  Here is a direct video link

Posted in Main Page | Comments Off on GM and the planet paying for status quo myopia