Dumb and dumber: incentives reward burning and burying unsold clothes rather than reusing

The fashion industry is often cited as the most polluting global industry behind those of oil and gas and industrial animal agriculture. Apparently, counter-productive tax incentives are presently rewarding importers for burning and landfilling unsold clothes rather than recycling or donating them. So, we taxpayers are subsidizing self-destructive environmental pollution and wasted resources and it is high time to stop the madness. In the meantime, consumer intolerance is a critical catalyst for change.

British luxury fashion brand Burberry is going to stop burning unsold clothes, bags and perfume, and will instead focus on recycling and donating their leftover product. Here is a direct video link.

Posted in Main Page | Comments Off on Dumb and dumber: incentives reward burning and burying unsold clothes rather than reusing

At asset market highs, liquid savings remain woefully insufficient

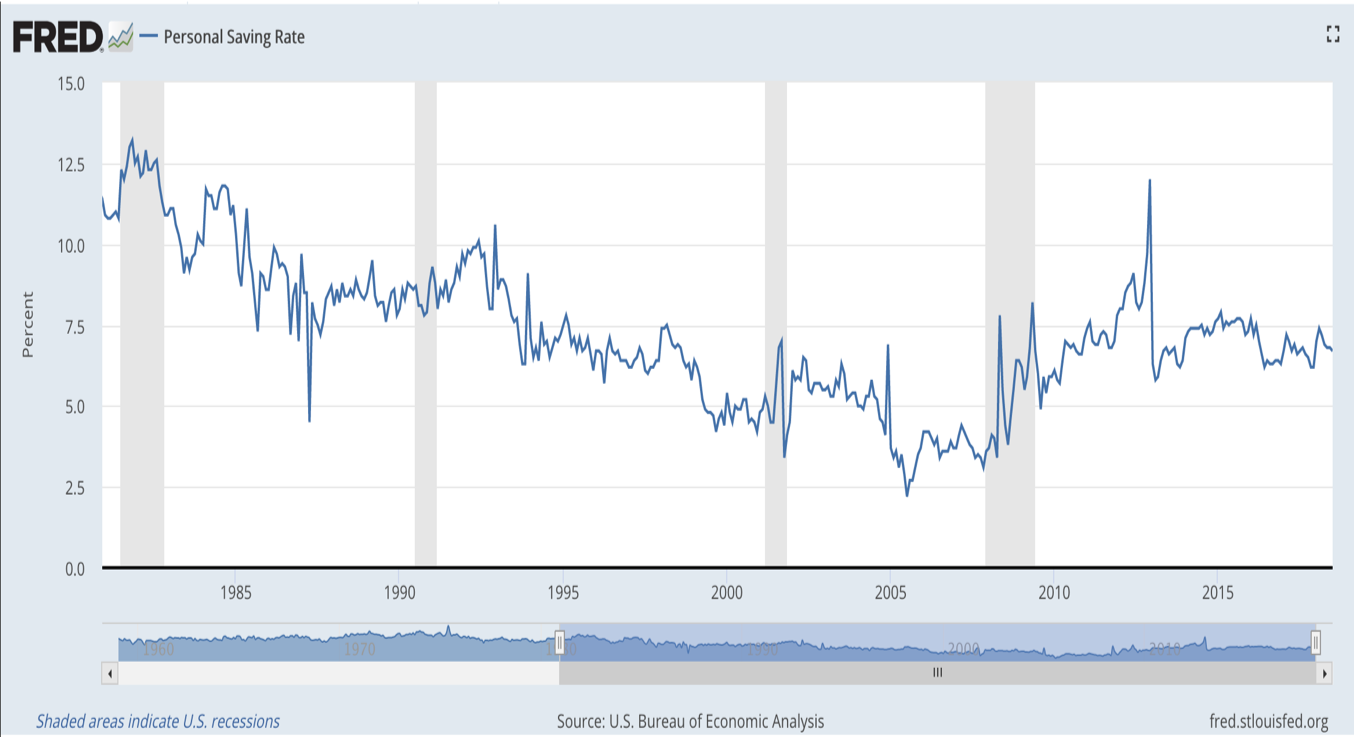
As shown below, the average US saving rate fell from 13% of disposable income in 1981 to 2% by 2005, as US housing prices peaked (and people naively bet everything they could borrow on home prices perpetually leaping faster than the rate of inflation). As the US realty bubble burst and prices fell in 2006 (followed by the stock and corporate debt bubble implosion in 2007-09), the household saving rate moved higher, before stalling around 6% since 2013 even with cyclcial highs in employment and income.
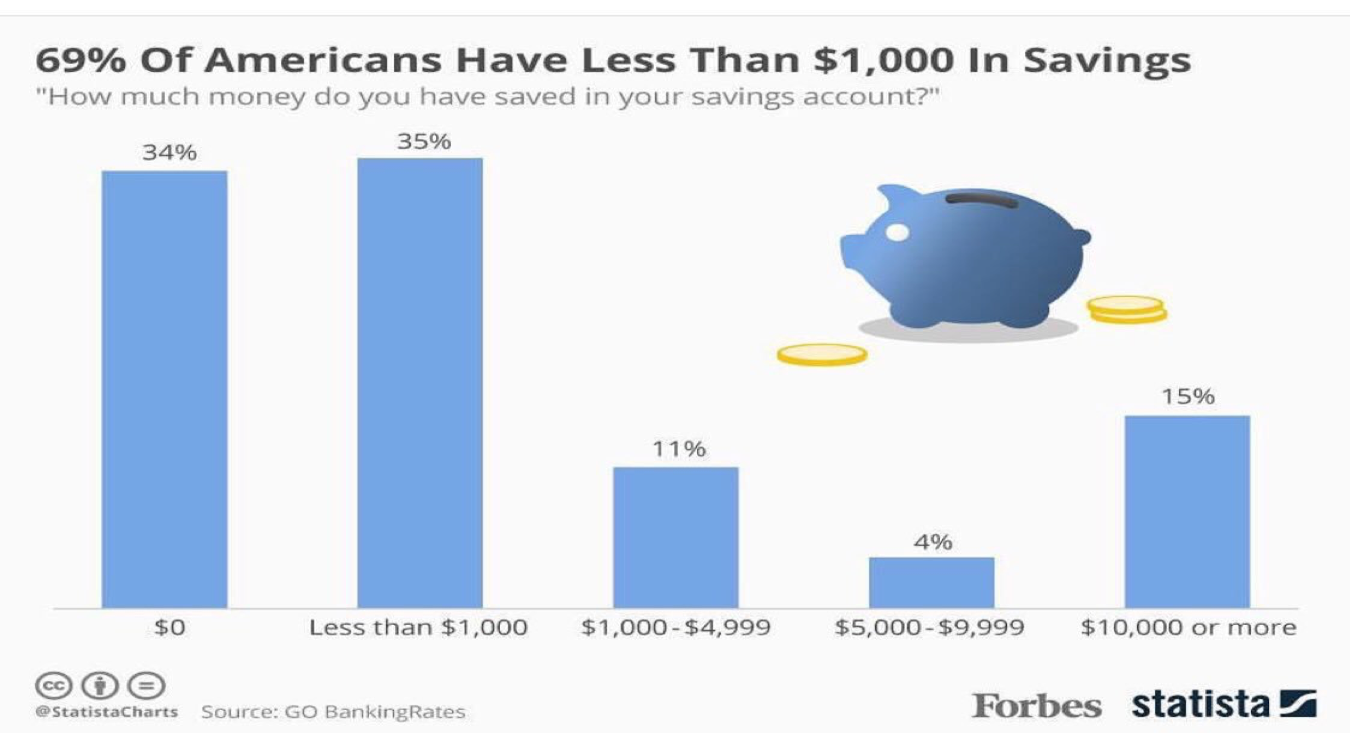
Today, 69% of American adults report less than 1k in liquid savings as shown here.
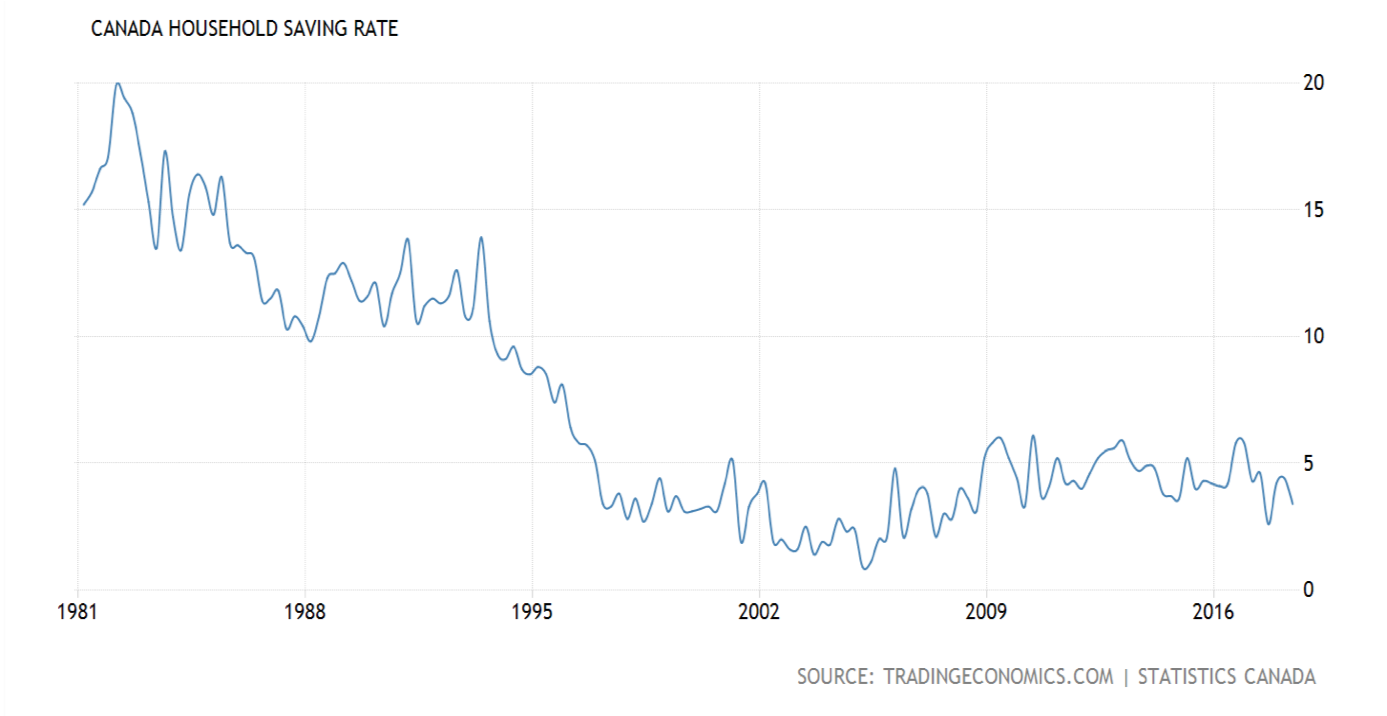
And Canadian stats are not better. As shown below, Canadian savings rates also fell from near 20% of disposable income in 1981 to about 2% by 2005, and remain less than 5% today as Canadians have also naively bet every dime they could muster on perpetually leaping property prices.
Unaffordable housing along with record household debt and muted wage growth over the last decade, have left little disposable income to accumulate as retirement savings or education savings for our children. Hence why young people have become increasingly indebted before they even enter the workforce, making it harder for them to start businesses, buy assets (from downsizing boomers) and start families (future consumption units) of their own.

The gamble-our-way-to-prosperity mentality is self-defeating and the deficits continue to mount.  The solution is to focus on lowering debt, risk exposure, and expenses so that we can increase net savings, productive investment and financial stability.  A drop in present personal consumption and speculation is necessary in order to enable future spending ability.

Some insightful stats are highlighted in the below segment:

As of January 2017, the average retiree receives $1,360 a month from Social Security. That’s $16,320 a year. About one-third of adults over 65 also collects a pension, but it’s not a large amount of money. The median private pension was only $9,376 a year, according to the Pension Rights Center (state, local and federal pensions were higher).

And those are the lucky ones. Anyone looking to collect more is going to need to rely on their personal savings. That gets me back to the 401(k) and IRAs. That 65-year-old with a median $64,811 in his 401(k) would pull out a little more than $3,000 a year assuming he or she will live at least 20 years more.

Even with stocks at new highs, there’s still a lot to be done on retirement savings, says Pisani from CNBC.


Posted in Main Page | Comments Off on At asset market highs, liquid savings remain woefully insufficient

Sellers in denial as 28% of GTA listed homes now sit vacant

As sales continue to slow in Canada’s property markets, the hottest spots in the greater Toronto (GTA) and Vancouver areas are, so far, still considered ‘sellers’ markets’ even as some 28% of the GTA’s listed properties are now sitting vacant– a 17% year-over-year increase in vacant homes for sale.

Reasons for the mounting unsold inventory include higher interest rates and the foreign buyers’ tax, but also households that are tapped out on debt-to-income ratios, and asking prices that are too high.

In general, sellers are evidently not yet willing to admit that the world-infamous Canadian realty bubble is finally deflating.  Notional gains are now eroding, and for those who overpaid in the boom and need to sell, the capital losses will be hard to take. See More than a quarter of the homes for sale in Toronto are empty:

 “there are a fair number of stubborn sellers holding out for an unrealistic price for their home, though they’ve already moved on to another home or downsized.

…many sellers are still expecting to see the kind of price increase and frantic action we saw back in 2017. The reasons for holding out could be an unrealistic or unreasonable expectation or it could be because these sellers are too financially tied to the property. If many home flippers accepted today’s market prices, they would experience a significant financial loss after considering any rehab and construction costs incurred after purchasing properties in 2017 prices.

Posted in Main Page | Comments Off on Sellers in denial as 28% of GTA listed homes now sit vacant