Risk-blind and the great bear market coming

Our son was born in December 1999, three months before the ‘irrationally exuberant’ stock market peak of March 2000.  When he was young, we used to tell him that he was born at the top of the greatest stock market bubble of all time.  Apparently we were mistaken.

Celebrating his 18th birthday last month, we had to change the story:  now he was turning 18 at the peak of the greatest financial bubble of all time.  His short life has now had the distinction of spanning the most destructive and reckless financial era ever.

Lest anyone try to delude themselves that the present run is just excesses in the tech sector, my partner Cory Venable’s chart of the relative strength indicator for the Dow 30 so-called ‘conservative’, dividend paying stock index below, says it all.  With a monthly RSI reading of 93.3 (! on a monthly!) stocks have never been more overbought, and have never lasted so long in the delirious zone.


After both of the last crashes, most kicked themselves for not seeing the warning signs; for ignoring rational metrics, buying and holding with the herd, as they fell into the abyss.

Today if one can’t see the warnings there is no hope that they ever will.  In the infamous words of Queen Elizabeth in November 2008, after falling markets had wiped an estimated £25 million off her personal fortune and triggered The Great Recession worldwide:

“If the problems were so large, why did nobody see it coming.”

The answer, as always:  greed, ignorance and lack of personal discipline.  We’ve been warned.
Posted in Main Page | Comments Off on Risk-blind and the great bear market coming

How much life savings should we bet on a ‘GOAT’?

Today on CNBC, Mike Santoli reviews the stats on the 2009 to 2018 stock market expansion and points out that, already the second largest and longest price expansion in history, Bulls are now betting this market will be the G.O.A.T (Greatest of all time) and manage to match the all time largest speculative price to earnings peak reached at the tech-bubble top of 2000.

Meanwhile in terms of price-to-sales, Leuthold Group notes that the S&P 500’s price-to-sales ratio today is already above where it was at the year-2000 market peak.

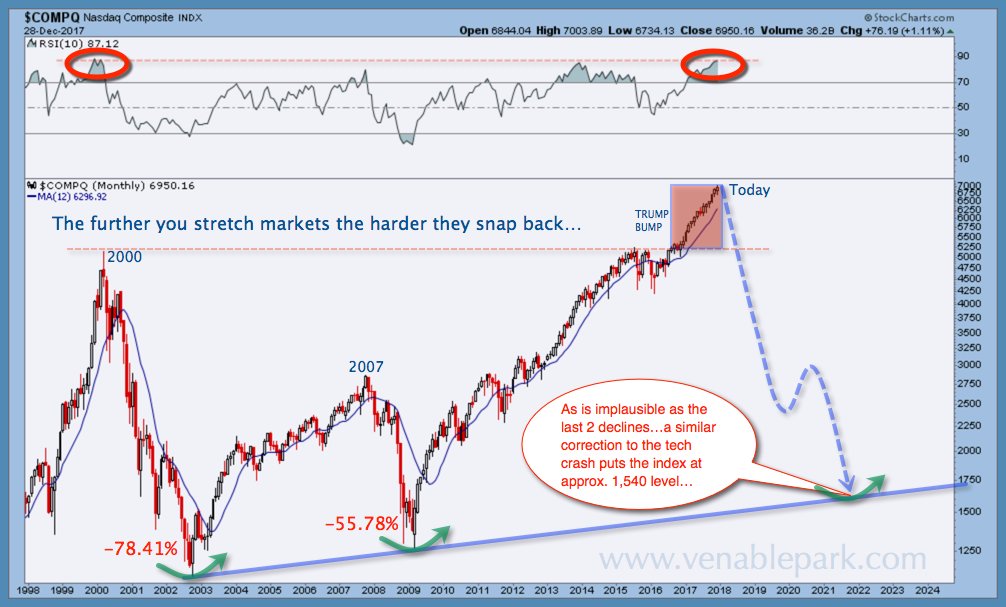
Everyone with a financial memory should know what happened next.  The below chart of the NASDAQ 100 Index since 1998, by my partner Cory Venable, is a reminder.  Not only did the NASDAQ collapse 78% into 2002 and the broader markets 50%, but it then took 16 lost years and trillions in central banks QE injections for the index to make back losses.  By then, most of the people who were holding in 2000 had long since liquidated in losses.  The rebound and Trump-bump extension since 2016, has now set stocks up for a similarly severe mean reversion period in the next contraction period (suggested by blue dotted line back to cyclical support).  On a monthly, relative strength indicator (RSI), the NASDAQ is as overbought today as it was in March 2000 (see red circles).  Truly, it’s hard to be hyperbolic here.

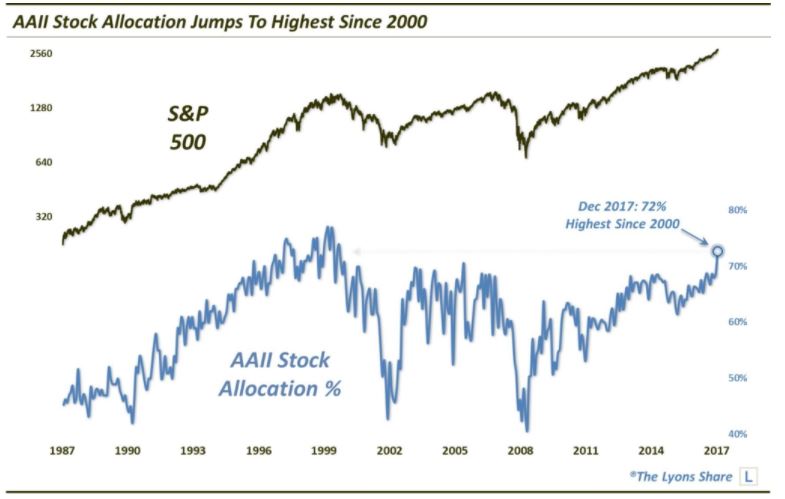
Yes, so long as more indiscriminate cash continues to flood into these markets than is trying to cash out, prices could levitate a while longer.  But at some point cash and margin room do run out.  Today margin debt is already far past the 2000 high (see the chart here) and monthly asset-allocation reports show that institutional and individual investor portfolios are already holding record lows in cash and 72% in stocks (the all-time peak in 2000 was 77%) as shown below.  Everyone that is willing to bet on miracles, or who is paid to gather assets or sell financial products–rather than manage risk–is already all-in.


If confidence and ‘fear of missing’ out prevents today’s holders from cashing out stock market bets at all-time cycle highs, the truth is that most never will –until they are forced by crashing prices, terror, margin calls, ETF sales and mutual fund redemptions as the masses liquidate and flee once more ahead.

So if you, your broker or manager are holding your savings in risk-assets today, you should understand the extreme odds against this bet, and ask yourself this question:  what percentage of your life savings can you afford to lose 50-80% of and then wait years trying to recover?

That answer will help you decide how much to bet on a ‘GOAT’ today.


Posted in Main Page | Comments Off on How much life savings should we bet on a ‘GOAT’?

Opportunity coming for those who are ready

While still up .7% over the last year, Toronto home prices fell for the 7th consecutive month in December, down 8.9% since May–the largest seven-month decline in data tracked since 2000. Falling 3.5% since November, the average sale price in Toronto is still–a wildly un-afforable for most–$735,021 ($1.2 million for single detached homes.)  See Toronto home prices fall for seventh month as lending tightens. Here is the chart.


Still with Canadian households at record indebtedness, and new lending restrictions just biting this month, the long overdue slowdown in the real estate sector is barely just started in Canada.  The economy which has been precariously dependent on this one sector since at least 2014, wobbles in the balance. See:  Global Housing Markets are ‘slowing sharply’. Is Canada next?

As the Bank of Canada frets over consumer debt levels and fantasizes about room for higher rates, this month’s new “stress test” for traditional mortgages is expected to reduce homebuyers’ purchasing power by about 21% (ie., 21% lower prices needed) and disqualify 1 in 10 would-be-borrowers in 2018 and beyond.

Now more levered than Americans before their housing bubble bust in 2006, Canadians are wholly unprepared for a secular downturn in real estate–something not seen in Canada since 1989.

After the average house price in the greater Toronto area (GTA) increased 113% in real terms between 1985 and 1989, the bubble burst.  See Toronto housing bubble in 1989:

Coupled with the early 90s recession, a spike in unemployment and a drop in the inflow of immigrants to the area, housing prices in the GTA collapsed. Between 1989 and 1996 average price of a house in GTA have declined by 40% adjusted for inflation…Downtown of Toronto was hit the worst with over 50% decline in value of a home.

Most often missed in these discussions, is that once debt and speculation-fueled financial bubbles burst, it typically takes more than a decade (or two!) for prices to recover their prior peak. By then those who held high, with leverage and low cash liquidity, have long since liquidated low with losses:

Unaccounted for inflation, it took 13 years for the average house price to recover in the GTA. In nominal terms, the average price breached the 1989 peak of $273,698 in 2002.

Only those who are prepared and waiting with low-leverage, patience and cash savings are able to take advantage of the most lucrative and low-risk investment opportunities in each secular cycle; while the unprepared–oblivious and/or reckless–as well as those needing to downsize holdings to raise cash for retirement, all suffer in the aftermath.

This price expansion cycle has been extra-long thanks to financially suicidal, central bank-enabled, credit expansion following the 2008 financial bust.  This suggests that the price contraction cycle–investment opportunity–that follows next, while also be equal and opposite in the other direction.  Who is ready?

Posted in Main Page | Comments Off on Opportunity coming for those who are ready