Canadian borrowers losing ability

Home sales in Canada’s largest city–Toronto–fell 37% year over year in June. Long overdue buyer exhaustion has finally been triggered after the Feds tightened mortgage insurance requirements last November and Ontario imposed a 15% tax on foreign purchasers in April.  Now regulators are considering new rules requiring lenders to stress test uninsured mortgages (prompted by oversized loss risk in the sector).

In addition, on Wednesday, the Bank of Canada is expected to raise its benchmark overnight rate to .75% from .50%. In anticipation, Canada’s biggest banks are also tightening. Royal Bank of Canada raised its fixed rates for 2-,3-, and 5-year term mortgages by .20%. See:  Canadian home buyers losing steam, and cash.

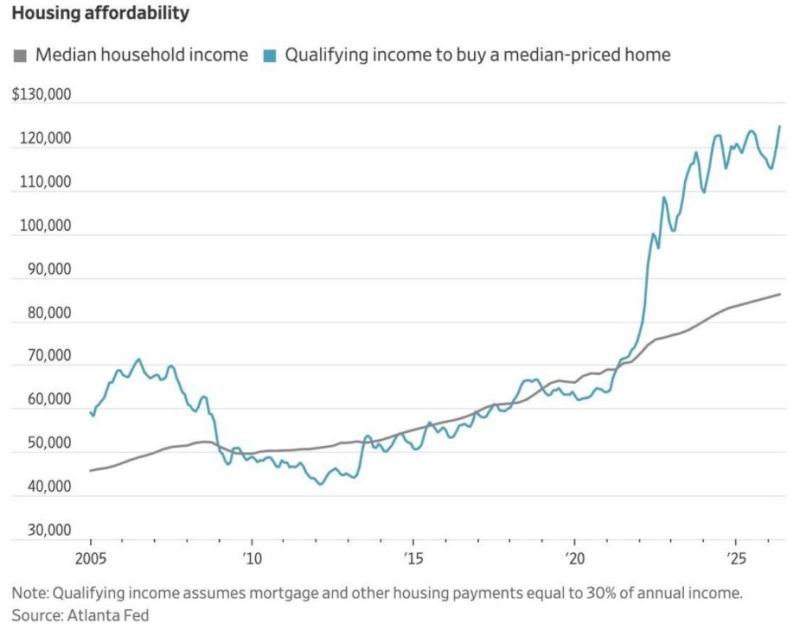
With some 90%+ of Canada’s economic growth coming from realty transactions and services the past 2 years, we doubt the BOC and banks will raise rates far before declining property prices and a weakening economy cause them to pause once more.  But at this point, holding rates lower for longer is not going to repair or even meaningfully patch the financial leak.  This is Canada’s payback period due after a decade of reckless credit abuse.

Next up will be a necessary cleansing cycle resulting in lower shelter prices to help restore affordability once more and reset many over-leveraged participants–households and businesses–through bankruptcy, credit restructuring and write downs for lenders.  It will also mean lower tax revenues for governments that have become unduly dependent on what has been the one firing economic cylinder since oil prices collapsed last in 2015.  This is the downside of too little diversification and unproductive spending.

Here is a direct video link.
Posted in Main Page | Comments Off on Canadian borrowers losing ability

Many Canadians in over heads even without rate increases

A new poll conducted on behalf of accountants MNP offers more sobering insight on the financial fragility of Canadian households. See: 27% of Canadians already ‘in over their head’ with mortgage payments: MNP.  Here are some highlights:

  1. 30% say any drop in the value of their home will cause them financial difficulties.
  2. Even with no price drop or increase in interest rates, 27% say they are already ‘in over their head’ in terms of funding their current mortgage payments and expenses.
  3. Over 70% rate their ability to cope with a 1% interest rate increase as less than optimal and 77% say they would have difficulty managing an increase of just $130 in their monthly payments.
  4. Those who have borrowed on home equity lines of credit are particularly vulnerable:

“Many are borrowing against their homes and using them to finance lifestyles they simply can’t afford. What’s worse is that many are not making regular payments against the principal, and the threat of an increase in interest rates might make it even harder to make ends meet,” Bazian said in the release. “We’ve been living with this ‘minimum payment mentality’ for far too long. Collectively we need to start looking critically at our debt loads and factoring in interest rate changes to see if the debt amassed is even affordable…For many, it already isn’t.”

A June report from the Financial Consumer Agency of Canada confirmed that Canadians owed $211 billion on 3 million home equity lines of credit (HELOCs) at the end of 2016, with 40% not making regular payments on the loans and 25% making only minimum or  interest only payments.  See:  Line of credit use soars

Posted in Main Page | Comments Off on Many Canadians in over heads even without rate increases

Canadians using homes as ATMs

We have encountered several people in the past year who have been gutting the equity in their homes via mortgages and ‘Home Equity Lines of Credit’ to speculate on other properties and security portfolios. Often they are doing so on the ‘advice’ of their bankers, mortgage brokers, realtors and stockbrokers, financial planners’and even accountants. Others have taken How to get rich seminars with HGTV celebrities like Scott McGillivray (similar to the Trump ‘University’ courses that people were paying thousands to take a few years back).  Sales puff designed to profit off the gullible.

All of this great for enriching those collecting fees and commissions on the transactions, and most likely to be financially devastating for those doing the buying and so called investing.  It has also set up for the next liquidation sale coming, where present holders become stressed sellers and those with cash can pick up assets for pennies on the dollar.  This has been an extra long up cycle, so we should expect the correction phase to be equal and opposite in the other direction.  Lots of good insights in this clip.

Scott Terrio, estate administrator at Cooper and Company, joins House Money to discuss the dangers people can get themselves into when usnig HELOCs.Here is a direct video link.

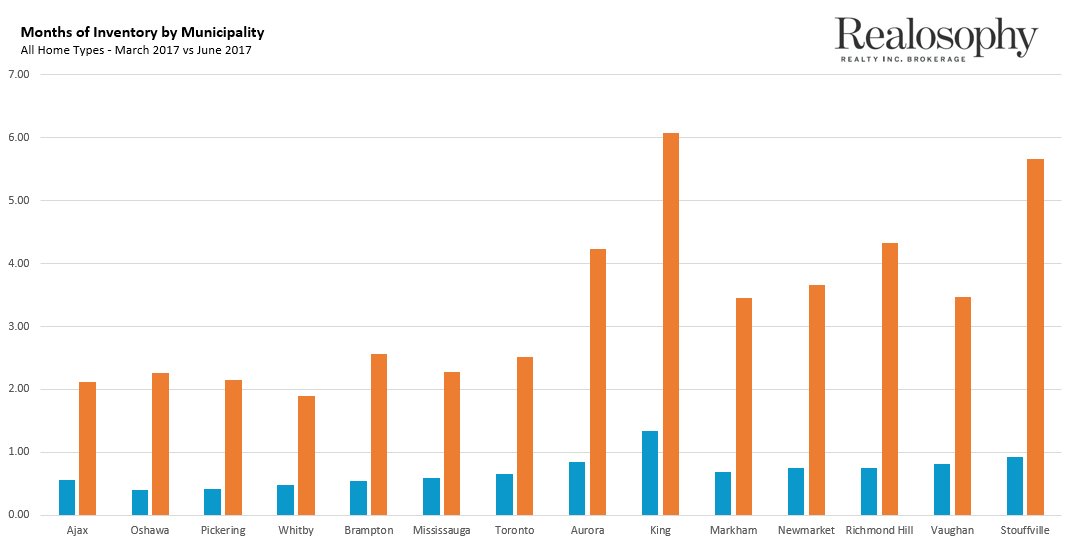
Meanwhile, the policies aimed at curbing rampant speculation in realty markets seem to be taking a hold in Ontario. This chart of months of inventory at the current rate of sales in Greater Toronto Area cities in June (orange) versus March 2017 (blue), offers a glimpse of rapidly changing supply dynamics.  What goes up on excessive credit, tends to mean revert just as aggressively.  Much more to come.

Posted in Main Page | Comments Off on Canadians using homes as ATMs