China boom retreating despite best made plans

Another weak reading from the Chinese economy with August imports falling 13.8% in U$ terms after a 8.3% drop in July.  Of course exports fell as well, down 5.5% in August after -8.3% in July. Weak exports reflect the soft sales in global markets generally, but it is the weak imports into China which are foiling the best made projections of many other countries who were banking on insatiable demand there to buoy global sales.

The world’s credit driven consumption bubble of 2001-2008 is over, and the rightsizing aftermath persists with an extended period of weaker demand as consumers work down excess debt levels and companies work down excess inventories and capacity.  This is not a quick rebound.

Even though Chinese authorities have been following tricks tried by western monetary magicians like issuing debt and intervening in publicly traded markets to prop up asset prices, thGlocal stock losses to date Sept 7 2015e net effect is still trillions in capital losses since June as graphed here from Bloomberg.
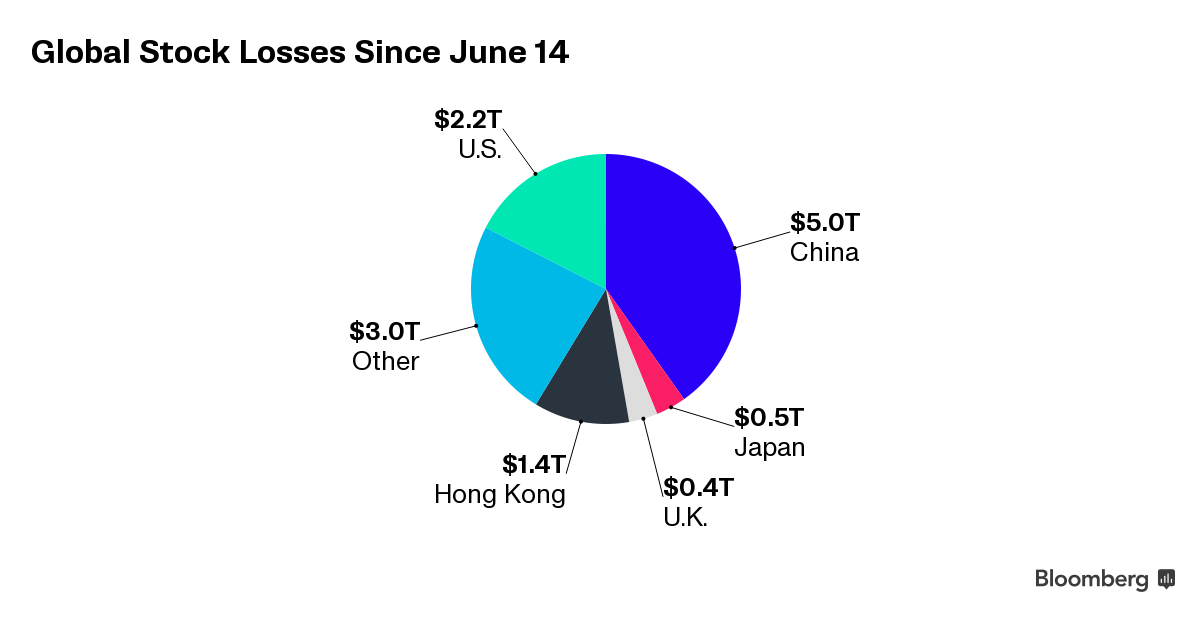
And for all those calling bottoms at every bounce, it is important to appreciate that debt levels and asset valuations are not low or even medium today, but remain near or above all time historic highs even as world GDP growth struggles to hit half of its 2007 pace.

As noted on the graph below of the Shanghai Composite since 2006, even China’s ‘officially’ fabricated reported GDP growth today is still 19% lower than its weakest read in the depths of the 2008 global recession.  Why in the world should we assume then that financial assets have bottomed with just modest ‘corrections’ to date?
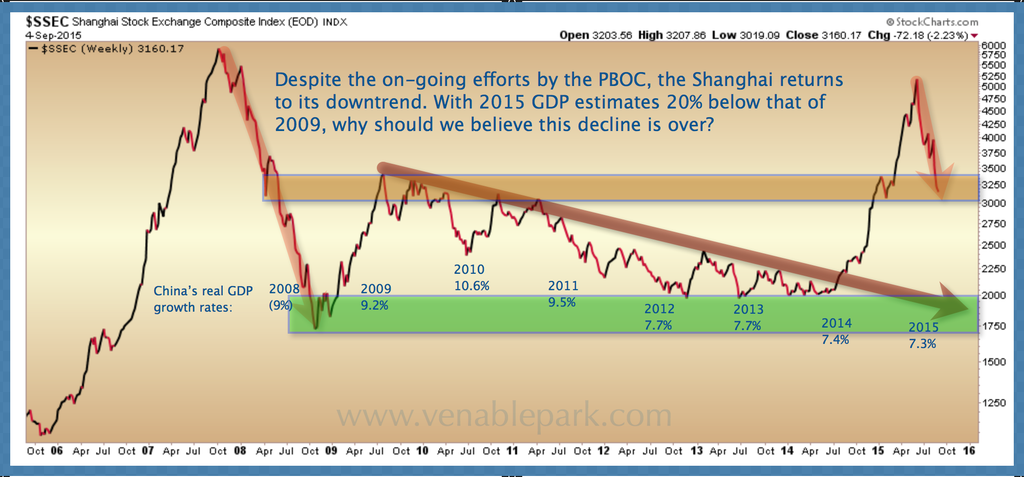
Shanghai Sept 2015

Posted in Main Page | Comments Off on China boom retreating despite best made plans

Danielle on This Week in Money

Danielle was the 3rd guest on This Week in Money with Jim Goddard yesterday, talking about recent trends in the world economy and markets.  You can listen to an audio clip of the segment by advancing the play bar to 26:17.

Posted in Main Page | Comments Off on Danielle on This Week in Money

Canadian financials heavily levered to downside this cycle

With plunging commodities and evaporating underwriting, to rising defaults in debt-laden households and top-heavy realty markets, Canadian financials have come into a rough patch. And they have earned it.  In a cruel twist of Bank of Nova Scotia’s hideous slogan:  Canadians are starting to discover that they are “Poorer than they thought”.  See: Half-empty office buildings on the rise in Calgary, Edmonton and Cracks begin to appear in Canadian bank earnings.

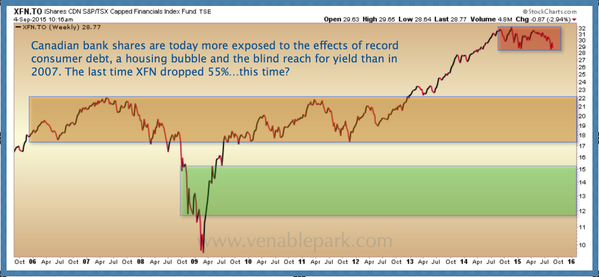
The question is how much do Canadian financial shares have to give back in order to pay penance for their most recent era of reckless excess.  As shown in this chart of the sector (XFN) since 2005, the potential downside this time should give sober capital cause for pause.  Having fallen just over 10% since April–evaporating 3 years of dividend income in 4 months–the sector would need to lose a further 45% just to retrace QE-mania over-pricing since 2010.  That would make for a total decline of 55% since the April 2015 peak and be perfectly in line with the loss cycles seen in both the 2001 and 2008 meltdowns.  But would that be enough this time?
XFN Sept 4 2015
With leverage in the Canadian banking and realty sectors higher today than at any time in the past 20 years, and with Canada now at the end rather than the start of a commodity supercycle, this time finance shares could have even further to mean revert (possibly the green band marked above).

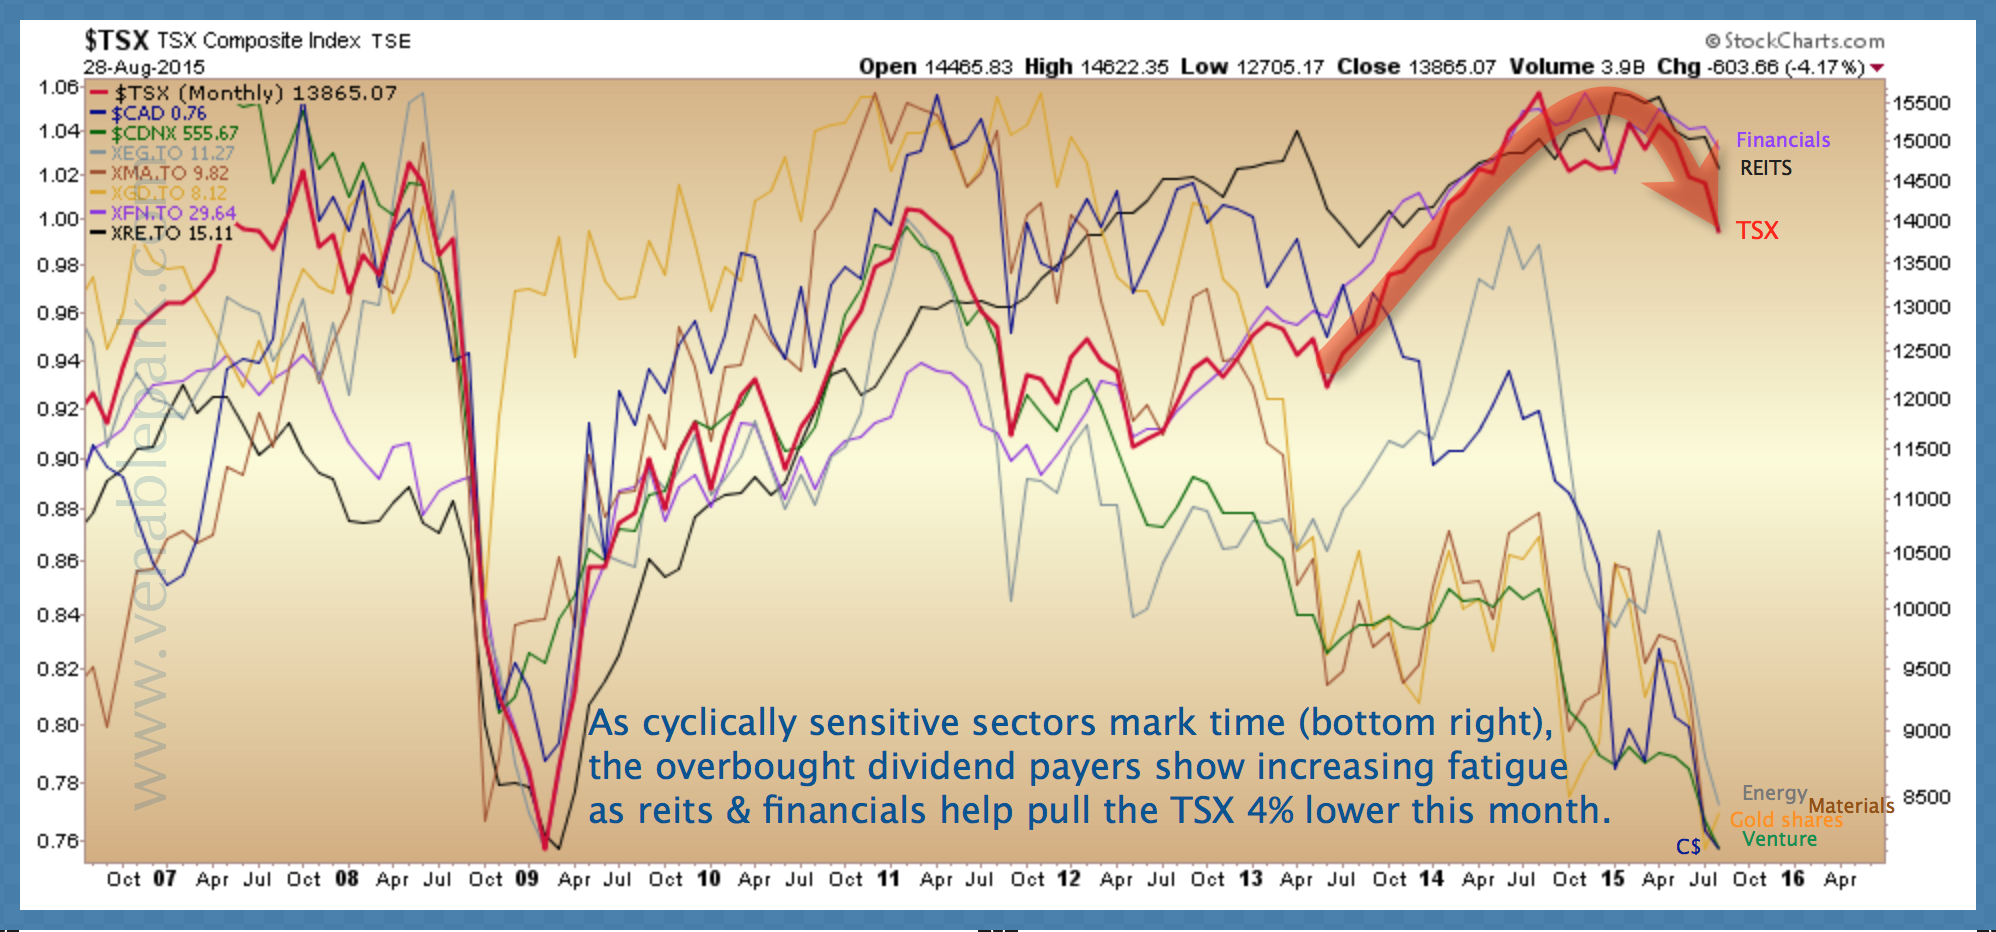
Holders and indexers of the broader market TSX–that is presently some 36% weighted in financials–should also have their eyes wide open.

TSX Aug 29 2015


Posted in Main Page | Comments Off on Canadian financials heavily levered to downside this cycle