Will the US 10-year yield move below the German once more?

With the equity mongrel horde still calling for higher interest rates and insisting that bonds are for dummies– even though the total return on treasuries has outperformed the total return on stocks by 5.7 x since 1982 (well how’s a devoted risk-seller to make outrageous commissions if people insist on owning the lowest risk deposits for heaven sake?)– here’s a thought:  what if US government bond prices were only just started into their next leg of ascent?

I have written many times about higher yielding North American treasuries being relatively attractive when compared with other developed country bonds and in an era of strong deflationary forces caused by a global debt overhang and aging demographics. See: North American Treasury yields: how low can they go? for more context.

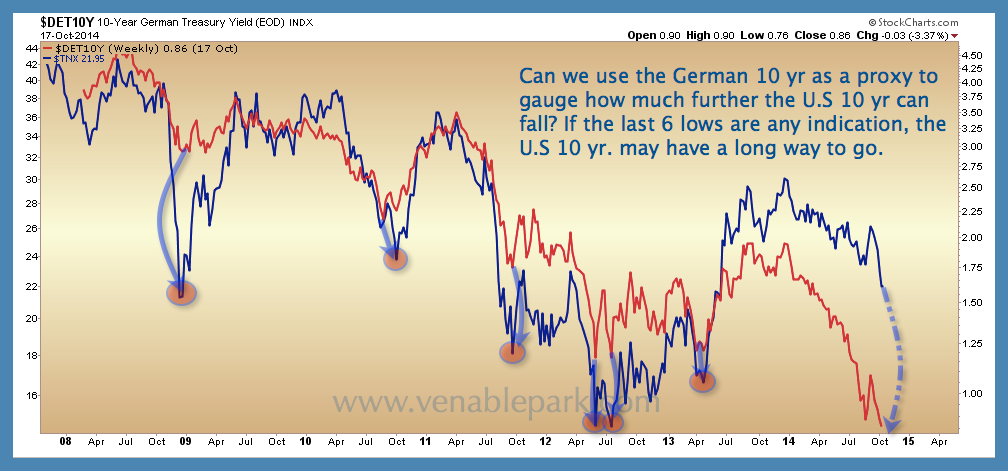
As shown in the chart below, each time the German 10-year yield has taken another leg lower during the economic ‘recovery’ over the past 6 years, the US 10-year has not only followed, but actually made a lower low (ie., US treasuries have increased in price by more).  With the German 10-year yield today at .84%, the US 10-year yield is now looking downright fat at 2.19%.  Could this time be different? Or could US 10-year yields actually move below 1% in risk-averse months ahead (as per dashed blue line) and racking up further capital gains in the process?  The answer seems to be yes.  Of course, don’t look for the investment sales monkeys to see that one coming…
German and US 10 yr yield

Posted in Main Page | Comments Off on Will the US 10-year yield move below the German once more?

Danielle’s weekly market update

Danielle was a guest today on Talk Digital Network with Jim Goddard, talking about recent developments in the world economy and markets. You can listen to an audio clip of the segment here.

Posted in Main Page | Comments Off on Danielle’s weekly market update

Loonie likely to land lower

Traditionally the Canadian dollar has tracked global demand for the nation’s rocks and trees.

As shown in the chart below, the connection between Canadian exports and the strength of its currency historically reflected in a correlation between Canadian resource-based venture companies (CDNX Index) and the loonie.  In 2011 as central banks went full nut-job with herculean promises of monetary power, the resource sector remained unconvinced and followed global manufacturing output lower, while the C$ weakened to a lesser extent.

C$ and Venture Oct 2014Over the past couple of months, the loonie has rejoined the resource sector’s trajectory but with a glaring gap now evident between the two.  This morning wildly volatile, the Canadian dollar index has now broken below cyclical support that had held out of the 2009 recovery.  Further downside to at least the last recession bottom in the .80 range seems probable, with further declines possible into the .70’s after that.

Posted in Main Page | Comments Off on Loonie likely to land lower