Good discussion on the Eurozone

Megan Greene from Roubini Global Economics talks with Michael Hewson yesterday looking at recent developments in Europe, particularly at the situation in Greece, the LTRO’s, Spain and the fiscal compact. Here is the direct link.

Posted in Main Page | Leave a comment

Excellent context on all that cash on the sidelines

Great piece from Jim Bianco of Bianco Research this morning (courtesy of the Big Picture blog):

Through Q4 2011, nonfarm nonfinancial corporate businesses held $2.23 trillion in liquid assets on their balance sheets. As the bullish argument goes, this must be a sign of pent-up demand just waiting to be unleashed on the [already over-valued] stock market.  Jim says not so much.  In the present high risk, poor value market and sluggish economy , stashing cash for later opportunities is actually a perfectly rational allocation decision. This is not a question of being chicken, or unsophisticated, but rather of exercising self-discipline, being prepared and shrewd.

” When examined over a shorter time frame, as shown below, the percentage of cash on the sidelines is at the upper end of its range of the past 30 years. Given the uncertainty in the markets, rampant volatility and the lack of good investment opportunities, this should not come as a surprise.

“While it is true that cash on the sidelines, as defined above, is at its highest level in roughly 30 years, should this be taken as a sign of pent-up demand that could lead to a huge rally once unleashed? We would still argue it is not. If and when investment opportunities become more enticing, we will see these levels fall from 14.24% to the historical norm of the past 30 years of 10%-11%. It is not as though companies currently have 40% of their assets in the form of cash waiting to be invested, as was the case in the 1950s…”  Source: Bianco Research [5]

Posted in Main Page | 2 Comments

ECRI reaffirms 2012 recession call

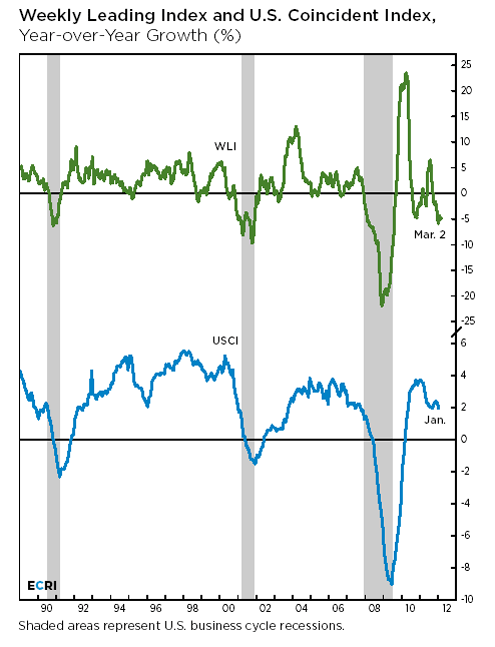
Today the Economic Cycle Research Institute issued a release with the below chart and a report reiterating their 2012 recession call. For those hoping that more liquidity injections to the banking system can avert this outcome, the ECRI is unequivocal:

“The bigger question is, can unprecedented, concerted global monetary policy action repeal the business cycle? The objective coincident and leading indexes that we have always monitored are still telling us that it cannot.”

In the chart, please note the one-to-one correspondence between the cyclical swings in the year-over-year growth rates of the WLI and USCI since the Great Recession. Both surged initially, only to roll over, pop up briefly, and then turn down once again. It is notable that the WLI, which is sensitive to the prices of risk assets that have been supported by massive worldwide liquidity injections, has hardly been swayed from its recessionary trajectory. In spite of the efforts of monetary policy makers, actual U.S. economic growth has slowed, while WLI growth has barely budged from a two-and-a-half-year low.

Click here to see their full release.

Posted in Main Page | Leave a comment