Outlook sours on tight credit and fewer loans

The May 2023 Dallas Fed bank credit survey results were just released, and the data is recessionary. It’s not just consumer credit that’s in decline. Commercial and industrial loans have contracted at a 14% annualized pace since mid-March and loans to commercial real estate at a -4% annualized rate. See Banking outlook continues to deteriorate amid further credit tightening, declines in loan demand.

Loan demand declined for the sixth period in a row amid further loan pricing increases and worsening general business activity. Overall, loan volumes continued to decline as well, though at a decelerated pace. Residential real estate loan volumes stabilized after falling for several months, and consumer loan volume declines slowed notably. Significant volume declines continue to be seen in commercial and industrial and commercial real estate lending. Credit conditions tightened further; 48 percent of bankers said they tightened credit standards and terms over the past six weeks, the highest share since the survey began in 2017. Loan nonperformance continued to increase slightly. The banking outlook continues to deteriorate, with contacts expecting a further contraction in business activity and loan demand and an increase in nonperforming loans over the next six months.

Posted in Main Page | Comments Off on Outlook sours on tight credit and fewer loans

Stressed consumers pulling back

The segment below offers a good big-picture overview of the interplay between incomes, consumer spending, economic growth and home prices. Canadian data looks worse than the US, but, so far, Canadian banks have allowed negative amortization to compound principal higher where payments are insufficient to cover principal and interest payments.  Many variable-rate borrowers have had their amortization period extended well beyond 30 years in the process. Extend and pretend cannot continue indefinitely; a pick up in forced sales looks inevitable as unemployment ticks higher.

Bank of America just reported a big slowdown in consumer spending in America. Which is a major 2023 recession warning. And suggests that we could see job losses spike in future months with home prices and stock prices declining. Consumer spending on Bank of America credit/debit cards declined most in Furniture, Home Improvement, and Luxury Goods. While spending still rose for restaurants. Overall, spending was down -1.2% YoY from last April. Declining consumer spending is a big problem for the US Economy because 70% of GDP comes from spending. So it means our economy is decline. And likely that businesses will continue to lay off workers in 2023.

Another company that had a concerning report was Airbnb. Their stock price is down by 15% in the last week because they had a “muted” outlook for travel demand in the rest of 2023. A slowdown in Airbnb bookings would mean that certain housing markets might have issues. The ones with the biggest drops in occupancy include Miami, Philadelphia, Fort Lauderdale, Austin, San Antonio, and Cape Coral.  Here is a direct video link.

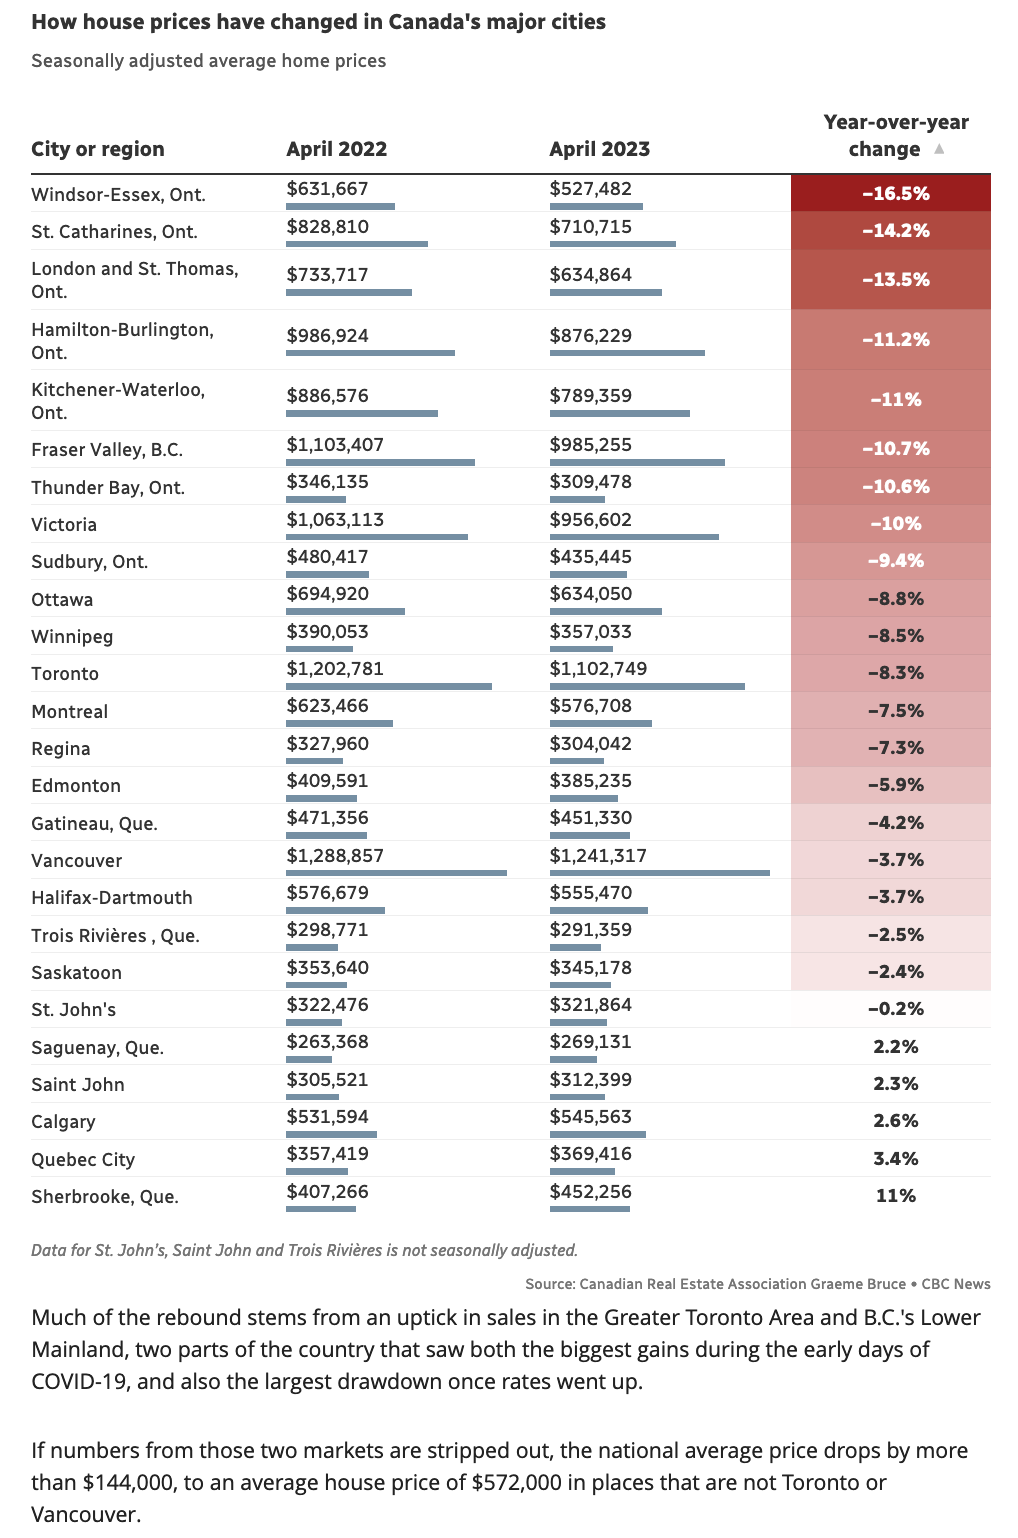
For repricing progress to date in major Canadian cities, see more here: Average Canadian home price $716,000 in April.

Posted in Main Page | Comments Off on Stressed consumers pulling back

Baby boomers helped inflate property prices, their demise suggests the opposite

Baby boomers and two decades of rock-bottom interest rates drove a structural boost to housing demand as older buyers/investors sought bigger homes as well as recreational and rental properties. As interest rates have risen and boomers die off, the question is who will buy from them and at what price?

The pandemic and a shortage of attractive retirement home options increased reluctance to downsize. Still, older homeowners will surely fall off the property ladder through death, and the downward pressure on prices promises to be significant across many countries. See some of the stats in House prices face a looming hit from the baby boomers who got rich off property:

There are two factors at play. First, the baby boomer generation is very big. Second, they are much more likely to own property than other cohorts.

In the US, the number of owner-occupiers who will stop owning homes between 2026 and 2036 will number between 13.1 million and 14.6 million, according to a 2018 paper by Dowell Myers and Patrick Simmons.

“The beginning of a mass exodus looms on the horizon,” the economists warned.

Because of the relatively large size of the baby boomer generation, the number of homeowners exiting the sector will be 42pc higher than it will have been in the preceding 10 years.

The trend is mirrored in the UK. Between 2008 and 2020, the share of homes owned by people aged over 75 jumped from 13.3pc to 18.1pc – equivalent to an extra 837,000 properties – according to the English Housing Survey.

Not only are boomers more likely to own property, but they are more likely to own more than one: holiday home ownership and buy-to-let ownership is extremely heavily concentrated amongst older generations.

Posted in Main Page | Comments Off on Baby boomers helped inflate property prices, their demise suggests the opposite