Danielle was a guest with Jim Goddard on Talk Digital Network, talking about recent developments in the world economy and markets. You can listen to an audio clip of the segment here.
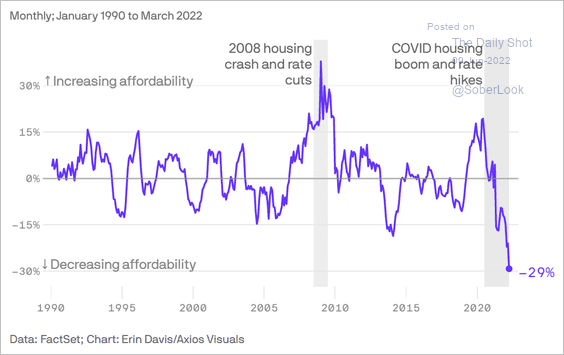
As shown below, highly-indebted, income-insecure, cash-light US consumers have not felt this bummed since the great recession when stocks were off 50%, and many were losing homes and jobs. Things are feeling tough now, but the market and economic downturn have barely started. Rough!
Posted inMain Page|Comments Off on Danielle’s biweekly market update
The higher the ratio of investors and secondary buyers in a housing market, the less stable prices tend to be.
In urban areas within an hour’s drive of Toronto (broad GTA), the average sale price topped $1,000,000 in February 2022, and so-called investors bought an estimated 40% of properties sold over the prior two years. Most used lines of credit to buy.
Many more properties were bought as secondary residences (vacation chalets, cottages etc.) with downpayments taken from HELOCs and mortgages against primary residences.
The Canadian median home sale price touched $816,000 in February–more than 12x the median after-tax household income of $70,000 and compared with a long-standing affordability norm of 3 to 4x.
With high prices, rental properties purchased in the past few years mainly were low or negative-yielding but bought on the presumption that prices could only rise. Now that carrying costs have risen sharply over the past year, property prices are stagnant and falling in most areas, and the urge to sell is contagious.
In America, median home prices recently reached some 6.5x the median household income. While much more affordable than Canadian home prices, the record 29% deterioration in US housing affordability since 2020 is the worst since 1987 and nearly twice as bad as the last housing bubble top in 2006 (chart below courtesy of TheDailyShot.com). Housing analyst Nick Gerli explains that high prices and interest rates have driven low home affordability and set the foundation for another bust cycle.
Housing analyst Nick Gerli returns to the program to warn how swiftly the prospects for home prices are eroding. Confidence in the housing market was supreme just a month or two ago, and suddenly that confidence is vaporizing as an increasing number of experts now caution of a “full-blown” correction ahead. Rising mortgage rates are a huge part of the equation, but we’re already starting to see sales slowing and even price cuts in a number of markets — especially the markets that have been the hottest in past recent years. Does Nick still think prices could come down by as much as 30% on average? Could we see price declines on par with the 2008 crisis? Here is a direct video link.
Posted inMain Page|Comments Off on Housing downturn in motion
Consumer layaway plans were popular in the debt-fueled boom before the market and economic crash of 1929. Every cycle, finance rolls out old leverage tricks enabling a near-term consumption bump by selling sketchy debts to indiscriminate investors. Same junk another day. Nothing new here; see Funding squeeze at buy-now-pay-later firm flashes warning:
Some of the riskiest loans given to millennials and Gen Z shoppers for clothes and electronics — and neatly repackaged for investors — are dropping in value.
Securitization packages of buy-now-pay-later loans from one provider, Affirm Holdings Inc., are falling in price for investors to buy while becoming more expensive to issue, after rising rates and a cost of living crisis cast a shadow over the sector.
Affirm has over 12.7 million customers and extended around US$3.9 billion of loans in the first three months of 2022. It was valued at US$47 billion in September after a blockbuster listing on Nasdaq in January 2021, but its shares have fallen over 80 per cent this year.
Posted inMain Page|Comments Off on Pain for buy-now-pay-later loan investors
“An explosive critique about the investment industry: provocative and well worth reading.”
Financial Post
“Juggling Dynamite, #1 pick for best new books about money and markets.”
Money Sense
“Park manages to not only explain finances well for the average person, she also manages to entertain and educate while cutting through the clutter of information she knows every investor faces.”
Toronto Sun