Rate shock pandemic spreading

Yesterday, US Fed head Jerome Powell ramped up talk of inflation-fighting rate hikes and aggressively reducing the Fed’s balance sheet. Bond prices have tumbled, as debt service costs leap for the public and private sectors.

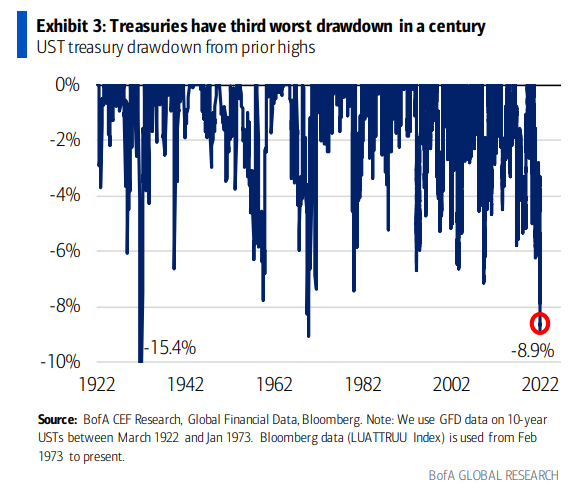
Over the past seven months, US ten-year Treasury prices (the flip side of yields) have seen their third-largest drawdown of the last century (as shown below). Touching 2.187% this morning, the US two-year Treasury yield (up from 1.80% last week and .149 last June) was just .16% below the ten-year–a fresh cycle low and the narrowest spread since the last recession began in 2020.
The US thirty-year bond at 2.59% (up from 1.20% in July 2020) is lower than the 20-year as the curve has inverted at 30-20, 3-10 and 5-10 terms.

Along for the rise in yields, the 30-year US mortgage rate is up to 4.72% from 2.75% in November 2021, just as the median listing price reached $392,000 in February (from $300,000 in March 2020)  As shown below, higher prices and mortgage rates have combined for a 28% leap in homeownership costs–the fastest and largest since 1987.

In Canada, five-year Treasury yields have rocketed to 2.237% from .78% in August 2021, taking the five-year fixed mortgage rate above 3.5% at all major banks from 1.5% in early 2020.  Over the same time, the median home price is up about 64%, from $530,000 to $870,000 nationally, making housing affordability positively grim.

While fixed mortgage rates move with the bond market’s expectation of Fed policy, variable-rate mortgages move with the rate hikes themselves. From around 1.65% today, Canadian variable-rate mortgages should rise to about 3% over the next 12 months if the Bank of Canada delivers on the five hikes currently telegraphed. This will be a significant increase for the 35% of Canadian mortgages presently variable.

Interest rates are also on the rise on business and personal loans, credit cards, lines of credit, bank overdraft and margin interest charged on brokerage accounts. All on top of the spike in food and gas prices.

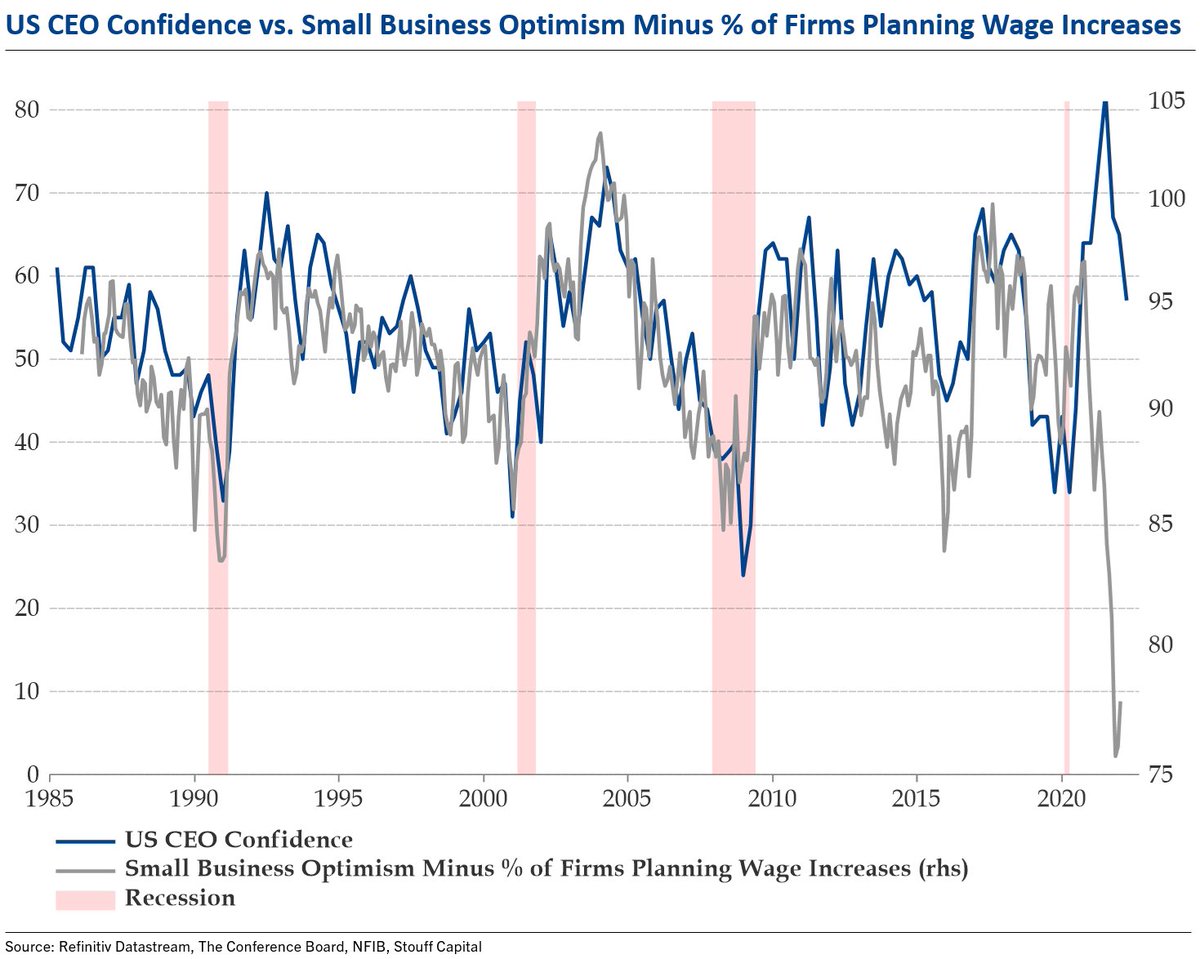
Financial stress is rising, and consumers and businesses are necessarily pulling in their spending and investment plans. Consumer confidence is slumping along with small business, and CEO confidence (below since 1985 courtesy of Julien Bittel) as free cash flow, revenue and profit margins shrink.
There is no doubt that politicians and central banks are unnerved by the recent rise in inflation and Russia’s war on Ukraine has intensified the shock and urge to “do something!”

In reality, in our highly levered world of households, businesses and financial markets, the tightening to date has already been massive and is undermining economic momentum.

As shown below with the 10-year US Treasury yield since 2008, rates have repeatedly risen during loose monetary conditions, only to tumble again as conditions tighten and the economy and risk assets slump. We’re there again now.
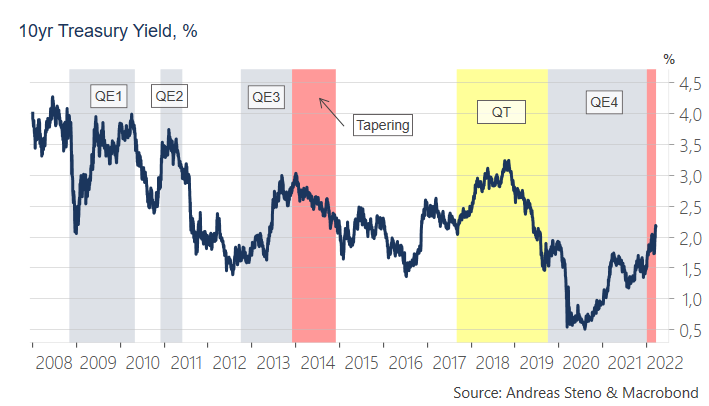
Central banks can talk up further tightening plans, but the bond market has already done their work. As the economic downturn intensifies, growth and inflation expectations will tumble with yields as Treasury bonds rebound, and policymakers shift back to trying to revive borrowing, animal spirits and asset prices. That could take years for the many who will suffer financial setbacks between here and there.
Posted in Main Page | Comments Off on Rate shock pandemic spreading

Canada’s unaffordable housing comes with long-term financial drag

The price of the average Canadian home hit $816,720 in February, its highest level on record (Canadian Real Estate Association).

The $816,720 average selling price is up 20 percent compared to last year’s level. In the most populated areas of the Greater Toronto and Vancouver areas, the average selling price exceeded $1 million. Without these two cities, the national average price was also a record high at $638,720.

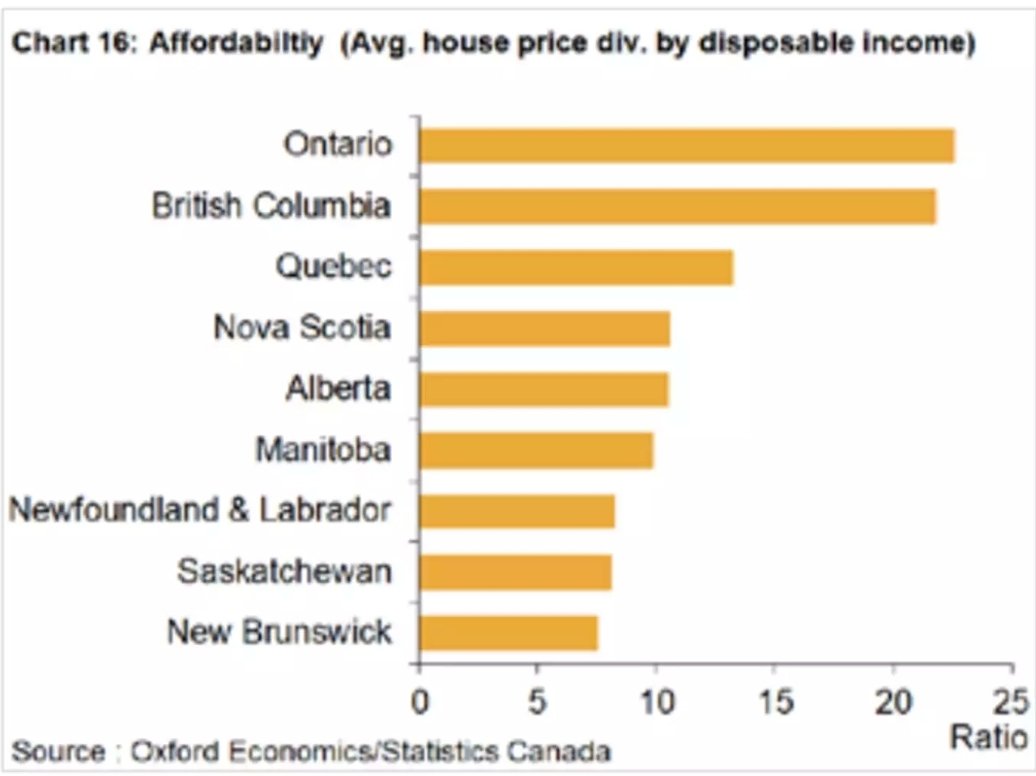
The average house price divided by disposable income is a precarious 23 in BC and Ontario (chart below). Many have necessarily given up on homeownership dreams. Many of those who do own are so indebted that they cannot meaningfully accumulate savings for other critical goals like retirement, education, emergency funds and new business creation. All of this has a long-term economic drag on households and the economy.

After doubling with the oil patch boom from 2004 to 2008, Calgary home prices fell 25% and largely flatlined for 15 years to 2020 (a typical historical pattern that followed past housing booms in Canada and other countries). Then, over the past year, relative value has attracted inflows (average price in Calgary $487,000 per CREA), and benchmark prices in the city leapt almost 9% in the past three months–the fastest clip since the heady days of 2006.

As with everything, high prices ultimately become the cure for high prices and this credit and speculation-driven cycle is unlikely to end differently than the hundreds that have preceded it globally.  Those who lever in late are likely to suffer one way and another.

Institutional investors and funds hoover up existing homes, pushing up prices and rents while funding new supply at a record clip (see Wall Street’s favourite suburban housing bet is getting crowded). The value of building permits in Canada hit $11.2 billion in November—the highest ever recorded. New private housing units under construction in America hit a 49-year high in January, with 1.543 single- and multi-family units in process—the most since 1973. Population-adjusted this matched the peak of the U.S. 2004-2007 building frenzy. In January, the 1.899 million U.S. building permits were also the highest since December 2006.

Bank of Montreal economist Robert Kavcic noted last week:  “Demand has been boosted by expectations of rising prices and a last-ditch effort to lock in cycle-low mortgage rates. But sentiment can change in a hurry, and this market could find balance very quickly the moment that it senses softer prices.”

While prices in Canada’s hot housing market continue to hit record highs, experts predict they could cool down if the supply increases alongside further interest rate hikes.  Here is a direct video link.

Posted in Main Page | Comments Off on Canada’s unaffordable housing comes with long-term financial drag

High gas prices accelerate energy evolution

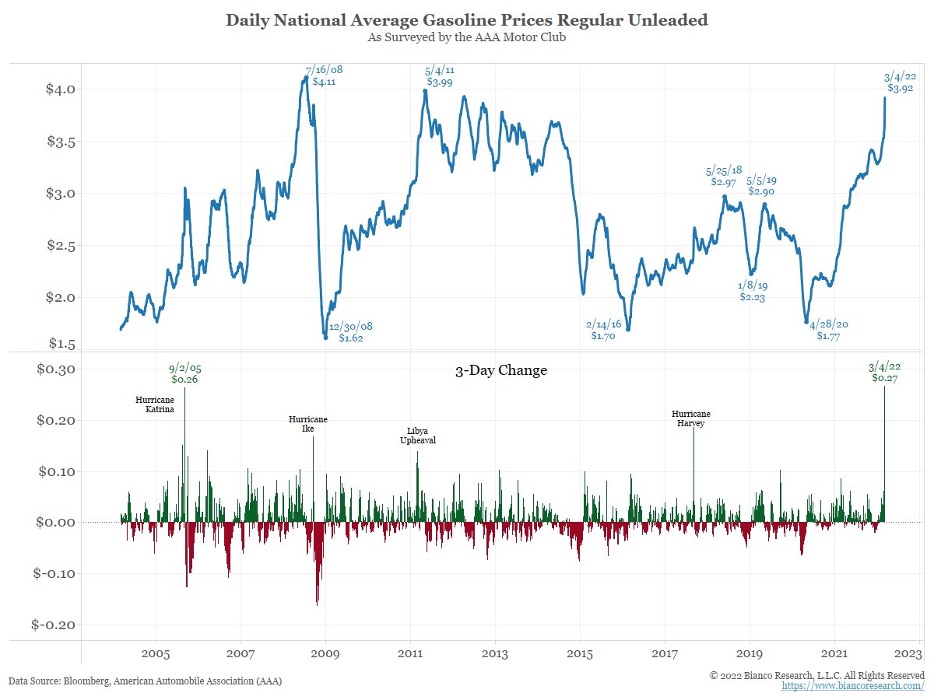
Just as employers are stepping up return to office mandates, gasoline prices are the highest in eleven years. Consumer pain is a valuable behavioural catalyst.

Half of the Canadian respondents to a recent Leger poll survey said they were now using their vehicles less; one-third said they were looking to buy an electric vehicle. I can attest to this trend as people are approaching daily to ask about our electric cars. Yes, we charge them in our garage overnight for about $5.00, and they can go 400 km on a single charge.  In addition, their cost of operation is dramatically reduced by 90% fewer parts to repair, replace and service, and a life expectancy greater than 800,000 km.

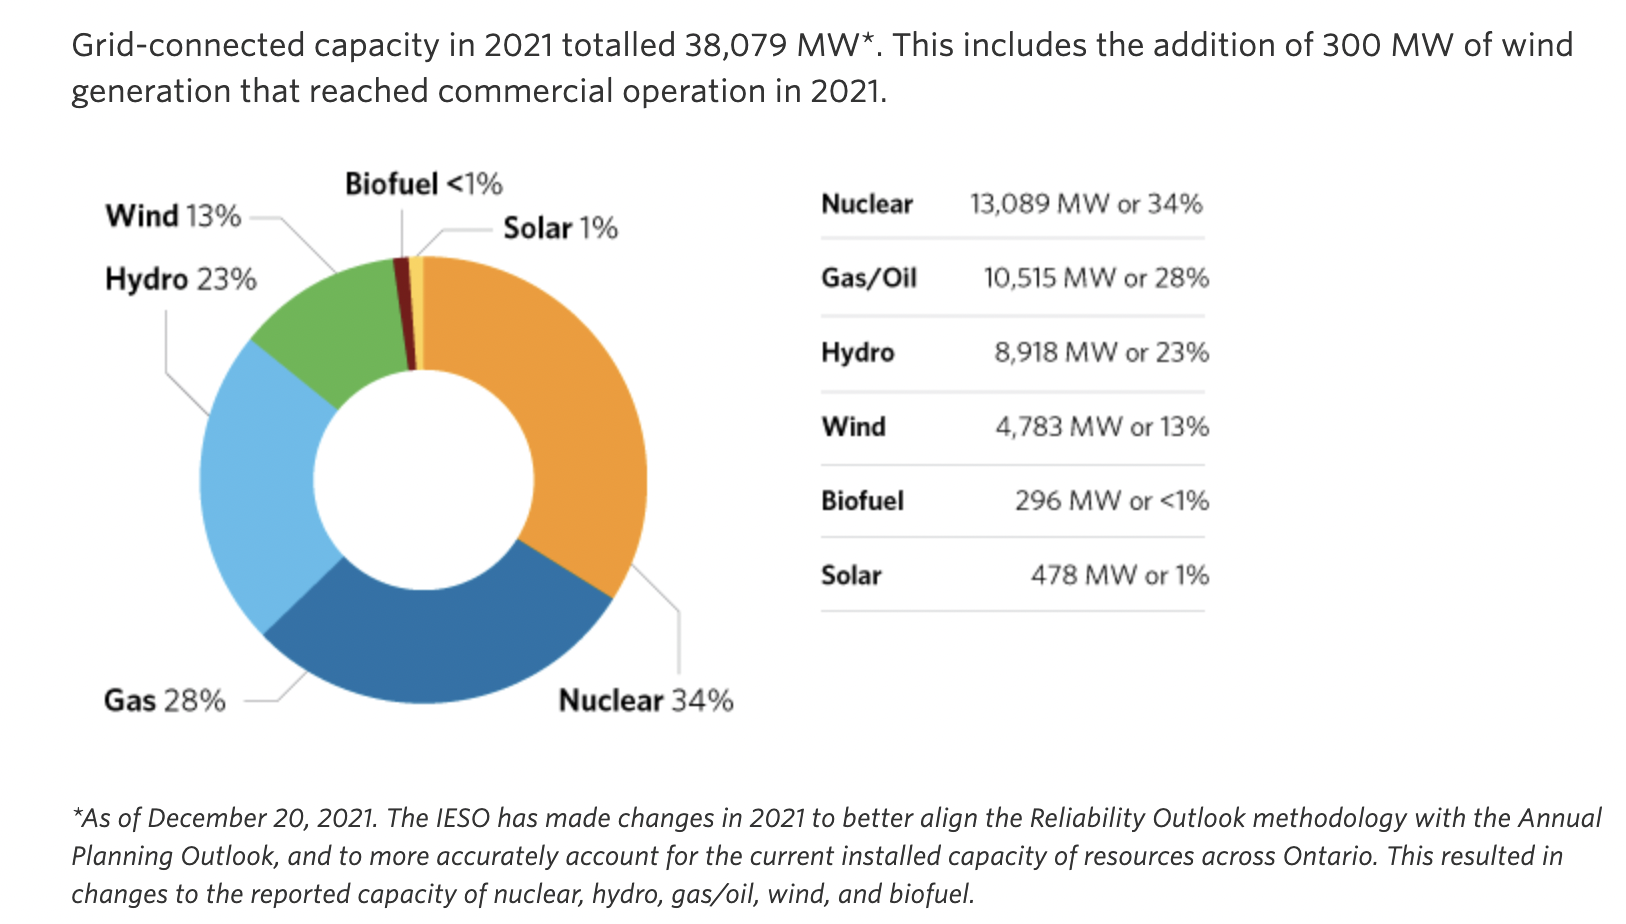
Yes, electrical power is more efficient and a lot cleaner than burning oil and gas in Ontario because 72% of the grid is powered by renewable energy sources as shown here.

Yes,  a shortage of nickel–an integral component of most lithium-ion batteries — is a hurdle.  And that is why metals recycling and alternate battery types are now seeing massive investment and innovation globally.

Six years ago, think tank RethinkX’s co-founders Tony Seba and James Arbib correctly anticipated that Russia would become a geopolitical flashpoint in the 2020s. Read: How Energy Disruption Led to Russia-Ukraine Crisis – and How the Crisis Will Accelerate Disruption.

Seba and Arbib told US military leaders that they would need to consider the probability of Russian aggression in the early-2020s. Seba’s projections showed that the acceleration of solar, wind, batteries, and EVs would make incumbent fossil fuel industries economically obsolete by 2030. The military and geopolitical systems these industries and countries are predicated on also become obsolete in the process. Countries primarily dependent on fossil fuel industries– and to perpetuate their internal political hierarchies–are at risk of resorting to traditional strategies of self-perpetuation and control to keep the cash flow going as long as possible.

350.org founder Bill McGibbon explains the opportunity and necessity in using the ongoing fossil fuel crisis to accelerate the transition to renewable energy in his latest article, In a world on fire, stop burning things. He speaks directly to Canadians:

Canada has fossil-fuel reserves totalling a hundred and sixty-seven petawatt hours, which is a lot. (A petawatt is a quadrillion watts.) But, he said, it has potential renewable energy from wind and solar power alone of seventy-one petawatt hours a year. A reasonable question to ask Trudeau would be: What kind of country finds a windfall like that and simply leaves it in the sky?

McGibbon talked to the CBC’s The Current on March 18 here in Fighting Putin and climate change at once.

Nothing about this necessary transition is easy. A war effort is required, to be sure. But then, nothing about the status quo is easy, affordable or sustainable. We evolve or die.

Posted in Main Page | Comments Off on High gas prices accelerate energy evolution