Pop Quiz: What would it take to return the TSX to where it topped in 2008?

The oil and gas overweight (13%) in Canada’s TSX typically helps buoy the Canadian stock market late in each market cycle.  Oil prices leap, explode the highly levered global economy and then plunge with demand once more.  Comparatively, just 3% of the S&P 500 is oil and gas.

With West Texas Crude back at an eight-year high today–last seen in 2014, and before that in the commodity cycle peaks of 2008-2011– the TSX is less negative this afternoon than most global markets.  With the S&P off nearly 8% from its December high, the TSX is down less than 2 percent since October.

Interestingly, currency traders are not buying the trend, with the loonie at .786USD, down against the greenback on the day, week, month and year to date.

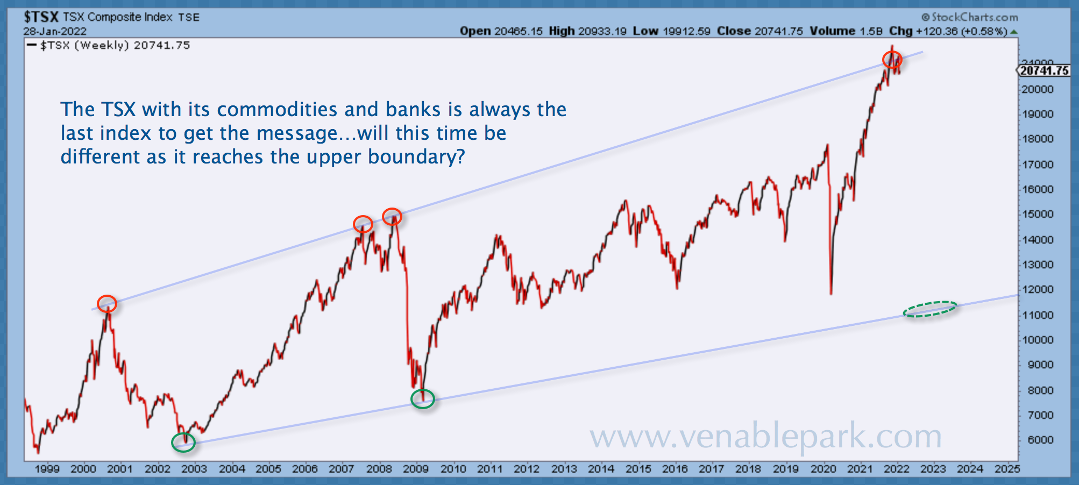
As shown below from my partner Cory Venable since 1998, after going parabolic on retail inflows during 2020 through 2021, Canada’s TSX index (which most Canadian stock funds, ETFs and equity portfolios track) is precariously peaked.  Few present holders appreciate how vulnerable this makes their capital.  Or that a relatively modest 30% bear market from here would return the Canadian stock market to the 15,000 area where it topped with oil in June 2008–13 years ago.  And with secular support in the 12,000 area (lower line above), a 30% retracement would be a historically modest correction cycle from here.
Who will have outperformed then?  We are going to find out.
Posted in Main Page | Comments Off on Pop Quiz: What would it take to return the TSX to where it topped in 2008?

Yield curve and consumer sentiment flatten with January inflation

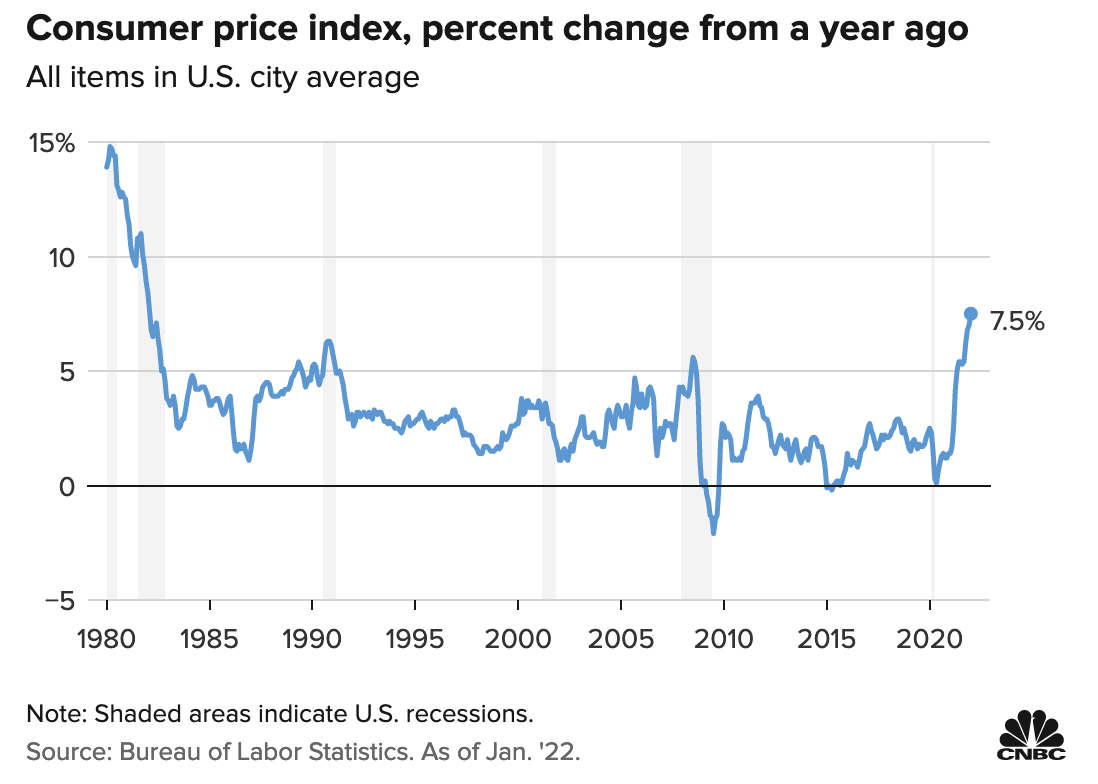
The consumer price index for January rose 7.5% compared with a year ago and was slightly higher than the consensus estimate of 7.2%.  As shown on the left courtesy of CNBC, this was the highest on this reading since February 1982.

Meanwhile, real earnings for workers increased just 0.1% on the month, and University of Michigan consumer sentiment fell to 61.7 in January vs. 67.2 in December.  Consumer expectations tumbled to 57.4–both the lowest readings since 2011.  See:  What to expect when consumers don’t expect inflation to last.

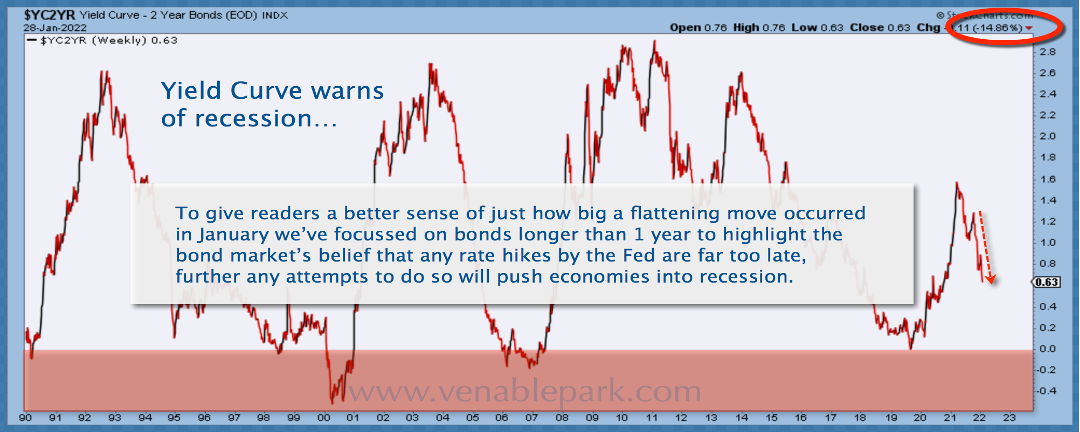
The bond market accelerated its bearish flattening on the news, with short bond yields leaping more than long yields.   This afternoon, the spread between the US 10 and 2-year Treasury yield is just .44%.   As shown in my partner Cory Venable’s chart below of the spread at the end of January, this economically-insightful metric was .63 just 11 days ago and has been tightening steadily over the past year on dimming economic prospects into 2022.  The 7, 10, 20 and 30-year Treasury yields all touched above 2% today (although just a .30% difference from the shortest to the longest).  The last time the US 10-year was at 2% was in July 2019, when the policy rate was sitting at 2.375% compared with the financial incentive-distorting .08% today.

Nearly two years of zero rates have been another epic central bank policy mistake.  And, coupled with unprecedented fiscal stimulus early in the pandemic, has inspired ominous debt, housing, cryptocurrency, commodity, and stock market bubbles, all simultaneously.

Adding insult to cash-stressed households, oil prices are roaring in classic late-cycle style.  West Texas Crude and Brent are both above $93 this afternoon.

Cue the end of QE and a whopping seven policy rate hikes priced into market expectations for 2022.  No wonder most of the stock market has been falling for months now.

A perfect financial shit storm is now unfolding—all demons of our dumb design.

Posted in Main Page | Comments Off on Yield curve and consumer sentiment flatten with January inflation

Grantham: super bubbles harm real life financial plans

Holders typically love it when asset prices rise far above long-term norms. But gains accidentally made in the bubble phase are always taken back in the bursting, and most participants are left worse off in the end.  Believe it or not.  As Grantham puts it “sooner or later, you will have made money to have sidestepped the bubble phase.”  Meanwhile, saving, spending discipline, and compounding time, most relevant in individual lifespans,  lost forever.

Our guest this week is Jeremy Grantham. Jeremy is the long-term investment strategist at his namesake firm, Grantham, Mayo, Van Otterloo & Co., or GMO, which he co-founded in 1977. He serves on GMO’s Asset Allocation Committee and board of directors. Here is a direct video link.

Posted in Main Page | Comments Off on Grantham: super bubbles harm real life financial plans