Restaurant sector disruption continues

A couple of weeks ago, we met friends for dinner indoors at a well-established, mid-range bar-restaurant that had been busy for years before the pandemic.  We made a reservation, presented proof of vaccination as required, and were one of just three tables occupied at 730 pm on a Saturday night.  We felt for the staff and management.

Despite 72% of Canadians being fully vaccinated, the economic costs of the pandemic are ongoing.  Even restaurants that cater to the wealthiest patrons are in trouble; see Canada’s High-End Restaurants Struggle To Survive:

“Fine dining is going to completely change. It’s going to become casual fine dining. … I just had a management meeting, saying we have to be more accessible to people,” Mr. Vij said. “Allow them to come to the restaurant maybe once a month instead of every three months, or we won’t survive.”

It’s not just that the pandemic has reduced traffic and increased costs.  It has catalyzed change in consumer behaviours.  More people have learned that cooking at home can be rewarding and healthier, physically and financially.  Some 20% in recent surveys say they are not planning to return to their previous eating out frequency.

The hard truth is that some of this is a necessary downsizing of a restaurant sector that became widely over-built during the credit bubble of the past decade. The impacts continue for employees and suppliers as well as landlords and commercial real estate.

Posted in Main Page | Comments Off on Restaurant sector disruption continues

Canada leads in most unsustainable housing bubbles

Canada has a housing problem that magnifies economic and social instability through malinvested resources, oppressive debt, low savings rates, reduced household formation, low birth rates, gambling and drug addiction.  Anyone that doesn’t understand the policy-supported links between casinos, money laundering, narcotics, crime and unaffordable home prices should invest some time digesting Sam Cooper’s investigative reporting laid out in interviews and his 2021 book Wilful Blindness.  The money trail has been documented by law enforcement for years.

A new UBS study confirms that housing bubbles accelerated over the past year as the pandemic ignited a global spending spree enabled by central bank and government stimuli.  As shown below, the Greater Toronto Area now ranks with Frankfurt as having the most over-valued housing in the world.  Vancouver is in the top six.  More than a third of Canada’s population lives in the greater Toronto, Vancouver and Montreal areas; one-half of that third is in and around Toronto.  Not surprisingly, then, the most indebted households are also in these areas.


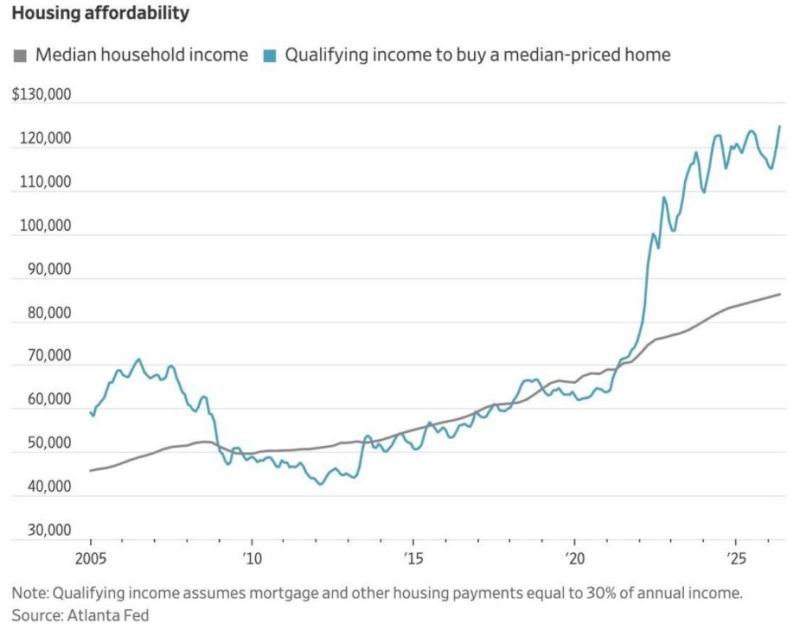
The report notes that the likelihood of a severe price correction rises with bubble readings and that worsening affordability, unsustainable mortgage lending, and a rising divergence between prices and rents have historically served as forerunners of housing crises:

Households have to borrow increasingly large amounts of money to keep up with higher prices. As a result, the growth of outstanding mortgages has accelerated almost everywhere in the last quarters, and debt-to-income ratios have risen—most markedly in Canada, Hong Kong, and Australia. Pressure is mounting on governments and central banks to take action. Lending standards, which were relaxed during the pandemic, are being tightened again. Additional hurdles for professional housing investors and foreign buyers already loom on the horizon. Overall, housing markets have become even more dependent on very low interest rates, meaning a tightening of lending standards could bring price appreciation to an abrupt halt in most markets.

No country has ever gotten out of a housing bubble without a bust.  The solution is not to add more debt and unaffordable supply, but rather for prices to mean revert back to rational multiples of rent and income.  This has to happen because the status quo is inherently self-destructive.  At the same time, the worst economic contractions have coincided with falling home prices.  There can be no sustainable equilibrium without price pain first.

Posted in Main Page | Comments Off on Canada leads in most unsustainable housing bubbles

China leading commodities and the world lower

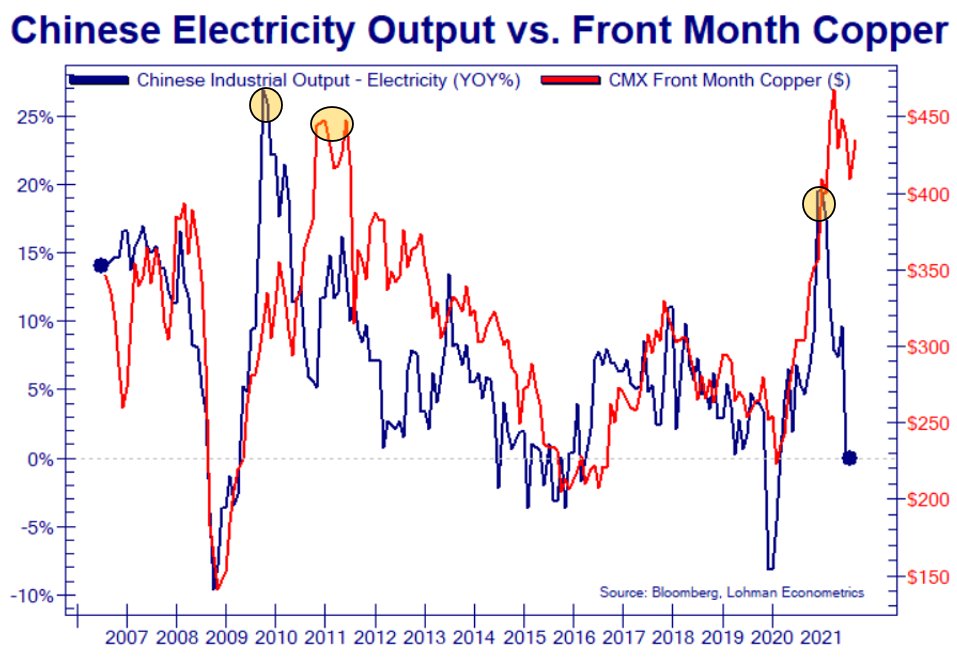
The cyclicality of Chinese electricity output is shown below year over year in blue since 2006.  Now in a significant cyclical (and secular) decline, China’s economy has major implications for industrial commodities like copper (in red), which spiked from March 2020 to March 2021 on unprecedented cash injections into households, businesses and financial intermediaries globally.  The mean reversion in Dr. copper (the Ph.D. in economics) and many other economically sensitive commodities is likely just begun.
At the same time, global economic growth peaked in the second quarter of 2021 and has turned lower since.  The I.M.F.’s latest update estimates 2022 global economic growth will be 17% lower than in 2021.

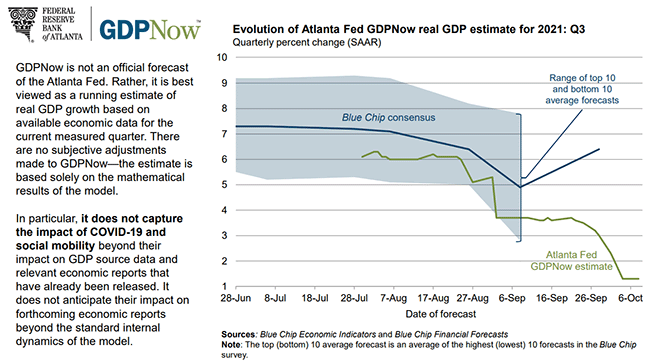
As shown below in blue, an optimistic consensus forecast for U.S. G.D.P. began June above 7%, before dipping to 5% in September.  The Atlanta Fed GDPNow forecast began August above 6% and is now tracking at 1.3% (in green).

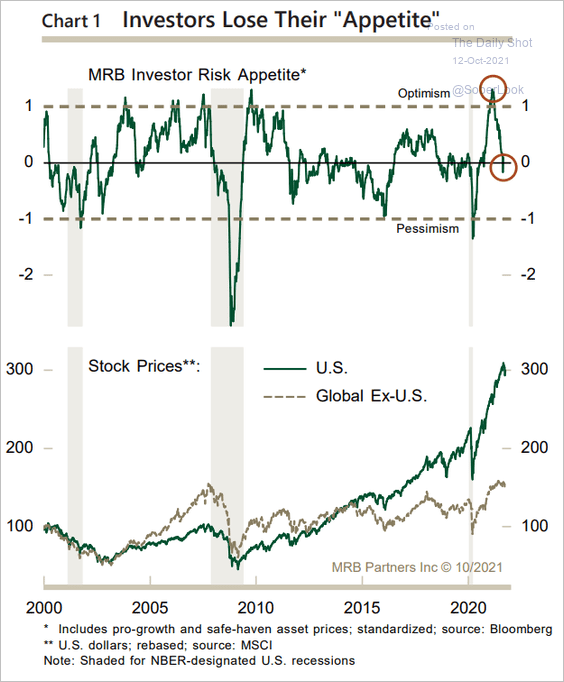
As shown below (upper panel), financial market optimism also appears to have peaked with parabolic stock prices in the second quarter.
In the lower panel, we see that global stock prices, ex the U.S. in brown since 2000, have rolled over near their 2008 cycle highs once more.  This is how secular bears move.  Only when valuations have collapsed back below long-term means and laboured there long enough to crush animal spirits does the next secular expansion begin from the ashes of investor pessimism.

We also can see that U.S. stocks (lower panel in green) have so disconnected into a world of their own dreaming that a 30% retracement from present levels would not even violate their 2009 uptrend.  History suggests that a loss of twice that much is likely.

Posted in Main Page | Comments Off on China leading commodities and the world lower