
Stock-linked pay driving destabilizing trends

A new analysis by the Economic Policy Institute finds that CEOs of publicly traded companies in the United States saw their compensation rise by 1,322% between 1978 and 2020—while the pay increase of the typical worker was just 18% during that same period.  See Since 1978 CEO pay has risen 1,322%.

As shown below, in 2020, executives at the largest public firms were paid 351 times as much as the typical worker from 21 times in 1965 and 61 times in 1989.  During the first year of the pandemic and the worst recession since the 1930s, CEOs saw their compensation increase by 18.9% while typical workers—those who could hold on to their jobs amid mass layoffs—rose just 3.9% over that time, EPI shows. 
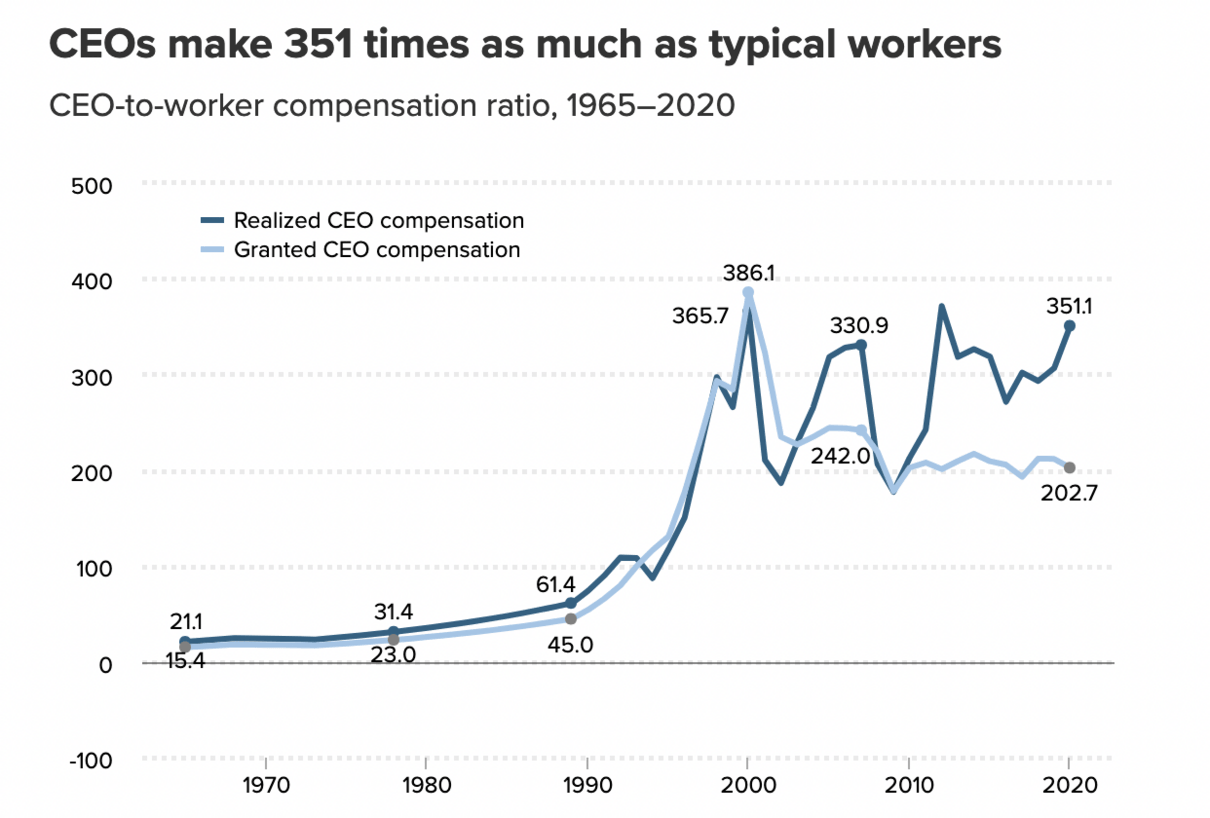
In addition to salary, CEO pay includes stock-linked bonuses, incentive payouts, and exercised stock options.

As in 2000 and 2008, the stock market bubble is driving destabilizing income discrepancy and political purchase at the expense of democracy along with a perverse and myopic fixation on keeping stock prices elevated rather than longer-term, productive investment, responsibility and risk-mitigation decisions.

When the asset bubble bursts again, some of this will correct as it did in 2001-03 and 2008-09. Still, new policies restricting share buybacks and linking executive pay to longer-term producer responsibility and balance sheet management are much needed.


Posted in Main Page | Comments Off on Stock-linked pay driving destabilizing trends

Market scams and fraud ‘top to bottom’

This discussion offers insight into the present ‘investment’ landscape dominated by scams, fraud, deception and participants that are oblivious or apathetic and speculating anyway. Not just in China…Whatever people are doing here, it’s not investing.  Gaming perhaps; but it’s not a game.  Individuals have everything to lose.

Posted in Main Page | Comments Off on Market scams and fraud ‘top to bottom’

Typical speculator experience: temporary profit and ultimate loss

John Hussman’s August letter The Folly of Ruling Out a Collapse is historically illuminating, as always, and includes some timeless quotes on the distinction between investing and speculation from the father of value investing, Ben Graham.  Here’s one excerpted from December 17, 1959:

Speculators often prosper through ignorance; it is a cliché that in a roaring bull market, knowledge is superfluous and experience a handicap. But the typical experience of the speculator is one of temporary profit and ultimate loss. Optimism and confidence have always accompanied bull markets; they have grown as the bull market advanced, and they had to grow, otherwise the bull markets could not have continued to their dizzy levels – and they have been replaced by distrust and pessimism when the bull markets of the past have collapsed. All my experience goes to show that most investment advisers take their opinions and measures of stock values from stock prices. In the stock market, value standards don’t determine prices; prices determine value standards.

The more it changes, the more it’s the same thing. The economic world has changed radically and will change even more. Most people think now that the essential nature of the stock market has been undergoing a corresponding change. Would that fact assure the investor against a costly and discouraging bear market experience? It seems to me that this is most improbable. The central level of values will be raised, but the fluctuations around these levels may well be just as wide as in the past, in fact, one might expect even wider fluctuations – the stock market will continue to be a place where a big bull market is inevitably followed by a big bear market. In other words, a place where today’s free lunches are paid for doubly tomorrow.

Typical of a rising market cycle, many participants today believe, or have been told, that they aren’t worried about extreme valuations or downmarket ‘fluctuations’ because asset prices always go up over time.  The relevant questions are over what time?; and how long can the owner wait for their savings to recover?

When prices don’t bounce back within weeks and months, it is common for loss tolerance to evaporate and for holders to sell long before any recovery.

For all those who think they are investing today at the worst asset valuations in a century, Hussman offers some smelling salts:

Don’t kid yourself…If your exposure to stocks doesn’t meaningfully take account of valuations here, you’re a speculator…If your speculation is based primarily on the fact that prices have gone up in the past, it’s very likely that you’re speculating recklessly.

Posted in Main Page | Comments Off on Typical speculator experience: temporary profit and ultimate loss




