Danielle’s bi-weekly market update

Danielle was a guest with Jim Goddard on Talk Digital Network, talking about recent developments in the world economy and markets.  You can listen to an audio clip here.

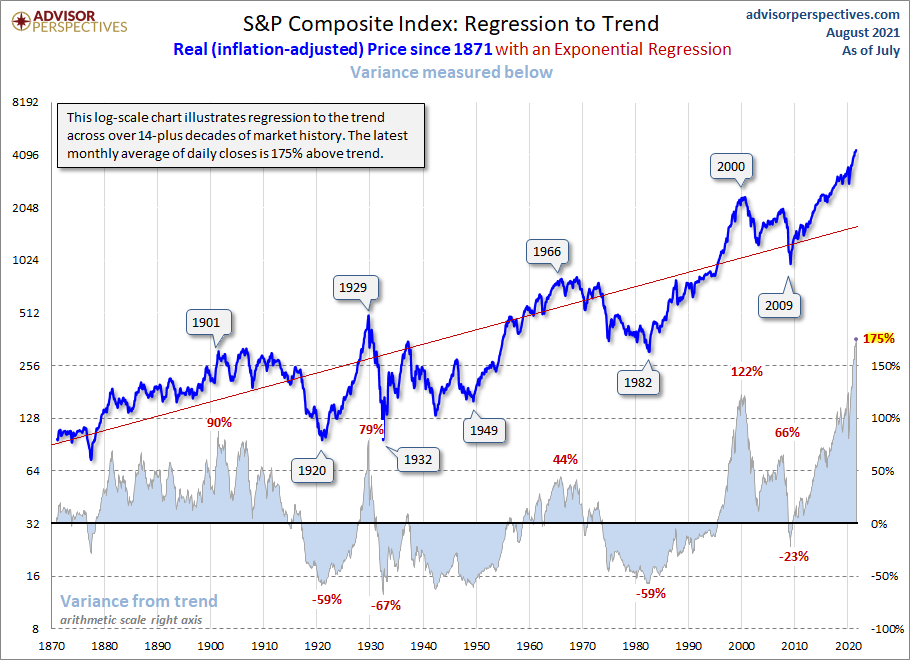
As mentioned in the segment, the chart below shows the real price change in the S&P 500 since 1870 (in blue) along with the 151-year trend in red.  With the latest monthly close 175% above the long-term mean, a down cycle that takes prices well below the red line would be in keeping with what followed past secular tops (1901, 1929, 1966, and 2000). Unlike the quick 2009 rebound, however, time below the mean in past cycles has been measured in years as this is needed to correct for the prior period of speculative fervour.

Posted in Main Page | Comments Off on Danielle’s bi-weekly market update

Doing today what will benefit us in the future

The U.S. government is working toward a bipartisan plan for $550 billion in infrastructure spending over the next five years (you can see the details and how it will be financed here.) It’s a tiny start on the trillions in this type of investment needed.

Today’s test for all developed economies is how to transition the private and public sectors from a 40-year fixation on excessive consumption and short-term financial targets (that ignore full-cost accounting) toward longer-term thinking and productive investments that lower costs/waste and increase resources/sustainability.

Sustaining health and prosperity requires doing things today that our future selves and generations will benefit from.

If you have not yet seen it, the 3-part documentary Myth & Mogul: John DeLorean on Netflix is worth watching and reminds us of how the obsession with status and consumption works to defeat innovation and longer-term viability.  You can see the trailer here.

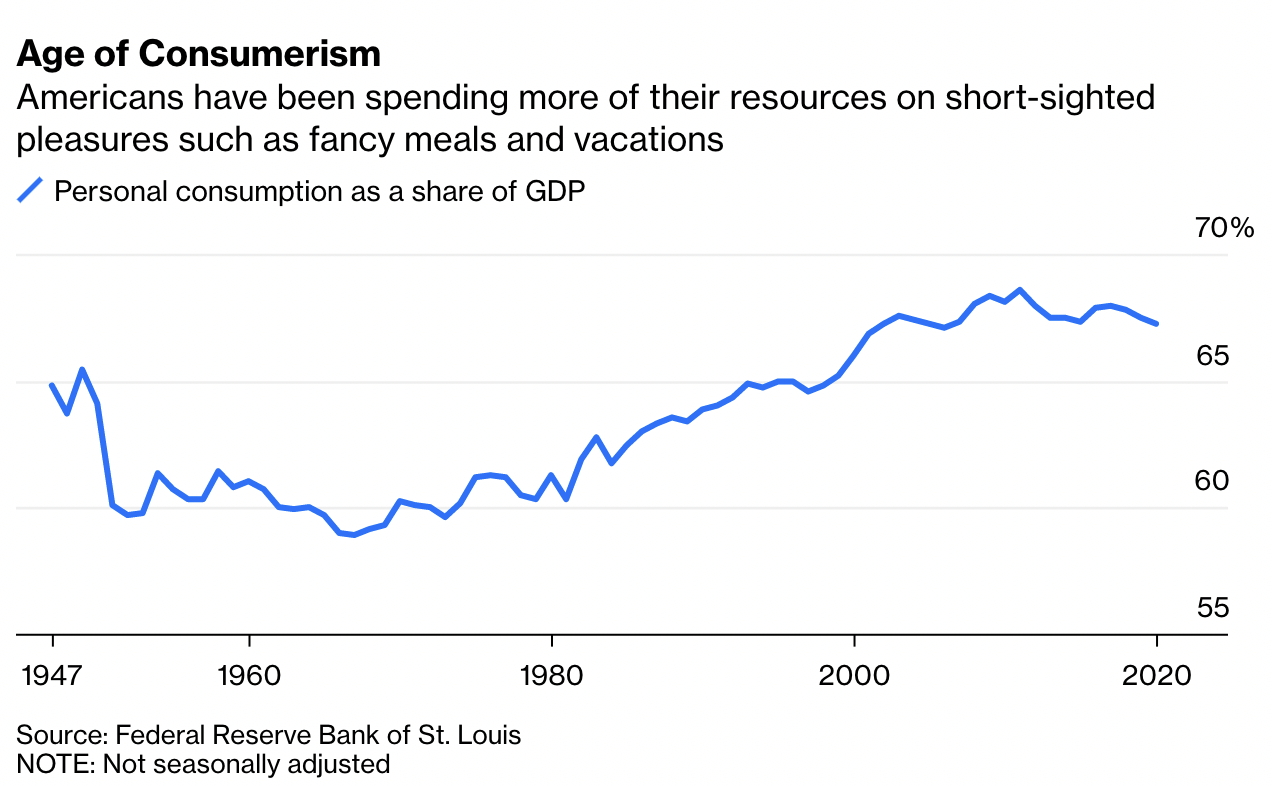
As shown in the charts below, private and public investment as a share of  US GDP has declined since the 1980s, as spending on personal consumption has risen. Similar trends have persisted in most developed economies.  See America squandered decades living for the moment:
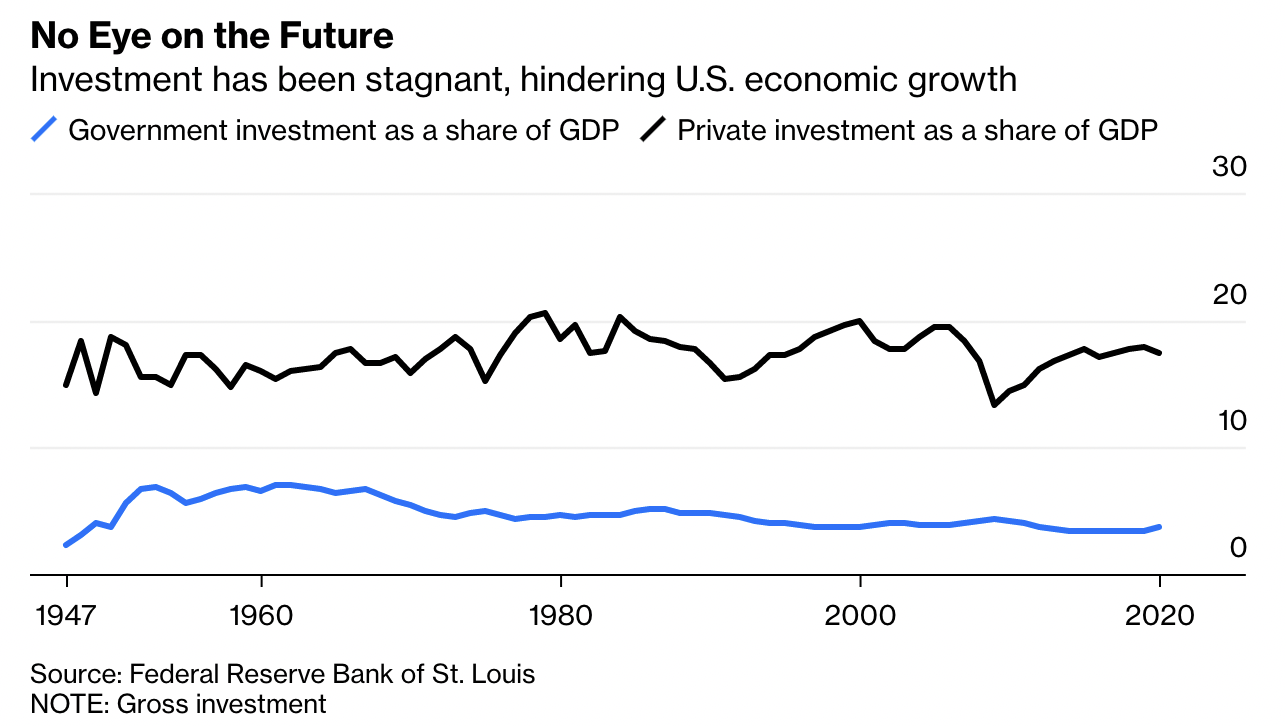
Every society faces a fundamental tradeoff between consuming now and consuming later.

There’s a finite amount of labor, materials and other resources in the economy, which can be used either to produce goods and services for consumption — fancy meals, nice vacations, and so on — or to produce capital goods like machine tools, roads, and business software. The more a society invests in the latter,  the more it increases its productive power — and therefore its wealth — in the future.

Fortunately, disruptive technologies are here to enable us in this process now more than ever before.  Plans and blueprints are already in place.  What we spend and allocate now must serve the larger plan or we are working at cross purposes.  See details in the latest ReThinkx Report: Disruption, Implications and Choices:

By supporting the clean disruption of energy, transportation, and food, societies can choose to accelerate global greenhouse gas mitigation to reach net zero emissions before 2040 and lay the groundwork for a complete solution to climate change, simultaneously saving trillions of dollars and improving prosperity and quality of life worldwide.

Posted in Main Page | Comments Off on Doing today what will benefit us in the future

Bank lending flatlines as investment prospects dim

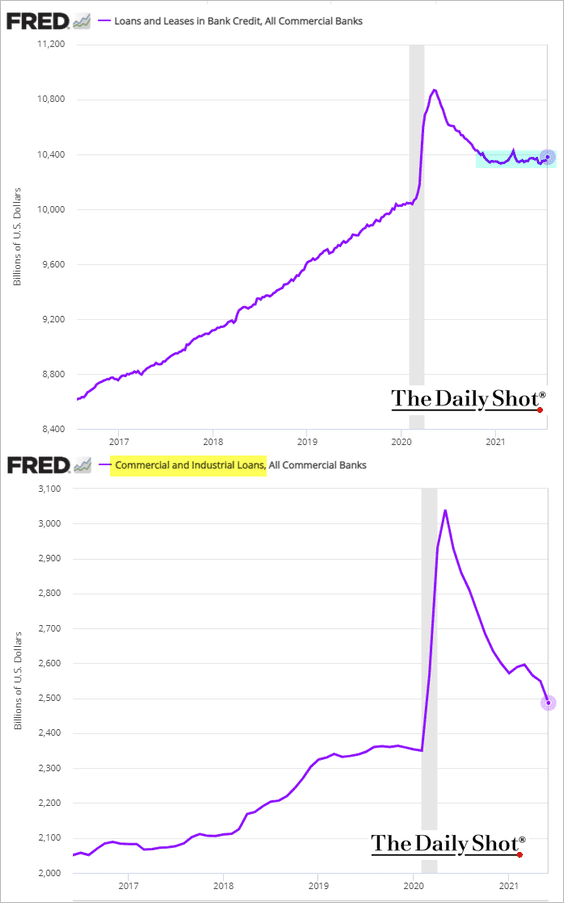
As we discussed in our July client letter “Tapped Out”, and here in Slowing Growth is Natural Product of Debt Hangover, a weakening credit impulse globally continues to bode poorly for economic momentum for the foreseeable future.

As shown below since 2016, the change in the flow of credit (commercial loans taken) has stalled over the last year notwithstanding trillions in cash injected into the lending system through central bank bond-buying.  Quantitative easing can flood banks with liquid reserves but it cannot make the private sector use it.

When corporations are debt-heavy and lacking in compelling domestic investment opportunities they have little incentive to seek new bank loans.

For their part, banks are in the business of only making loans that have a high probability of being repaid in full with interest.

As Richard C. Koo,  explains in The Other Half of Macroeconomics (2018):

“Once the bubble bursts and households and businesses are left facing debt overhangs, no amount of monetary easing by the central bank will persuade them to resume borrowing until their balance sheets are fully repaired. Some are badly traumatized by the years of painful deleveraging experience and may never borrow again—even after they restore their balance sheets…The fact that a number of central bank governors continue to insist that further monetary easing will enable them to meet their inflation targets suggests that they still do not understand why their models and forecasts have failed.”

Posted in Main Page | Comments Off on Bank lending flatlines as investment prospects dim