
Pent down demand weighs on global growth and inflation

June’s US consumer price index (including clothes, groceries, restaurant meals, recreational activities and vehicles) increased 5.4% from a year ago, the highest 12-month rate since August 2008.  The so-called core price index, which excludes food and energy, rose 4.5% year over year.  The seasonally adjusted 0.9% rise in June from May was the largest one-month change since June 2008 (a price peak that cycle).

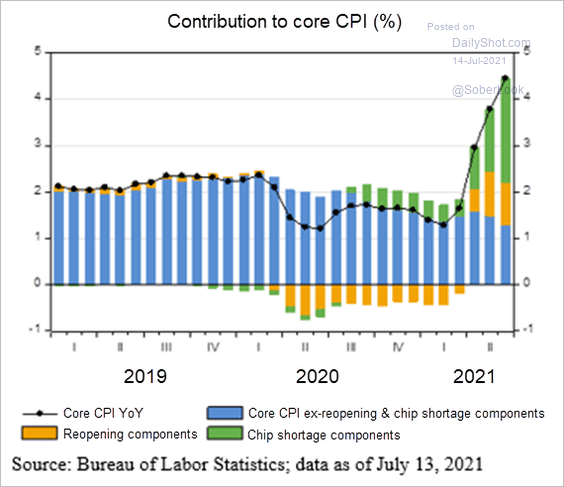
Accelerating prices for new and used cars (driven by a surge in demand and constricted supply during the pandemic) and gains in prices for lodging and transportation services, including car and truck rentals (reopening components), contributed to the vast majority of the core CPI increase.  As shown below, since 2018, core CPI (ex reopening and chip shortage components) has actually been declining since April (blue bars).   Lest anyone forget, vehicles are the largest ticket item in the durable goods category, and durable goods are so-named because they last longer than three years.  By definition, then, record durable goods demand over the last year is unlikely to be repeated for a few years, at least.
As David Rosenberg noted yesterday, the S&P 500 household durable goods stock composite has sagged nearly nine percent from the nearby highs as service spending picks up:

“…this is important since the former represents a US$2.4-trillion chunk of GDP, or four times the size of the latter. And within the “reopening” subsectors, only retailing and restaurants are behaving well, while office real estate investment trusts, airlines, hotels and casinos have rolled over considerably.”

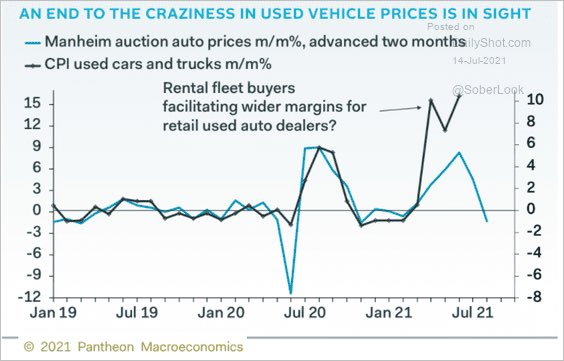
According to the Conference Board, consumer plans to purchase a vehicle in the next six months remain down year-over-year, and the index of consumer sentiment from Morning Consult ended June (down 0.6% from May, which ended down 0.9% from April) 12.1% below Feb. 29, 2020 levels.  As shown on the left, auto auction data suggest that used vehicle prices are now likely to move lower in the months ahead, as pent-down appetite weighs.
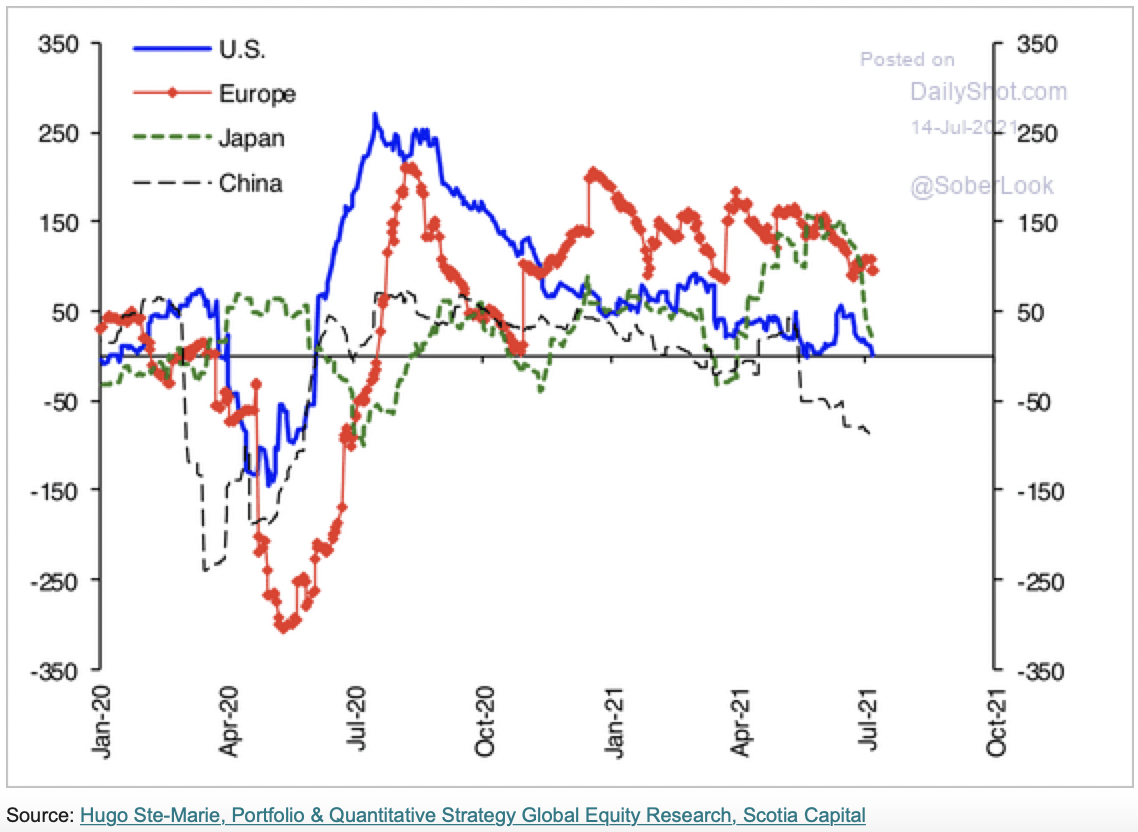
Slowing demand is already evident in weakening economic surprise indices for the world’s largest economies since last summer, as shown below.  First-in and out of COVID-19 shutdowns, the weakening in China’s economy and price data year-to-date is noteworthy and prompted a surprise decision from China’s central bank (PBOC) last week to try and expand lending by lowering reserve requirements (RRR) for its banks effective July 15.  The PBOC is now expected to deliver further cuts in the RRR as pressure on the economy persists, and consumer inflation eases (latest Reuters poll).
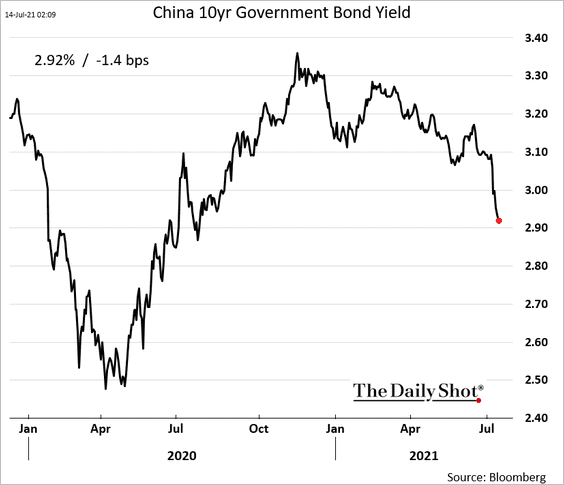
As with North American Treasury yields, the 10-year yield in China has been falling again since March 2021, and at 2.92%, remains well below its 3.22% level before the global recession hit in early 2020 (shown on the left).
At the same time, lumber continues to deflate with futures at $558 per thousand board feet this morning, down 67% since early May, as demand cools and production expands.

The US dollar has been strengthening against the basket of its major trading partners since May.  A rising dollar is deflationary for America but inflationary for those importing its goods.  This adds to headwinds for developing economies like Russia, Brazil, Turkey and many others who then find they need to raise interest rates to support their currencies and combat a rising cost of goods–slowing the global economy in the process.

Central banks and record levels of debt have not arrested the economic/financial cycle–what magnified the up will also magnify the down.  Understanding this is essential risk management.

Posted in Main Page | Comments Off on Pent down demand weighs on global growth and inflation

Monetary policy impotent during a balance sheet recession

Between 2008 and 2019, excess capacity, slow growth and never-ending central bank liquidity injections suppressed interest rates and encouraged corporations to magnify profits by increasing their debt.  This meant that the corporate sector came into the 2020 recession with record indebtedness.

As central banks flooded financial markets with even more liquidity over the past 16 months, interest rates/yields fell to the lowest level on record and companies borrowed even more.  Nonfinancial companies issued $1.7 trillion of bonds in the U.S. alone last year, nearly $600 billion more than the previous high (Dealogic). By the end of March, non-financial debt reached $11.2 trillion (Federal Reserve), about half the size of the U.S. economy.  See Pandemic Hangover:  $11 Trillion in Corporate Debt.

With global demand/capacity utilization rates still well below 2019 trends and uneconomical pricing for most assets everywhere, compelling capital expenditure opportunities are now scarcer than cash.  As the economy rebounds from the depths of the pandemic shutdown, many business models are in flux and downsizing of commercial/office space is a common theme.  Using cash to reduce debt is the logical move.

A similar impulse has been evident in US households since the 2008 crisis as home prices slumped with investment yields and an aging population increasingly values financial stability more than discretionary spending.

According to the New York Fed, US households spent just 29%, 26% and 25% of the three pandemic stimuli cheques over the last year, with the balance used to increase savings (which includes paying down debt).  Deleveraging strengthens corporate and household balance sheets but detracts from Gross Domestic Product and increases the need for government spending as an economic stabilizer.

Economist Richard Koo’s 2009 book The Holy Grail of Macro Economics:  Lessons from Japan’s Great Recession explains the 15-year long recession that followed the bursting of Japan’s real estate, debt and stock market bubbles in 1989 and compares it with the US market crash of 1929, the Great Depression and the 2008 Financial Crisis.  The book stimulates much food for thought about our current cycle globally.

Koo uses a century of history to show that when the corporate and household sectors are striving to reduce debt and rebuild balance sheets, monetary prods cease to stimulate spending.  The payback period is both painful and essential:

“…one of the key characteristics of a balance sheet recession…is that monetary policy becomes useless.  People in Japan have already experienced this first-hand:  monetary policy had no effect, even though interest rates remained at our near zero from 1995 to 2005.  The stock market did not rally, and the economy did not recover.   In contrast, the late 1980s asset-price bubble happened when the official discount rate stood at 2.5 percent.  Yet just a few years later, in February 1993, the same policy rate of 2.5 percent had no stimulative impact whatsoever.  Nor, subsequently, did an interest rate of 0 percent.”

Posted in Main Page | Comments Off on Monetary policy impotent during a balance sheet recession

Grantham: climate is the “race of our lives”

When legendary value investor Jeremy Grantham turned 80, he made two resolutions: “to be prepared to write a cheque up to the limits of your ability”, and to “say what you think you should say to everybody”…

In this week’s show, Grantham shares his views on climate change, why he calls it the “Race of Our Lives,” and how he is investing to combat it. Here is a direct video link.

DP note: Grantham’s foundation and the ESG fund he describes are mandated to be fully invested with 30 year plus time horizons.  Grantham describes new business ventures and technologies in this segment but also warns repeatedly that most assets are presently suffering from bubble pricing with greater downside than upside prospects from present levels.  Few individuals have the luxury of decades where they can wait to make back capital losses and not require income or withdrawals in the interim.  It’s important to remember that even world-changing technology and companies can be capital destructive over relevant time frames when bought near cycle peaks.  For individuals, it is pragmatic to define sectors and percentage targets for allocation while waiting for repricing cycles to bring investment-grade entry points before committing capital.

Posted in Main Page | Comments Off on Grantham: climate is the “race of our lives”





