Herd immunity threshold rising with morphing virus

As many are vaccinated and a significant portion are determined not to be, the virus is taking every opportunity to morph.  Dreams of COVID-19’s mayhem ending any time soon look unrealistic, see Delta Seen to Push Herd Immunity Threshold above 90%.

The spread of the delta coronavirus variant has pushed the threshold for herd immunity to well over 80% and potentially approaching 90%, according to an Infectious Diseases Society of America briefing on Tuesday.

That represents a “much higher” bar than previous estimates of 60% to 70%, because delta is twice as transmissible, said Ricardo Franco, an assistant professor at the University of Alabama at Birmingham.

“It is becoming clear that this is a very dangerous, way more dangerous virus than the original one,” Franco said.

Posted in Main Page | Comments Off on Herd immunity threshold rising with morphing virus

Slowing growth is natural product of debt hangover

In 1933, Irving Fisher, one of America’s most influential economists, noted that economic growth declines in highly indebted economies because debt increases current spending in exchange for a decline in future expenditures unless the debt is self-financing, i.e., helping to generate an income stream that repays the principal and interest.  Thus, debt borrowed for personal consumption, including housing, reduces savings for investment and future growth. The accelerated consumer spending over the past year was always to be short-lived as households now spend years paying down the additional debt.  For a good update on the latest data, see Disappointing Growth Shows Stimulus Diminishing Returns.

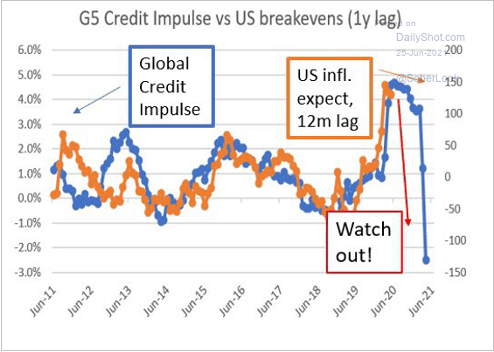
‘Credit impulse’ is a 2008 term coined by Michael Biggs, then an economist at Deutsche Bank, when he noted that the most critical variable in terms of forecasting GDP growth is not the change in the availability of credit but rather the change in the flow of credit (loans taken) as a percentage of GDP.  As shown on the left in blue, the credit impulse peaked globally last June and has plunged since. Inflation expectations (in orange) are set to follow.

No one should be surprised that economic growth is quickly cooling and treasury yields slumping once more.  Irrationally inflated equity and corporate debt prices are next to get the memo.

Posted in Main Page | Comments Off on Slowing growth is natural product of debt hangover

Inflation and interest rates: all roads lead back to Rome

A. Gary Shilling’s excellent August Insight is out today (subscription only); some takeaways can be found in his recent Bloomberg Quint article here: With bond yields, something has to give, here’s the punch line:

The yield on the benchmark 10-year U.S. Treasury note averaged 0.79% from 2007 through last year after adjusting for inflation as measured by the consumer price index. It’s now minus 4.0%. If that’s not shocking enough, corporate bonds rated below investment grade, or junk, yield 4.57%, below the current 5.40% rate of inflation. Something’s got to give. To return to more normal conditions, either nominal yields must rise or inflation must recede. Bet on the latter.
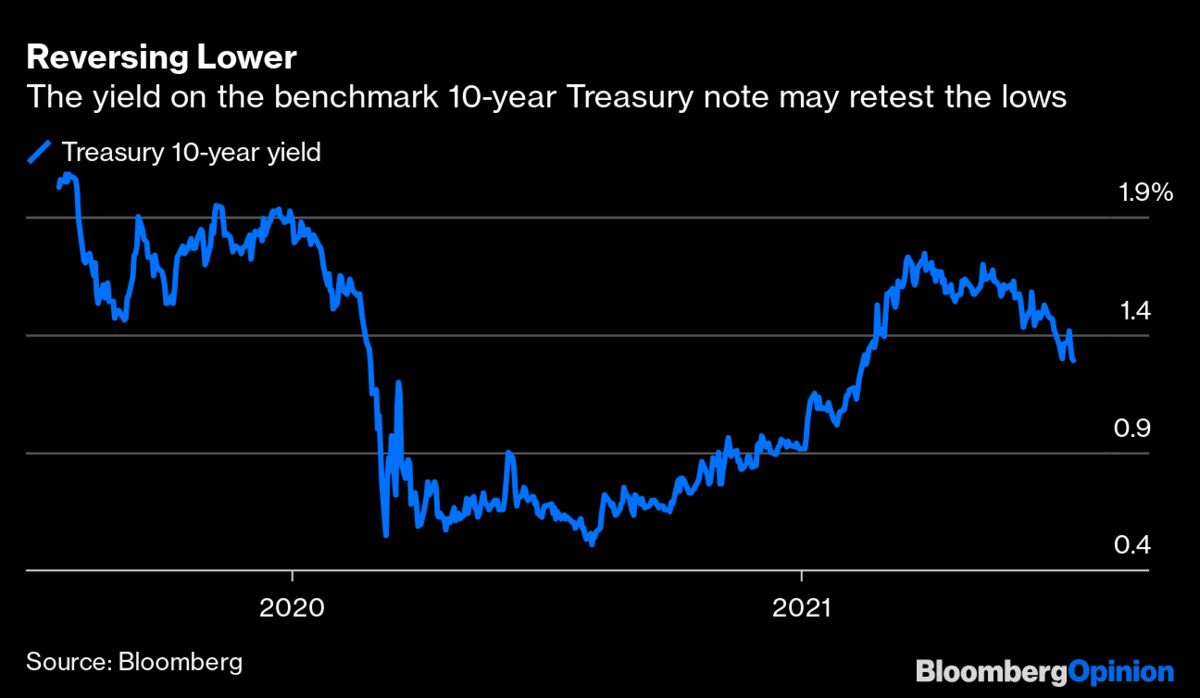
While the risk-sellers continue their standard refrain that Treasuries are for dummies because inflation and interest rates are only headed higher, the reality is that higher rates are self-correcting in a global system where households, corporations and the investor class are all cash-light and heavily levered on the same inflated asset prices together.  This makes the financial system highly interrelated and vulnerable to a psychological shift or demand shock at every moment.

In its latest 2021 Financial System Review, the Bank of Canada warns of contagion risks where buyer exhaustion, a crash in the stock market, cryptocurrencies or a weakening of international trade are just a few of many things that threaten a circular impact where home prices and incomes fall, contracting the entire economy.

In our massive global leverage cycle for the history books, all roads now lead to Rome:  debt-fuelled pandemic spending inflated prices over the past year and brought forward future spending.  In so doing, this has deflated future consumption power and demand, which suppresses longer-term inflation and interest rates–lower for longer.

Posted in Main Page | Comments Off on Inflation and interest rates: all roads lead back to Rome






